W-8BEN-E and W-8BEN in Georgia: LLC and Individual Entrepreneur Under the 1973 US–USSR Treaty
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Treaty articles and rates on this page are checked against the 1973 US–USSR convention and IRS Tax Treaty Table 1 (Rev. May 2023), which lists Georgia among the countries to which the U.S.-U.S.S.R. income tax treaty still applies. Signed at Washington on 20 June 1973, in force from 29 January 1976. Last checked: 05.11.2026.
 AI-generated image
Most W-8BEN-E guides assume a modern treaty: Article 7 for services, 5% or 15% on dividends. Georgia (the country) has no such treaty with the United States.
IRS Tax Treaty Table 1 lists Georgia (the country) among the countries to which the U.S.-U.S.S.R. income tax treaty still applies. The text is ussr.pdf, signed at Washington on 20 June 1973 and in force from 29 January 1976. Last checked: 05.11.2026.
An LLC or a joint stock company files Form W-8BEN-E. An individual entrepreneur files Form W-8BEN, with or without small-business status, because that person is not a separate company: start the W-8BEN wizard.
Or skip the reading and start the W-8BEN-E wizard. A signature-ready PDF is $30 for a company and $5 for an individual.
Blank form or already filled in?
You can download the official, blank form from the IRS and complete it yourself — or get the same file already filled in by the wizard.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for an LLC or a joint stock company.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for an individual entrepreneur.
- The convention the IRS applies: ussr.pdf on IRS.gov, signed at Washington on 20 June 1973, in force from 29 January 1976. There is no separate income-tax treaty.
- Already filled in (5–10 minutes): W-8BEN-E for a company ($30) or W-8BEN for an individual ($5).
Which form does the business file?
The form follows the person who owns the income, not the platform that asked for a document.
- LLC and joint stock company: Form W-8BEN-E. A single-member LLC is still a company for this form.
- Individual entrepreneur: Form W-8BEN. Small-business status does not create a separate person.
- Branch of a foreign company: The foreign parent is the person claiming the income. The parent files the form that matches the parent.
- US citizen or green-card holder in Tbilisi: Form W-9. A W-8 series form is for a person who is not a US person.
Chapter 3 on Line 4 is a separate question from which form you picked. The next sections are residence, then that classification.
A foreigner who lives in Georgia (the country)
Treaty benefits follow tax residence, not the passport. A citizen of Ukraine, Poland, or another country who is a tax resident of Georgia (the country) and claims the treaty writes Georgia on Line 9 of Form W-8BEN. That person does not claim the treaty of the country of citizenship.
- Residence is a local question: The convention counts an individual resident in the country for purposes of its tax (Article II(3)(b)), so the tax rules of Georgia (the country) decide. The rules of the country of citizenship may have their own answer.
- Still resident in the country of citizenship: See an adviser. This page does not decide whether you are a tax resident of Georgia (the country).
- A company: The convention counts a legal entity, or another organization treated there as one for tax purposes, created under the laws of the country (Article II(3)(a)). An LLC or a joint stock company registered in Georgia (the country) meets that; a company registered elsewhere and run from Tbilisi does not.
- What the form names: Line 9 of Form W-8BEN, or Line 14a of Form W-8BEN-E, names Georgia (the country) when the tax residence is there and the payee claims the treaty. The form has no place for the name of the convention.
What the payer withholds without the form
Without a valid form, a US payer generally withholds 30% of the gross US-source payment. Work a company does in Georgia (the country) is not US-source: Part III (Lines 14a, 14b and 15) of Form W-8BEN-E stays blank. Services a company performs in the United States are Article 4(1) at 0% when the income is not derived by a representation there. An individual's work done from Georgia (the country) leaves Part II (Lines 9 and 10) of Form W-8BEN blank; pay for services performed in the United States is claimed under Article 6(2) on Form 8233, not Form W-8BEN. Copyright royalties, including software, are Article 3(1)(a) at 0%. Dividends stay at 30% because this convention has no dividends article.
The form goes to the US payer (the client, platform, or broker). It is not filed with the Revenue Service and it is not filed with the IRS. It only documents the withholding rate at source. This page does not promise a refund of tax already withheld.
Chapter 3 (Line 4): which box the entity checks
Georgia (the country) is not on the per se list in 26 CFR 301.7701-2(b)(8)(i). The default below is the classification with no Form 8832 on file.
| Entity | Line 4 | Notes |
|---|---|---|
| LLC, including a single-member LLC | Corporation | Corporation by default. A single owner does not make it a disregarded entity. Disregarded treatment requires a filed Form 8832. |
| Joint stock company | Corporation | Corporation by default. Not a per se corporation. Form 8832 remains available. |
| Partnership | Partnership | Check Partnership. |
| Individual entrepreneur | Form W-8BEN | Not a separate person. Small-business status does not change the form. |
| Small business, International Company, Virtual Zone Person | No change | These are tax regimes. They do not change the Chapter 3 classification. |
The sample LLC below is Corporation on Line 4 and Active NFFE on Line 5.
The address and the number: Lines 6 and 9b of W-8BEN-E, Lines 3 and 6a of W-8BEN
On Form W-8BEN-E, Line 6 is the address in Georgia (the country) and Line 9b is the foreign TIN. On Form W-8BEN, Line 3 is the address and Line 6a is the foreign TIN; that form has no Line 9b. For treaty benefits, the foreign TIN is enough. A US EIN is not required. An individual entrepreneur writes a personal number on Form W-8BEN, not a company identification code.
| Number | Where it goes |
|---|---|
| Company identification code | Line 9b of Form W-8BEN-E. Usually nine digits, from the registry. The sample uses 405123987, which shows the shape only. |
| Personal number of a citizen | Line 6a of Form W-8BEN. Usually eleven digits. The shape only is 01024057381. It is not a company identification code. |
| Number from the Revenue Service for a non-citizen | Line 6a of Form W-8BEN, when that is the tax number. Usually nine digits. A residence card or other identity card is not this number. |
| US EIN | Not required for treaty benefits. The foreign TIN is enough. |
405123987 and 01024057381 show the number of digits only. They are not real identification codes.
What a completed W-8BEN-E looks like for an LLC
An example: Kartli Tech LLC, whose staff perform software services on site in the United States, Active NFFE, income not derived by a representation there, Article 4(1) at 0% on those services, Line 14b No LOB article in treaty. Work done only in Georgia (the country) would leave Part III blank.
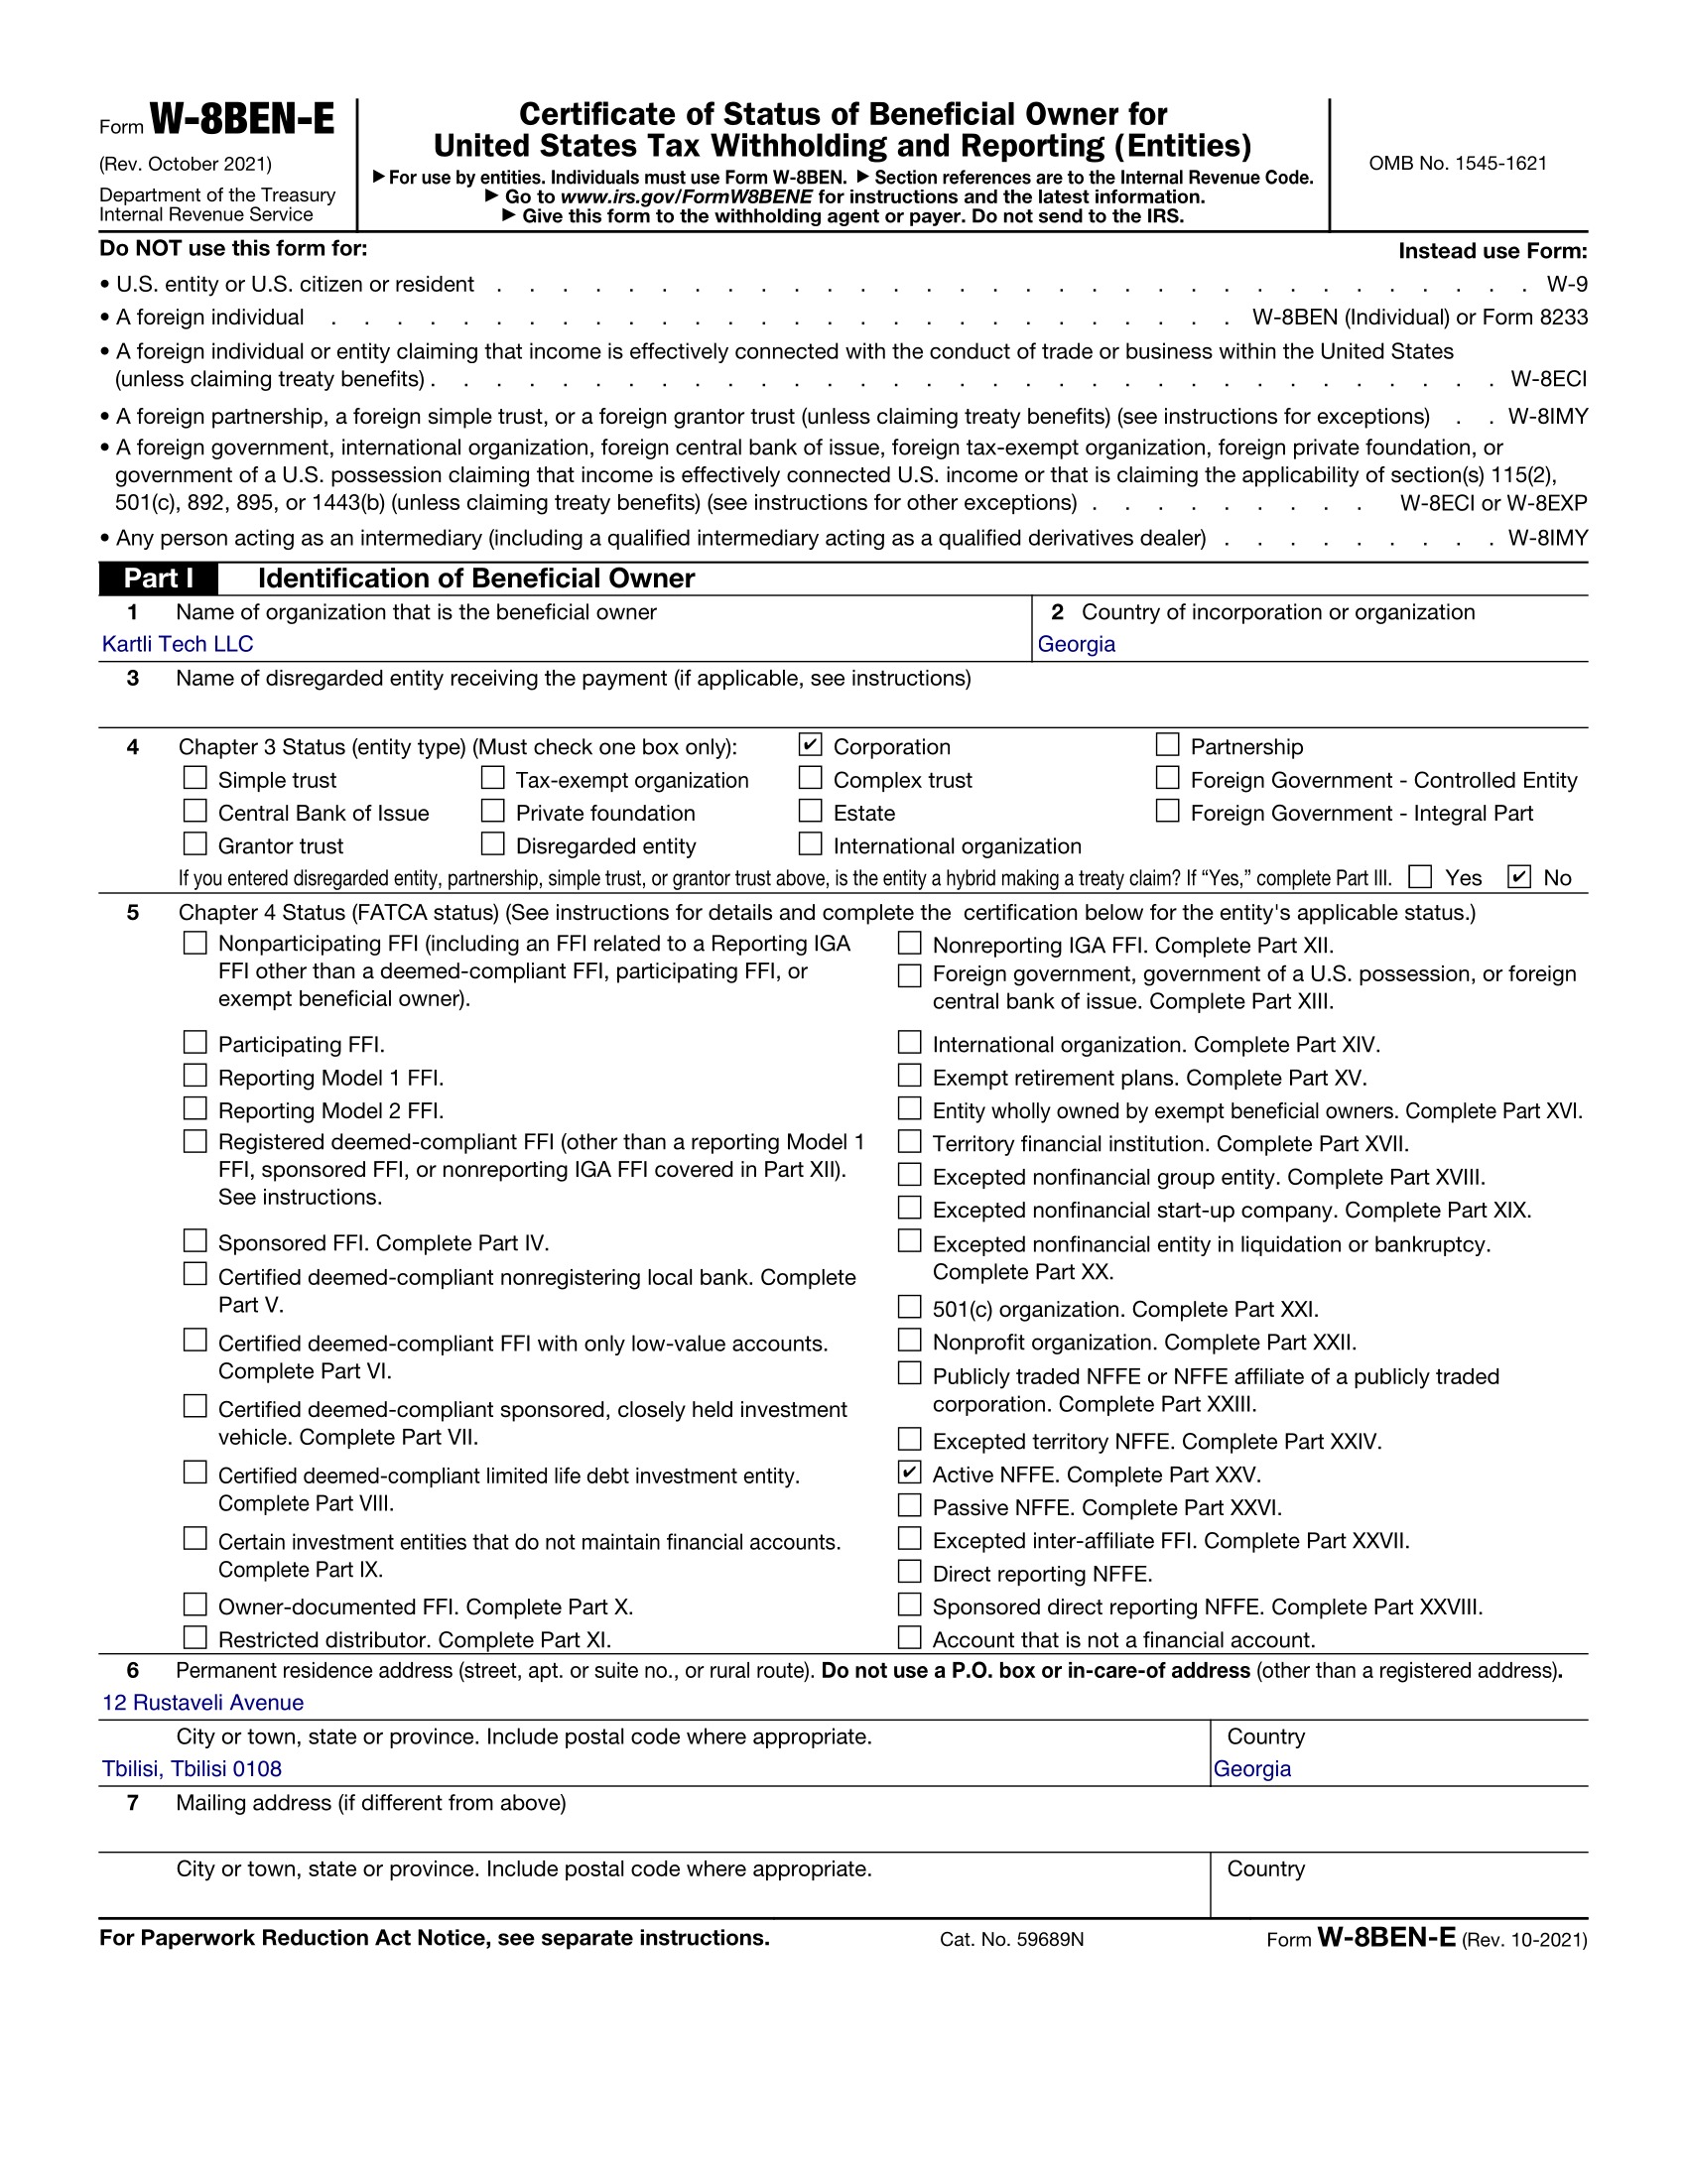
For illustration only. Sample facts: Kartli Tech LLC, 12 Rustaveli Avenue, Tbilisi 0108, identification code 405123987, Chapter 3 Corporation, Active NFFE, Part III Georgia, Line 14b No LOB article in treaty, Line 15 Article 4(1), 0%, services performed in the United States. Signed by Giorgi Beridze. The name, address, and identification code are fictional.
Rates by income type
Each row is the US withholding rate for that income when the condition in the last column is met. The treaty text uses Roman numerals. Line 15 of Form W-8BEN-E, and Line 10 of Form W-8BEN, use the Arabic digits, with the paragraph.
| Income | Article (W-8BEN-E Line 15 / W-8BEN Line 10) | US rate | Condition |
|---|---|---|---|
| Services by a Georgian LLC performed in the US | Article 4(1) (IV(1)) | 0% | Only if the income is not derived by a representation: an office or other place of business the LLC established in the US under US laws. Work done from Georgia is not US-source income at all: Part III (Lines 14a, 14b and 15) stays blank. |
| Technical services under an installation contract, performed in the US | Article 3(1)(d) (III(1)(d)) | 0% | Engineering, architectural, designing and other technical services in connection with an installation contract with a US resident, carried out in a period not exceeding 36 months at one location. Holds with or without a representation (Article IV(5)). An individual's pay for this work goes on Form 8233, not W-8BEN Line 10. |
| Services supplied in the US through a broker or independent agent | Article 3(1)(e) (III(1)(e)) | 0% | Through a broker, general commission agent or other agent of independent status acting in the ordinary course of its business. Holds with or without a representation (Article IV(5)). An individual's pay for this work goes on Form 8233, not W-8BEN Line 10. Gain from selling goods is not FDAP income, so no US withholding applies to it. |
| Services by an individual performed in the US | Article 6(2) (VI(2)), on Form 8233, not W-8BEN Line 10 | 0% | Only if present in the US for no more than 183 days in the tax year. Work done from Georgia is not US-source income at all: Part II (Lines 9 and 10) stays blank. |
| Software licences, YouTube Partner Program, other copyright royalties | Article 3(1)(a) (III(1)(a)) | 0% | Includes computer programs, patents, trademarks, know-how. Website AdSense is pay for services, not a royalty: earned from Georgia, it leaves Part II (Lines 9 and 10) of Form W-8BEN or Part III (Lines 14a, 14b and 15) of Form W-8BEN-E blank. |
| Equipment rental | Article 3(1)(a) (III(1)(a)) | 0% | Industrial, commercial or scientific equipment. Unlike most treaties, equipment rental is in Article III, not business profits. The wizard's income list has no equipment type of its own: pick Royalties, then equipment, or Other income, then the rent or royalties item. |
| Gains on those rights or property, gains on inherited or gifted property, reinsurance premiums | Article 3(1)(b), 3(1)(c) or 3(1)(f) (III(1)(b), (c), (f)) | 0% | Subject to tax only in the residence state. In the wizard: Other income, then the item. |
| Interest on credits financing trade between the US and the C.I.S. (in the convention, the USA and the USSR) | Article 3(1)(g) (III(1)(g)) | 0% | Not for interest from a general banking business in the US. |
| Other interest | — | 30% | No treaty rate for other interest paid to a resident of Georgia (the country). US domestic law may exempt it, for example portfolio interest or interest on bank deposits. Ask an adviser. |
| Dividends from US shares | — | 30% | No dividends article at any ownership percentage. US-source dividends paid to a resident of Georgia (the country) stay at the statutory 30%. |
| Pensions, annuities, social security | — | 30% | No article (IRS Tax Treaty Table 1). Article VI(1)(a)(1) covers remuneration from government funds paid to a citizen of the paying state and names no pension. |
| Rent from US real property | — | 30% | No article. Article III(1)(a) names rentals only for works, rights, equipment and know-how. |
| Stipend or scholarship of a student temporarily in the US | Article 6(1)(d) (VI(1)(d)), W-8BEN Line 10 only | 0% | Only an amount necessary to provide for ordinary living expenses, for a primary purpose of studying at an educational or scientific research institution or of acquiring a profession or a specialty, for no longer than that purpose requires and not more than 5 years. The amount is set in each case, generally below $10,000 a taxable year. Pay for teaching, research or other personal services goes on Form 8233. |
The treaty text uses IV, VI, and III. On Form W-8BEN-E, write the article with its paragraph, such as Article 4(1) or Article 3(1)(a). Article 6(2) goes on Form 8233. Do not copy a 5% or 15% dividend rate from a modern treaty. There is no dividends article.
Line 14b: there is no limitation-on-benefits article
With a treaty claim, check “No LOB article in treaty”. The 1973 convention has no limitation-on-benefits article. Do not check Active trade or business. That box belongs to treaties that have the article.
A blank IRS form, or a filled PDF?
The blank form is free from the IRS. The wizard asks the questions for this convention and fills Line 14b and Line 15 from the same rates as the table above.
| Step | What you do |
|---|---|
| Blank form | Download W-8BEN-E or W-8BEN from irs.gov and complete every line yourself. |
| Line 15 | Only with a treaty claim. Write the article and paragraph from the table, such as Article 4(1) or Article 3(1)(a), with the rate. Do not write the Roman numeral. Article 6(2) goes on Form 8233. |
| Line 14b | Only with a treaty claim: No LOB article in treaty. Leave Active trade or business empty. |
| Wizard | {path|w8ben-e-form#wizard|W-8BEN-E ($30)} for an LLC or a joint stock company, or {path|w8ben-form#wizard|W-8BEN ($5)} for an individual entrepreneur. |
Frequently asked questions
Short answers for an LLC and for an individual entrepreneur paid from the United States.
Is there a US–Georgia tax treaty?
There is no separate income-tax treaty. IRS Tax Treaty Table 1 lists Georgia (the country) among the countries to which the 1973 U.S.-U.S.S.R. income tax treaty still applies. The text is ussr.pdf.
I'm a Ukrainian individual entrepreneur living in Tbilisi. Which treaty do I use?
If the person is a tax resident of Georgia (the country), a treaty claim names Georgia on Line 9 of Form W-8BEN, not Ukraine. Work done from Georgia leaves Part II (Lines 9 and 10) blank, and pay for services performed in the United States is claimed under Article 6(2) on Form 8233, not Form W-8BEN. This page does not decide whether a particular reader is a tax resident there. If the person is still a tax resident of Ukraine, see an adviser.
Why is my US broker withholding 30% on dividends?
This convention has no dividends article at any ownership percentage. The statutory rate is 30%. This page does not promise a refund of tax already withheld.
Do I need a US EIN?
No. For treaty benefits the foreign TIN is enough. A company writes the identification code, usually 9 digits, on Line 9b of Form W-8BEN-E. On Line 6a of Form W-8BEN, a citizen writes the personal number, usually 11 digits, and a non-citizen the number from the Revenue Service, usually 9 digits.
My platform asks for Article 7 / Article 12 — what do I write?
A company writes Article 4(1) for services performed in the United States; work done from Georgia (the country) leaves Part III (Lines 14a, 14b and 15) blank. Copyright royalties, including software, are Article 3(1)(a). In this convention Article VII is the taxation of citizens and Article XII is the exchange of information, so neither is the line to write.
Does small business status change anything on the form?
No. Small business status, an International Company, and a Virtual Zone Person are tax regimes. An LLC still files Form W-8BEN-E. An individual entrepreneur still files Form W-8BEN.
Which number goes on Line 9b?
Line 9b of Form W-8BEN-E takes the company's identification code, usually 9 digits, for example the shape 405123987. Form W-8BEN has no Line 9b: on its Line 6a a citizen writes the personal number, usually 11 digits, for example the shape 01024057381, and a non-citizen the number from the Revenue Service, usually 9 digits. An individual entrepreneur does not write a company identification code.
Which Line 14b box do I check?
With a treaty claim, No LOB article in treaty. Do not check Active trade or business. This convention has no limitation-on-benefits article.
Is equipment rental a business profit?
No. Under this convention, rent for industrial, commercial or scientific equipment is in Article III(1)(a) with copyright royalties. On the form that is Article 3(1)(a), at 0%. Rent from US real property is not in that paragraph and stays at 30%.
How long is Form W-8BEN-E valid?
Generally through the last day of the third calendar year after the year of signing, unless the facts on the form change. A form signed in 2026 is valid through 31 December 2029.
Related guides
The same 1973 convention for a Moldova company, plus the individual wizard.
- Moldova SRL: The same 1973 convention, in Romanian.
- Entity type on Line 4: Full guide to Line 4
- Individual entrepreneur: W-8BEN wizard ($5)
Common mistakes
- Article 7 or Article 12 from a modern-treaty guide: Company services performed in the United States are Article 4(1). Copyright royalties are Article 3(1)(a). In this convention Article VII is the taxation of citizens and Article XII is the exchange of information.
- The treaty of the passport country: A tax resident of Georgia (the country) claims the 1973 convention. Residence is not citizenship. This page does not decide a particular reader's residence.
- 5% or 15% on dividends: There is no dividends article. The statutory rate is 30% at any ownership percentage.
- Form W-8BEN-E from an individual entrepreneur: An individual entrepreneur files Form W-8BEN. The person is not a separate company. Small-business status does not change that.
- Active trade or business on Line 14b: With a treaty claim, check No LOB article in treaty. Work done in Georgia (the country) leaves Part III (Lines 14a, 14b and 15) blank. This convention has no limitation-on-benefits article.
- Roman numerals on Line 15: The treaty text uses IV, VI, and III. Form W-8BEN-E uses Article 4(1) and Article 3(1)(a), and Form 8233 uses Article 6(2).
- An identity card instead of the tax number: On Line 6a of Form W-8BEN, a non-citizen uses the number from the Revenue Service, usually 9 digits, and a citizen the personal number, usually 11 digits. The shape only is 01024057381.
US withholding, not tax in Georgia (the country)
This page is about US withholding on payments to a company or an individual entrepreneur. It does not decide how Georgia (the country) taxes those profits.
Local tax on the income, once it is received, is a question for an adviser there. Form W-8BEN-E and Form W-8BEN only document what the US payer withholds.
Ready to finish the form?
The wizard asks the same questions as this page and suggests the article and rate for Line 15.