W-8BEN-E for a Hungarian Kft. After the US-Hungary Tax Treaty Ended (2024)
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Verified against IRS Announcement 2024-5 and the IRS "United States Income Tax Treaties - A to Z" list (last checked September 2026): the United States terminated the 1979 US-Hungary income tax convention. It ceased to apply to taxes withheld at source on January 1, 2024, and to other taxes for periods beginning on or after that date. Hungary no longer appears on the A-to-Z list, and no replacement treaty is in force. Every withholding figure on this page reflects ordinary US statutory rules, not the old treaty.
 AI-generated image
The US terminated its tax treaty with Hungary. Since January 1, 2024, there is no treaty rate to claim — here is what that actually changes for your Kft. (less than you think). If a US company, marketplace, or broker has asked your Kft. for Form W-8BEN-E, Part III (Lines 14–15) stays blank. There is no article to name and no reduced rate left to claim.
This guide is for a Hungarian company that invoices US clients or holds a US brokerage account. It covers the Kft. versus a Zrt. or Nyrt., why services performed in Hungary are still not US-source income, which number goes on Line 9b, and why copying a 1979 rate onto the form is the mistake to avoid. A sample PDF is included further down.
If you are an individual — an egyéni vállalkozó, not a Kft. — you file Form W-8BEN, not this one: start the W-8BEN wizard. Most natural persons use an adóazonosító jel (10 digits, starting with 8). A company uses an adószám. This page is for the company form.
If you prefer to skip the reading, you can start the W-8BEN-E wizard now — it already knows the US-Hungary treaty ended in 2024 and, by default, leaves Part III (Lines 14–15) blank. In a few minutes you have a signature-ready PDF for $30.
Blank form or already filled in?
You can download the official, blank form from the IRS and complete it yourself — or get the same file already filled in by our wizard.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for a Kft., Zrt., or Nyrt.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for an egyéni vállalkozó.
- Already filled in (5–10 minutes): W-8BEN-E for Hungarian companies ($30) or W-8BEN for individuals ($5) — the wizard already knows there is no treaty in force and, by default, leaves Part III (Lines 14–15) blank.
- IRS treaty list: United States Income Tax Treaties - A to Z — Hungary does not appear on this list.
- IRS Announcement 2024-5: Announcement 2024-5 — the 1979 convention ceased to apply to withholding on January 1, 2024.
What happened to the 1979 treaty
Hungary is not like Brazil, Singapore, or Hong Kong, which never had a comprehensive US income tax treaty. Hungary had one, and the United States ended it.
- 1979: The United States and Hungary signed an income tax convention. Older guides still quote its rates: 5% or 15% on dividends, and 0% on many kinds of interest and royalties.
- July 2022: The United States gave notice that it was terminating the convention.
- January 1, 2024: The convention ceased to apply to taxes withheld at source, and to other taxes for taxable periods beginning on or after that date (IRS Announcement 2024-5).
- 2026: No replacement treaty is in force. Hungary is off the IRS A-to-Z list. If a new convention enters into force later, this page will be updated.
Kft., Zrt., Nyrt., or an egyéni vállalkozó?
Hungarian company law uses several forms, and US tax classification does not follow the local abbreviation one-for-one:
- Korlátolt felelősségű társaság (Kft.): The usual limited-liability company. It is not on the IRS per se corporation list. It defaults to Corporation because its members have limited liability, and it can elect a different US classification by filing Form 8832. A single-member Kft. is not disregarded by default.
- Nyilvánosan működő részvénytársaság (Nyrt.): The public company limited by shares. 26 CFR 301.7701-2(b)(8)(i) lists "Hungary, Reszvenytarsasag" as a per se corporation. A Nyrt. is always a Corporation. There is no Form 8832 election.
- Zártkörűen működő részvénytársaság (Zrt.): The private company limited by shares. Since 2006 a részvénytársaság exists as a public Nyrt. and a private Zrt., and both forms fall under the same eCFR row. A Zrt. is also per se. It is not treated like a Kft., and it cannot elect out of Corporation status.
- Egyéni vállalkozó: A sole trader. Not a separate legal entity. The individual files Form W-8BEN, not W-8BEN-E, and the foreign TIN is an adóazonosító jel, not the company's adószám.
- Betéti társaság (Bt.) or közkereseti társaság (Kkt.): Partnership-style forms. Check "Partnership" in Part I, line 4, not "Corporation," unless a Form 8832 election says otherwise for an eligible entity.
The trap worth naming: a closed joint-stock company is still a részvénytársaság. In many countries only the public company is per se. In Hungary the private Zrt. is per se as well. A Kft. is the form that stays eligible for Form 8832.
Because the treaty is gone, the Chapter 3 box no longer unlocks a reduced rate. It still decides which form you file and how the payer reads the certificate.
Who actually needs to submit this form?
Any Hungarian Kft., Zrt., or Nyrt. that receives payments from a US business and needs to document that it is not a US person. Common situations:
- Invoicing US clients from Hungary: Your Kft. bills a US company for consulting, software, design, or similar work performed in Hungary.
- US payment platforms: Payouts from Stripe, Amazon, YouTube/AdSense, or similar US-headquartered platforms.
- A US brokerage account: A broker that holds US stock for a Hungarian company typically wants a current W-8BEN-E before it applies the statutory rate. An investor who is not a company uses Form W-8BEN and an adóazonosító jel, for example 8123456786.
- US-source dividends, interest, or royalties: These are the payments that moved from the old treaty rates to 30%. The form documents foreign status. It does not restore the 1979 rates.
What actually happens without a valid form — and what did not change
Without a submitted W-8BEN-E, the US payer generally withholds 30% of the gross payment under the Chapter 3 nonresident-alien presumption rules — not because it treats you as a US person. Filing the form does not unlock a treaty rate, because the treaty no longer applies.
For income that is genuinely foreign-source — the common case of a Kft. invoicing a US client for services performed outside the United States, from Hungary — US withholding tax does not apply at all, treaty or no treaty. The source-of-income rules look at where the work was performed, not where the client sits. That 0% result did not change in 2024. A W-8BEN-E in this case documents foreign status and Chapter 4 (FATCA) status so the payer does not withhold by mistake. Genuine US-source income is different: dividends on US stock, interest on most US instruments, and royalties for IP used in the United States are now withheld at the full 30% statutory rate. Sources that still cite 5% or 15% on dividends, or 0% on interest and royalties, are describing the terminated 1979 treaty.
What changed on January 1, 2024
The old convention is not a menu you can still pick from. This is the practical difference for a Hungarian resident:
| Income type | 1979 treaty | Since 2024 |
|---|---|---|
| Dividends on US stock | 5% or 15%, depending on the old ownership test | 30%. There is no treaty reduction. |
| Interest on most US instruments | Often 0% | 30%, unless a separate non-treaty rule applies. The portfolio interest exemption (IRC section 871(h)/881(c)) is a question for an accountant. It is not automatic, and it is not a treaty benefit. |
| Royalties for IP used in the US | Often 0% | 30%. There is no treaty reduction. |
| Services performed in Hungary | 0%, because the income was not US-source | Still 0%. Ending the treaty did not turn foreign-source service fees into US-source income. |
Do not route the same income through a company in a third country just to revive a treaty rate. Limitation on Benefits articles in those other treaties are written to deny that kind of restructuring. That is a question for a tax advisor, not a line on this form.
Form W-8BEN-E, line by line, for a Hungarian Kft.
The line numbers below match the current form (Rev. October 2021) for the standard case: an operating Kft., Active NFFE, with no treaty-benefits claim. Holding companies and financial institutions follow different rules on some lines.
| Line | What you enter |
|---|---|
| Line 1 | The legal name exactly as registered (e.g., "Danube Kft."). |
| Line 2 | Country of incorporation: Hungary. |
| Line 3 | Leave blank unless a single-member Kft. has filed Form 8832 to elect disregarded status (uncommon). A Nyrt. or Zrt. cannot make that election. |
| Line 4 | "Corporation" for a Kft. (the default), and also for a Nyrt. or a Zrt. (both per se). "Partnership" for a Bt. or Kkt. Never check "Corporation" for an egyéni vállalkozó — that person files Form W-8BEN. The hybrid-entity follow-up is usually "No" for an ordinary Kft. |
| Line 5 | Chapter 4 (FATCA) status — almost always "Active NFFE" for an ordinary trading or services company. Ask an accountant if the company mainly holds investments. |
| Line 6 | The registered office in Hungary, in Latin letters (e.g., Andrassy ut 10, fsz. 2, Budapest, 1061). |
| Line 7 | Leave blank if it matches line 6. |
| Line 8 | Leave blank unless the company has actually received a US EIN. |
| Line 9a | Leave blank unless the entity is itself a Foreign Financial Institution. |
| Line 9b | The company's adószám, for example 12345676-2-42 (eight digits, a VAT-status digit, and a two-digit tax-office code). Do not enter an individual's adóazonosító jel (10 digits starting with 8, for example 8123456786). That number belongs on Form W-8BEN. |
| Line 9c | In practice this is not checked for a registered Kft. — the tax authority already issued the adószám. |
| Line 10 | Leave blank unless the withholding agent specifically asked for a reference number. |
| Part II (Lines 11-13) | Not completed for an ordinary Kft. This part is only for a disregarded entity or a branch receiving the payment. Do not confuse it with the treaty claim. |
| Line 14a | LEAVE BLANK. There is no US-Hungary tax treaty in force, so there is no treaty country to cite. |
| Line 14b | LEAVE BLANK. Without a treaty there is no Limitation on Benefits test to certify. |
| Line 15 | LEAVE BLANK. Do not enter a 1979 article, a 5% or 15% dividend rate, or a 0% interest or royalty rate. Those figures describe a terminated convention. |
| Line 39 (Part XXV) | Check the "Active NFFE" certification, matching Line 5. |
| Part XXX | Signed by a managing director or other authorized person, with capacity stated. |
This reflects the Rev. October 2021 revision of Form W-8BEN-E. Cross-check the current IRS PDF before you submit.
Every field in the table above is filled in by our guided W-8BEN-E wizard from your answers — including the decision to leave Part III (Lines 14–15) blank.
Adószám or adóazonosító jel
Hungary issues two different numbers. Only one of them belongs on the company form.
| Point | What it means |
|---|---|
| Company adószám | The entity tax number. The sample shape is 12345676-2-42: an eight-digit core, one VAT-status digit, and a two-digit code for the tax office. That is the number on Line 9b of Form W-8BEN-E. |
| Personal adóazonosító jel | A 10-digit number that always starts with 8, for example 8123456786. It identifies a natural person. It goes on Form W-8BEN, not on the company form. |
| Why the old placeholder was wrong | A generic 10-digit string that does not start with 8 is neither an adószám nor an adóazonosító jel. Do not copy 1234567890 onto either form. |
| Egyéni vállalkozó | A sole trader is not a Kft. The person files Form W-8BEN and uses the adóazonosító jel. Filing W-8BEN-E because the person has a trade licence does not create a company. |
| Zrt. versus Kft. | A Zrt. is per se Corporation, the same eCFR row as a Nyrt. A Kft. defaults to Corporation and can still file Form 8832. Do not treat a Zrt. as if it were an eligible Kft. |
Read the adószám from the company's tax card before Line 9b. Keep the hyphens. Do not substitute a director's adóazonosító jel.
Sample: completed W-8BEN-E for a Hungarian Kft.
A filled example for a fictional Kft. with no US permanent establishment, Active NFFE status, and Part III left blank because the US-Hungary treaty ended in 2024. This is the same signature-ready PDF our wizard produces from the same inputs.
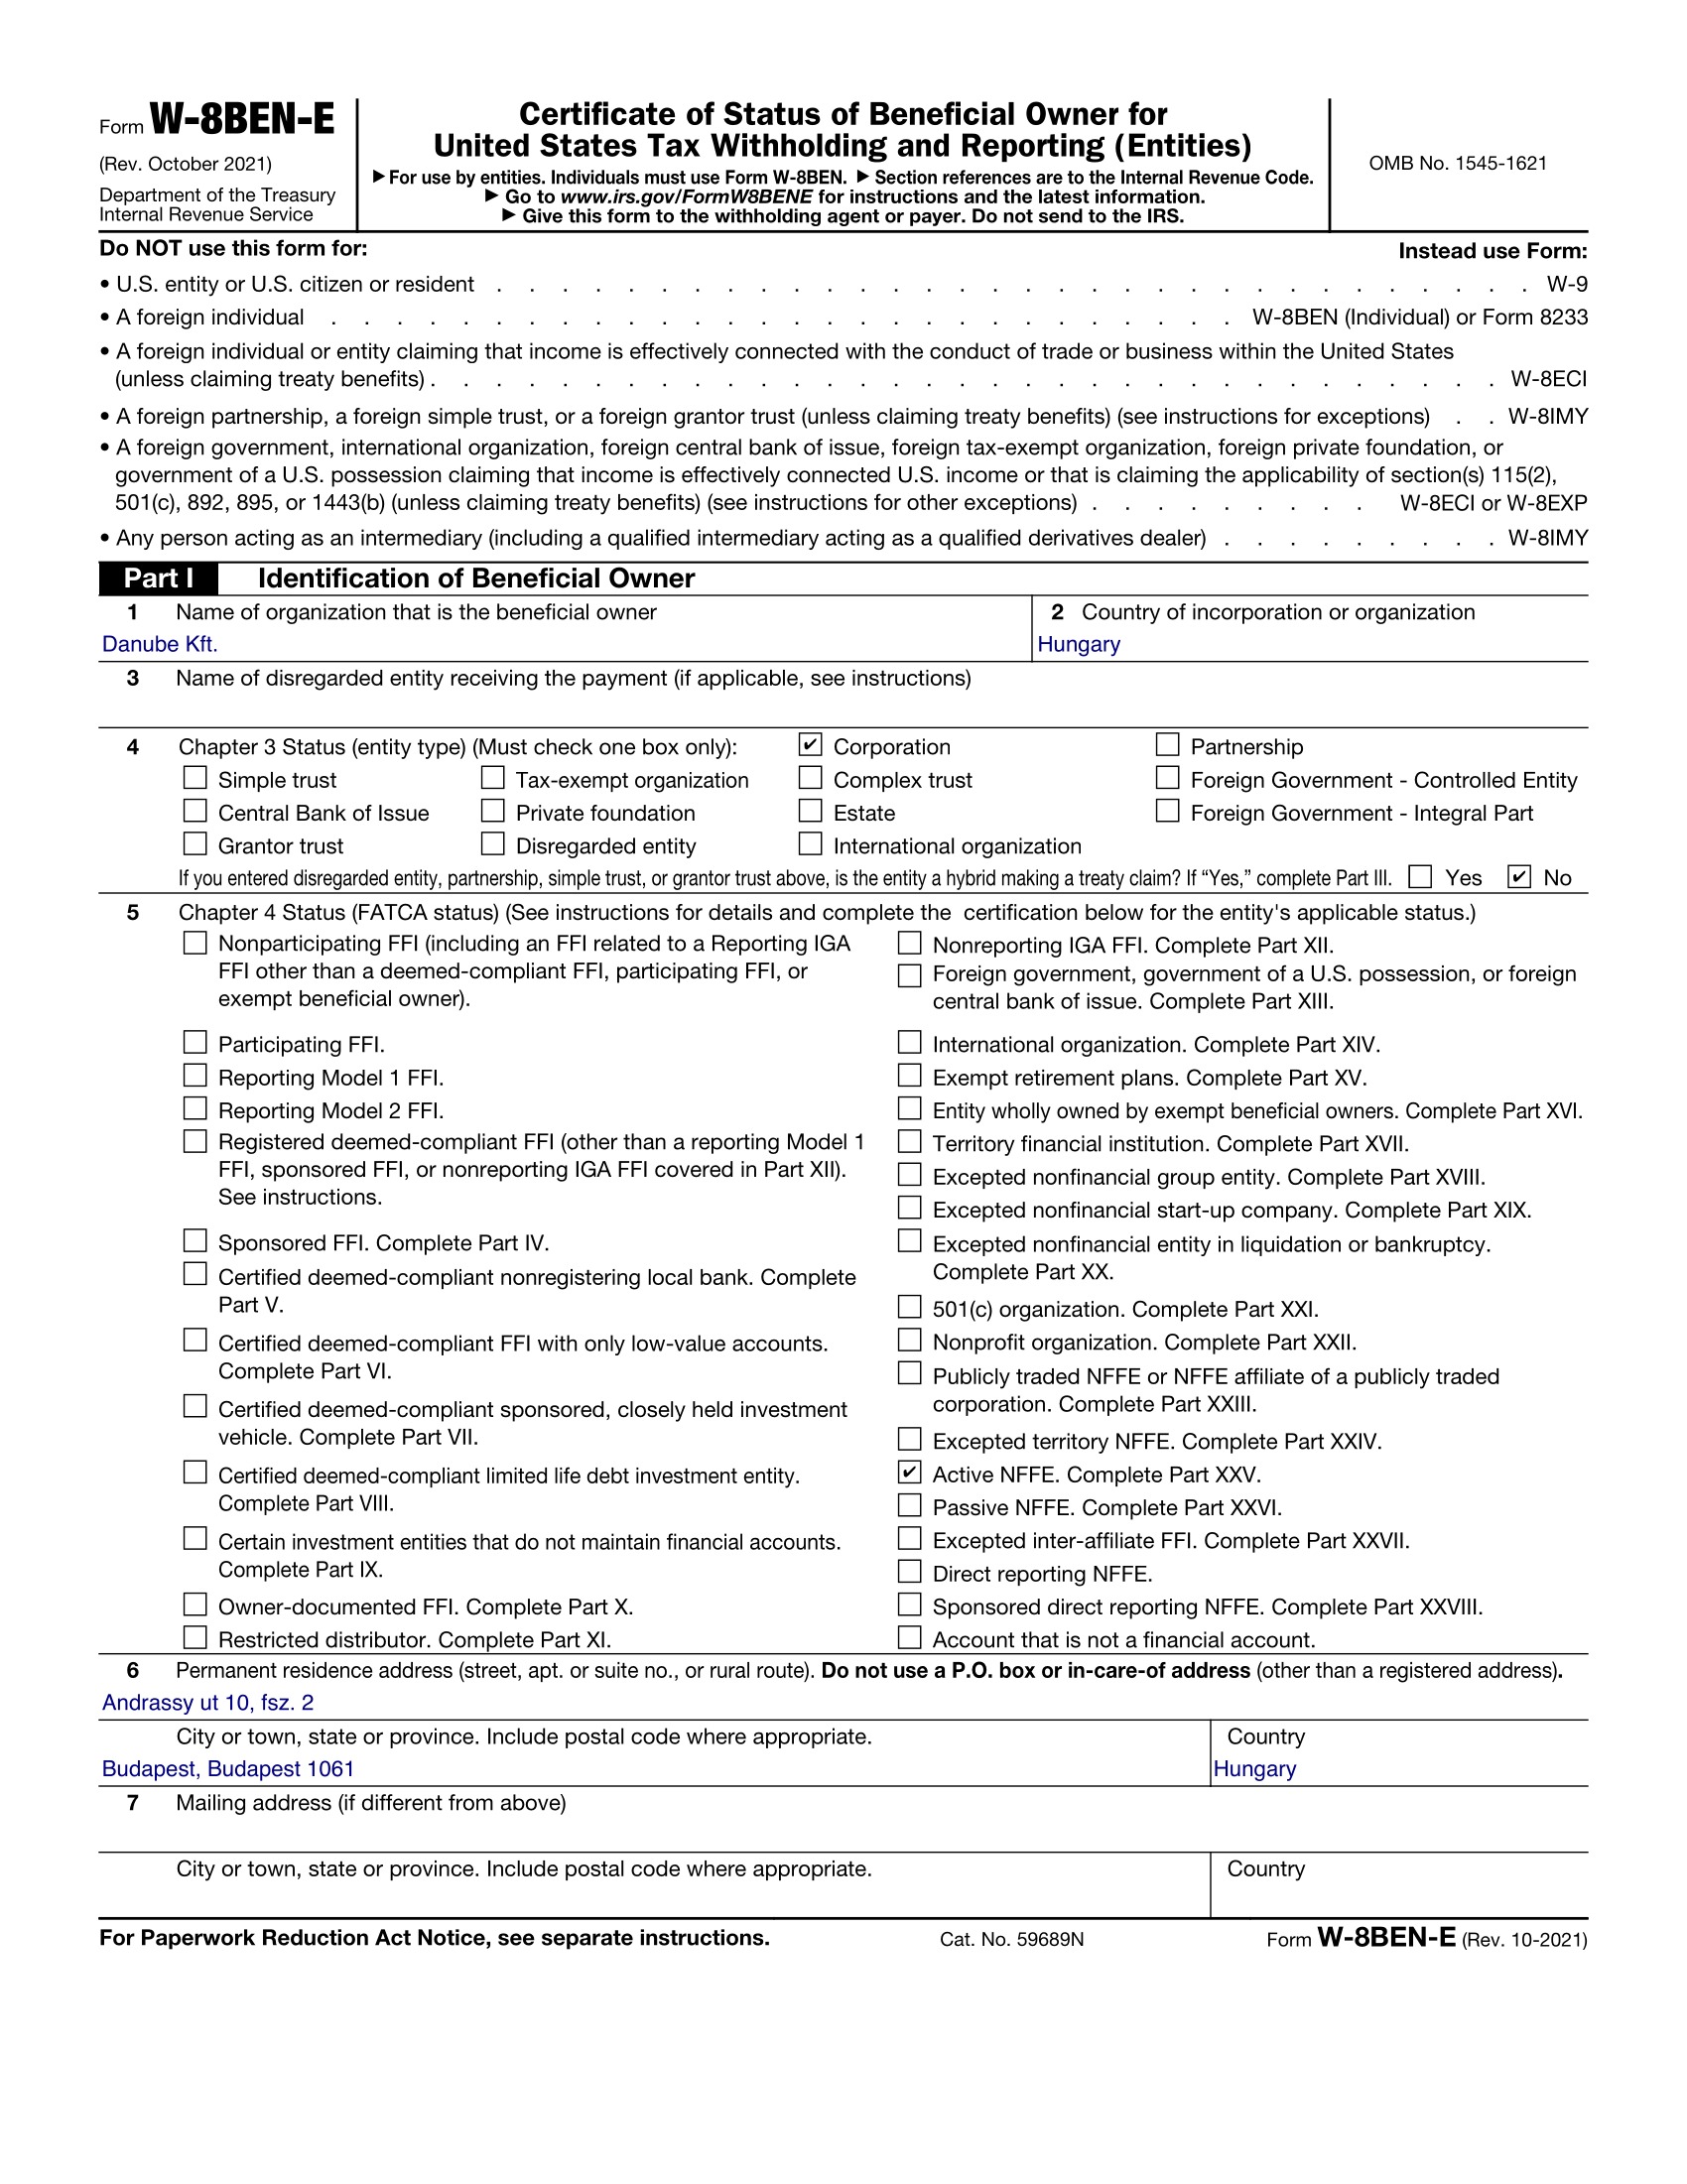
Sample only — uses a fictional company for illustration. Example: Danube Kft., Andrassy ut 10, fsz. 2, Budapest 1061, Hungary, adószám 12345676-2-42, Chapter 3 Corporation, FATCA Active NFFE, Part III blank (no US-Hungary tax treaty in force).
US withholding after 2024: what applies to a Hungarian Kft.
There is no reduced-rate table by article anymore. What matters is whether the income is US-source:
| Income type | US withholding | Note |
|---|---|---|
| Services performed outside the US | 0% (not US-source income at all) | Unchanged by the end of the treaty. The form documents foreign status. |
| Dividends on US stock | 30% | The old 5% and 15% rates died with the 1979 convention. You cannot still claim 15%. |
| Interest on most US-issued instruments | 30% | Unless the separate portfolio interest exemption applies. Ask an accountant. Do not treat it as automatic. |
| Royalties on IP used in the US | 30% | The old 0% royalty rate is no longer available. |
For a Kft., Form W-8BEN-E does not restore a treaty rate. Its job is to show the payer that the company is foreign, so services performed in Hungary are not withheld by mistake, and so US-source payments are withheld at 30% rather than under a harsher backup rule that applies when no form is on file.
Checklist vs. a ready-made PDF
Most older Hungarian write-ups still walk an investor through the 1979 dividend rates. That path is wrong for a form signed in 2026. The wizard asks the current questions and hands you the PDF.
| Criterion | Published guides | Our wizard |
|---|---|---|
| What you get | Often a 1979 rate table that no longer applies | The completed, signature-ready PDF, with Part III left blank by default |
| Kft. versus Zrt. versus egyéni vállalkozó | Easy to file the company form for a sole trader, or to treat a Zrt. like a Kft. | Hungary-specific Chapter 3 hints: Zrt. and Nyrt. are per se; a Kft. can use Form 8832; a sole trader is sent to W-8BEN |
| Part III left blank (treaty ended in 2024) | Risk of typing 5%, 15%, or 0% from the old convention | Knows there is no US-Hungary treaty in force and, by default, leaves Part III blank |
| Adószám versus adóazonosító jel | Easy to put a personal 8-series number on the company form | Asks for the adószám on W-8BEN-E and the adóazonosító jel on W-8BEN |
Start the wizard now and get your finished PDF in minutes.
Frequently asked questions
Questions we see from Hungarian Kft. owners and from people who still have a 1979 rate sheet.
Can I still claim 15% on US dividends?
No, not since 2024. The 5% and 15% dividend rates belonged to the 1979 convention. That convention ceased to apply to withholding on January 1, 2024. US dividends paid to a Hungarian resident are now withheld at 30%.
Will my US client withhold 30% on my invoices?
Not for services performed outside the United States. A Kft. that does the work in Hungary is earning foreign-source income. Ending the treaty did not change that. The 30% rate is for genuine US-source income, such as US dividends, US-source interest, and royalties for IP used in the United States.
Is a Zrt. treated like a Kft.?
No. A Zrt. is a részvénytársaság, and 26 CFR 301.7701-2(b)(8)(i) lists "Hungary, Reszvenytarsasag" as a per se corporation. A private Zrt. and a public Nyrt. are both per se. A Kft. is not on that list. It defaults to Corporation and can elect another classification on Form 8832.
Is a new treaty coming?
None is in force as of 2026. Hungary is not on the IRS list of income tax treaties. If a replacement convention enters into force, the product will be updated. Until then, Part III stays blank.
Does Hungary have any tax treaty with the United States?
Not a comprehensive income tax treaty that is currently in force. The 1979 convention was terminated. That is why Part III of Form W-8BEN-E (Lines 14–15) stays blank. Part II (Lines 11–13) is a different section — disregarded entity or branch — and also stays blank for an ordinary Kft.
Which number goes on Line 9b?
The company's adószám, for example 12345676-2-42. An individual's adóazonosító jel starts with 8 and has 10 digits, for example 8123456786. That personal number goes on Form W-8BEN.
Can I use a company in another country to get the old rates back?
Do not assume that works. Limitation on Benefits articles in other US treaties are designed to deny benefits when a Hungarian resident routes income through a third-country company only to claim a treaty rate. Ask a tax advisor before any restructuring. Do not invent an article on this form.
What is Chapter 4 / Active NFFE?
It is a FATCA classification, separate from the end of the tax treaty. An ordinary trading Kft. with mostly active business income is usually Active NFFE. That certification is Part XXV, not Part III.
How long is the form valid?
Generally until the end of the third calendar year after signing — a form signed in 2026 is valid through 31 December 2029, unless the facts change sooner.
Do I send this form to the Hungarian tax authority or to the IRS?
Neither, in the ordinary case. You give it to the US withholding agent — the client, platform, or broker that pays you. The payer keeps it as documentation.
Where to go next
For more detail on specific parts of the form:
- Fill out your W-8BEN-E in the guided wizard: Start the W-8BEN-E wizard ($30)
- Are you an egyéni vállalkozó?: Use the W-8BEN vs W-8BEN-E guide or the W-8BEN wizard ($5)
- General W-8BEN-E line-by-line guide: Form W-8BEN-E complete guide
- How withholding works without a valid W-8: US withholding tax guide
Common mistakes to avoid
- Filling Part III with the 1979 rates: 5% or 15% on dividends, or 0% on interest and royalties, describes a convention that ceased to apply to withholding on January 1, 2024. Lines 14a, 14b, and 15 stay blank.
- Putting an adóazonosító jel on the company form: Line 9b of Form W-8BEN-E takes the adószám (12345676-2-42). The 10-digit number that starts with 8 (8123456786) is for a person on Form W-8BEN.
- Assuming that, without a treaty, 30% is withheld from every payment: Services performed in Hungary are still foreign-source. The 30% rate is for US-source income.
- Treating a Zrt. like a Kft.: A Zrt. is per se Corporation. A Kft. is the eligible entity that can file Form 8832.
- Sending an egyéni vállalkozó down the company form: A sole trader files Form W-8BEN.
A note on Hungary's own tax system
Hungary taxes company profits locally (the headline corporate rate has been 9% for years) and taxes individuals under its own rules. None of that changes Form W-8BEN-E. The US form only concerns US withholding on US-connected payments.
If the company receives significant US-source dividends or royalties, ask a Hungarian accountant how that income meets the local return. This page stays on the US certificate.
- Local corporate tax: separate from US withholding, and not a reason to complete Part III.
- Adószám versus adóazonosító jel: two different identifiers. Only the adószám goes on the company form.
- None of the above: restores the 1979 treaty rates.
Ready to get your Hungarian Kft.'s W-8BEN-E right after the treaty ended?
The guided wizard asks the same questions covered on this page — and already knows the US-Hungary treaty ended in 2024, so by default it leaves Part III blank, without filling in an article.