W-8BEN-E for a Polish company selling on Amazon.com
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
A sp. z o.o. selling on Amazon.com answers the US tax interview as a foreign corporation. Poland’s trap is the article number: business profits are Article 8, and there is no LOB clause.
Three Polish entries people mix up
- Line 4: Corporation for a sp. z o.o. A spółka akcyjna is Corporation because it is per se.
- Line 9b: the 10-digit NIP. REGON and KRS are not tax numbers.
- Line 15 stays empty for product sales shipped from outside the United States. That sale is not FDAP, so 0% business profits is not the claim. Article 7 in this treaty is real property. Article 8(1) is business profits. 0% under Article 8(1) is only for profit not attributable to a permanent establishment in the United States.
The interview is the filing
The Tax Information Interview drafts and e-signs the W-8. Upload or mail a signed PDF only if Amazon asks. A valid W-8 keeps the spółka off 1099-K; without it Amazon suspends selling privileges until the interview is done. Product sales carry no US withholding either way. It stays through 31 December of the third year, then Amazon asks again. Status: Provided and Pending Validation. Our PDF lists fields. See the Amazon W-8BEN-E page.
Lines for a spółka z o.o.
The KRS excerpt gives the name. The article numbers below follow the 1974 treaty, which is the one in force — the 2013 treaty is not.
| Line | Polish entry |
|---|---|
| Line 1 | The firma from KRS, Latin letters, including “sp. z o.o.” or “spółka akcyjna”. |
| Line 4 | Corporation for a sp. z o.o. Shareholders are not personally liable. A spółka akcyjna (S.A.) is always Corporation: Poland, Spółka Akcyjna, is per se under Treas. Reg. §301.7701-2(b)(8). |
| Line 5 | Active NFFE when the company trades and passive income stays under half. A holding that only owns shares is Passive NFFE. |
| Line 9b | NIP, ten digits, issued to the company. Not REGON, not the KRS number, not a board member’s PESEL. |
| Line 14a | Poland, if the company is resident in Poland and claims the treaty. |
| Line 14b | The treaty does not contain a limitation on benefits provision. Tick the “no limitation on benefits” statement. Do not invent an article number. In Polish filing notes this is brak klauzuli LOB. |
| Line 15 | Leave it empty for product sales shipped from outside the United States. Do not write Article 8(1) at 0%, and do not write Article 7 — in the Polish treaty Article 7 is income from real property. 0% under Article 8(1) is only for profit not attributable to a US permanent establishment. |
sp. z o.o., S.A. and partnerships
Limited liability points at Corporation. A Polish partnership does not use this certificate.
- sp. z o.o.. Corporation. That is the usual Amazon seller. The legal name keeps the “sp. z o.o.” ending.
- spółka akcyjna (S.A.). Always Corporation. It is on the per se list for Poland.
- sp. j., sp. k., spółka partnerska. Partnerships. The IRS instructions for Form W-8BEN-E say a foreign partnership files Form W-8IMY, not W-8BEN-E.
A jednoosobowa działalność gospodarcza is a person. The form is W-8BEN. Selling as a sole trader? Use W-8BEN
NIP, REGON, KRS, PESEL
REGON
A statistical number, nine or fourteen digits. It is not the foreign TIN.
KRS
The court-register file number. Useful to prove the company exists. It does not go on line 9b.
PESEL
Eleven digits for a natural person. The board member’s PESEL is not the company’s NIP.
Article 7
On this treaty Article 7 is real property. Business profits are Article 8. Copying “Article 7” from a German or French page is the mistake.
Fulfilment stock and Article 6(3)
Poland’s permanent-establishment exceptions are in Article 6, not Article 5. Article 6(3)(a) and (b) say that using facilities only to store, display or deliver goods, and maintaining a stock only for storage, display or delivery, do not of themselves create a permanent establishment.
A Gdańsk jewellery studio can place amber pieces in Amazon’s US centres on that wording. The exception ends if the company runs its own American warehouse, posts employees, or gives someone authority to conclude contracts in the United States. Those facts can be a permanent establishment. Article 8 then allows US tax on the profits attributable to it.
The 2013 Poland–US treaty is not in force. Do not cite its article numbers. When Amazon asks for line 15 on product sales, leave it empty. A warehouse used only for storage, display, or delivery is not a permanent establishment. 0% under Article 8(1) is only for profit not attributable to a permanent establishment in the United States. Profit the United States may tax through that establishment is not 0%.
CIT in Poland
Amazon.com profit of a Polish resident company is in the CIT return. The standard rate is 19%. A small taxpayer that meets the statutory conditions may use 9% on the qualifying base — the thresholds are on podatki.gov.pl, and they change, so read the current page before you assume 9%.
A W-8 does not remove that Polish tax. Selling fees from a US Amazon company are imported services. The place of supply follows article 28b of the VAT act, and the company self-charges VAT under article 17(1)(4) (import usług). The CIT return is filed with the Polish tax office and includes the Amazon.com margin whether or not US withholding was zero.
Bursztyn Studio sp. z o.o., Gdańsk
Bursztyn Studio sp. z o.o. sets amber in silver. It launched on Amazon.pl, merchant fulfilled, then turned on FBA for Amazon.com and sent trays to US fulfilment centres. The workshop and every employee stay in Gdańsk. No agent concludes contracts in the United States.
Tomasz Wójcik, prezes, selected Corporation, entered NIP 5832147696, marked that the treaty has no limitation on benefits, and left the claim line empty, because the product sales are not US-source FDAP. He did not write Article 7, and he did not write Article 8(1) at 0%. Amazon stores the interview. The PDF here repeats the answers for the case when Amazon asks for a signed document.
Article 6(3)(a) and (b) are why the US trays are not a permanent establishment: they are stored and delivered, nothing more. Profit is declared in Poland. At the standard rate that is 19% CIT; 9% is only if the company is a small taxpayer under the current rules. The studio, the address and the NIP in the sample are fictional.
Sample: Bursztyn Studio sp. z o.o.
Line 9b is a fictional NIP. Line 14b says the treaty has no LOB article. Line 15 stays empty for the product sales.
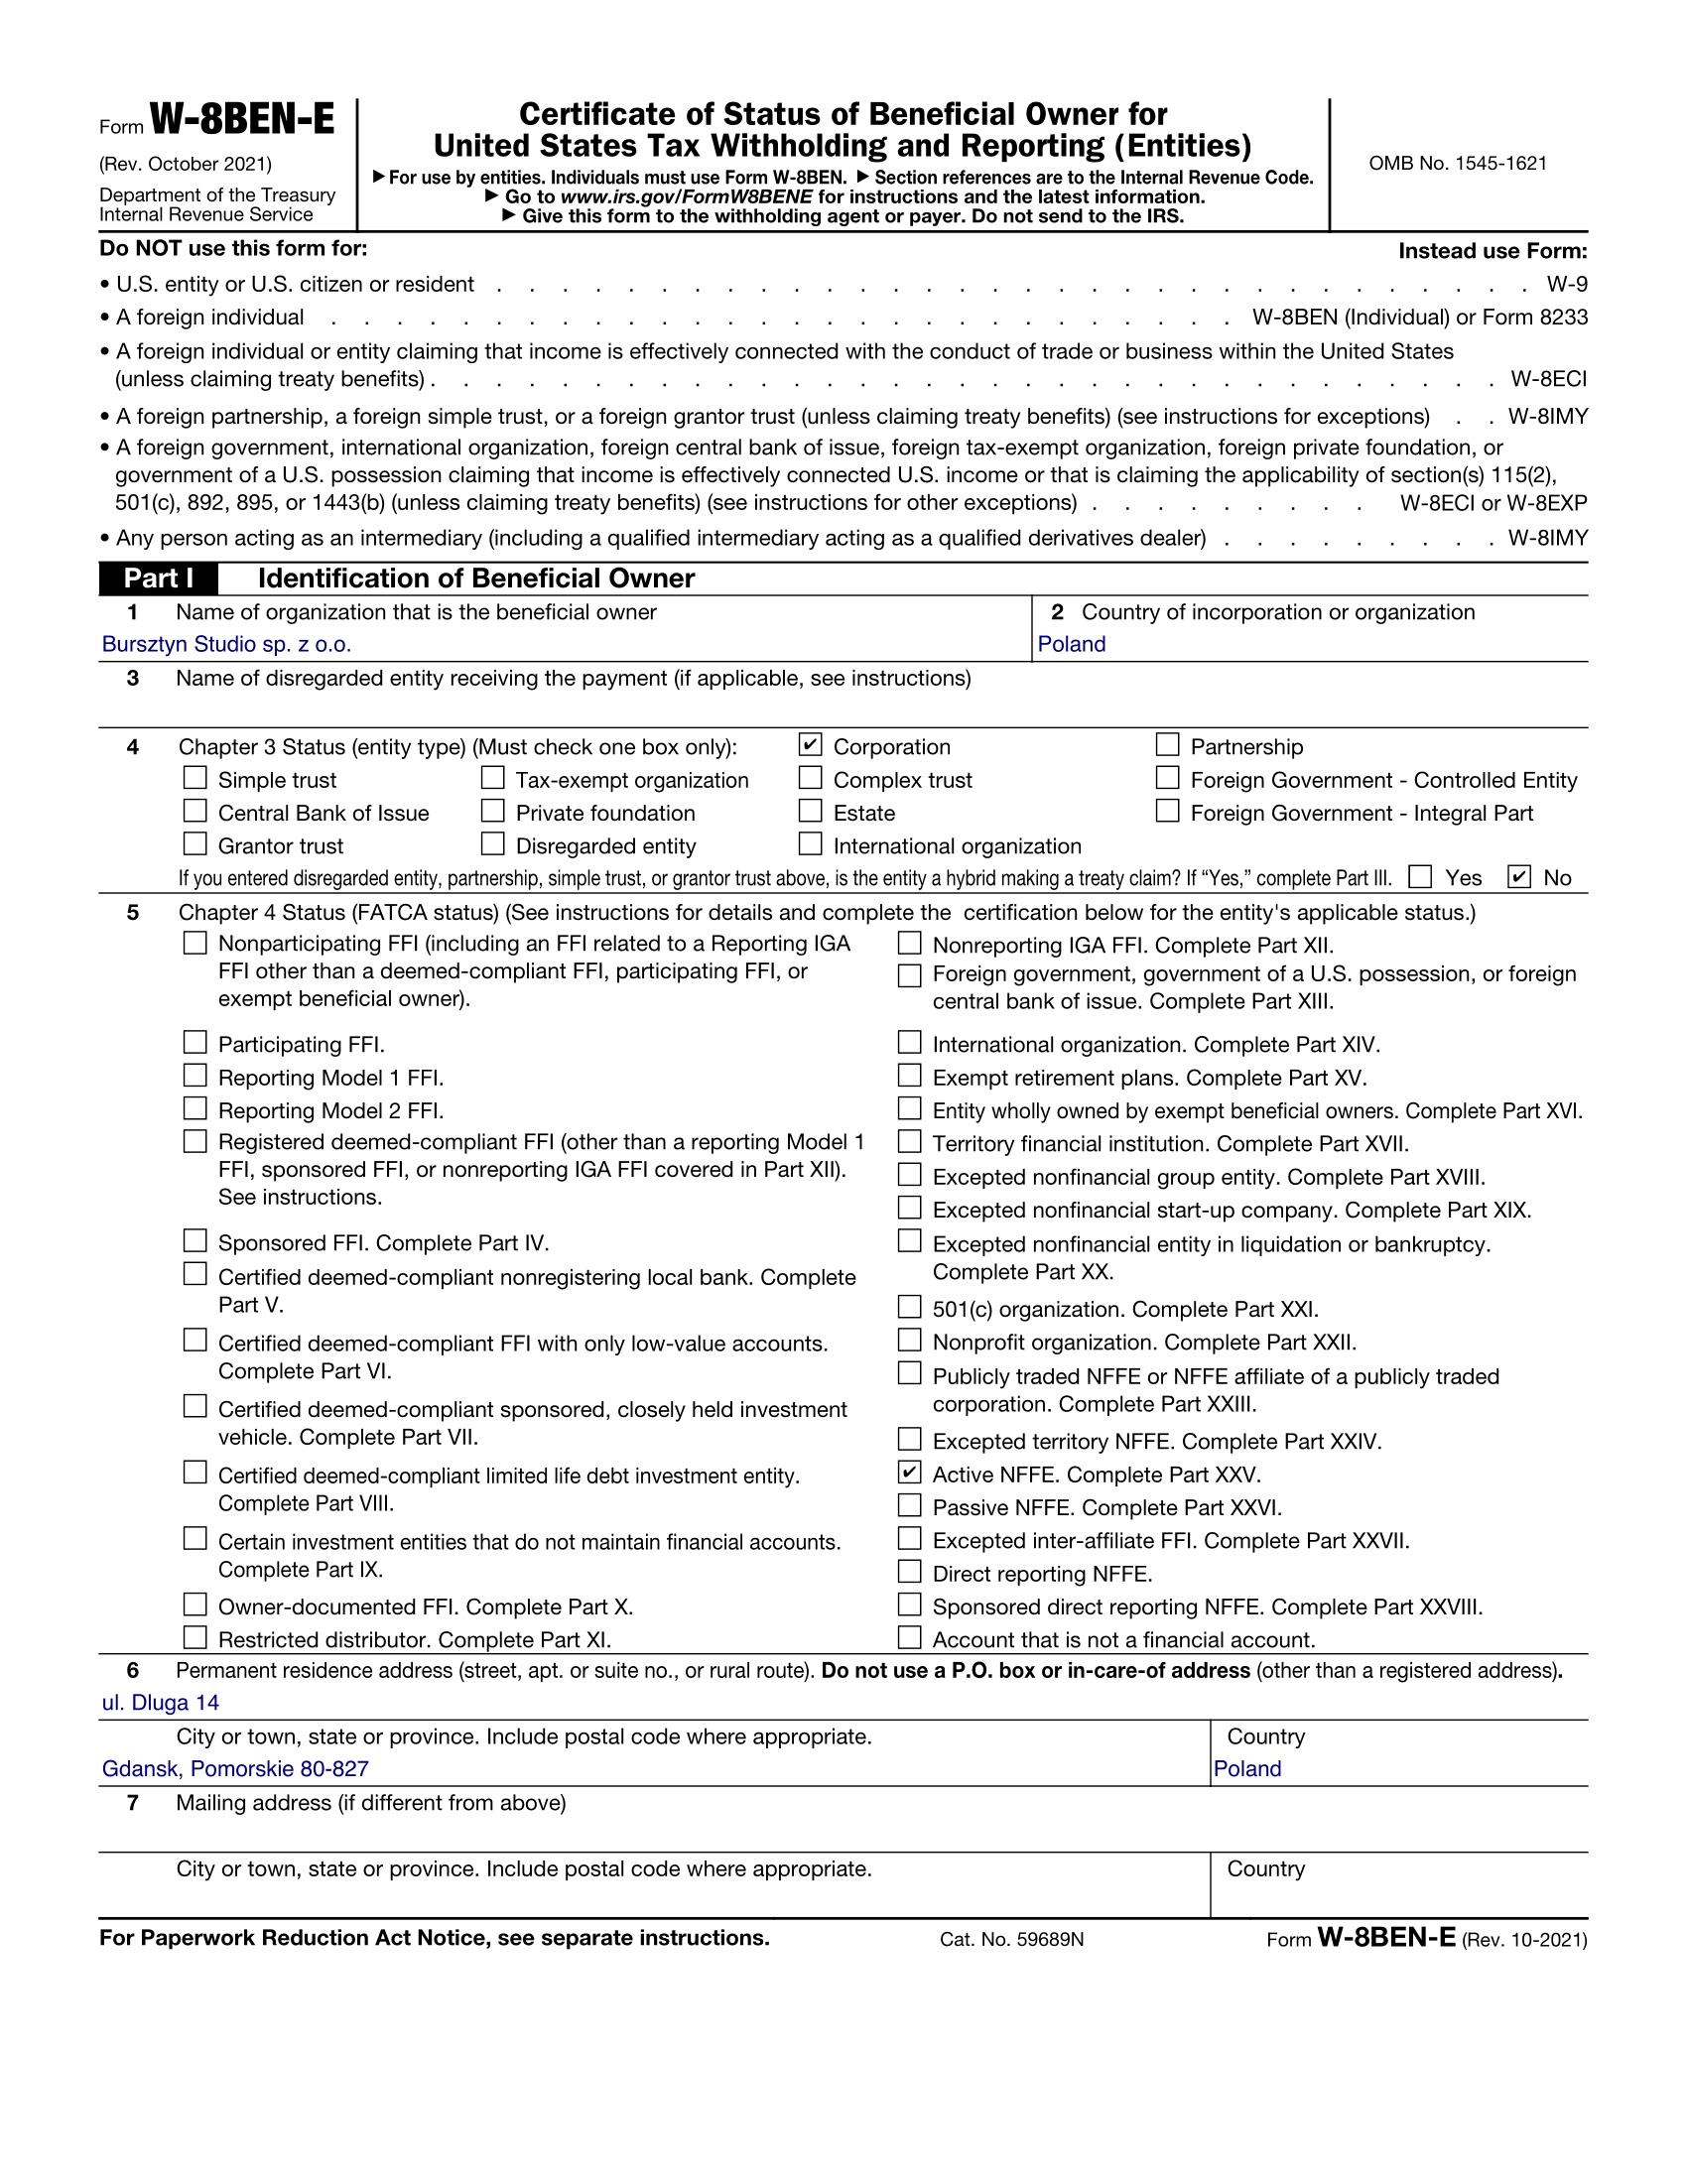
Example only. Bursztyn Studio sp. z o.o., Gdańsk, is fictional.
Article 8, NIP, no LOB article
Build the Polish W-8BEN-EFor an organization
For companies, funds, partnerships registered outside the USA.
Free to start. Payment is only required at the final step to download your completed PDF.
Loading...
Questions Polish companies ask
Why is line 15 Article 8 and not Article 7?
In the Poland–US treaty that is in force, business profits are Article 8. Article 7 of that treaty covers income from real property. A goods seller with no US permanent establishment leaves line 15 empty and does not claim Article 8(1) at 0%. 0% under Article 8(1) is only for profit not attributable to a US permanent establishment. The 2013 treaty, which renumbers some of this, is not in force.
What do we tick for limitation on benefits?
The statement that the treaty does not contain a limitation on benefits provision. There is no article to cite. Polish notes call this brak klauzuli LOB. Do not borrow Article 28 from the German treaty or Article 23 from the UK treaty.
Does FBA mean the company needs an EIN?
No. Line 8 stays blank without a US office, employees or a dependent agent. Line 9b is the NIP. Cartons in an Amazon building are not a reason to apply for a US employer identification number.
We already sell on Amazon.pl. Is the US interview separate?
Yes. The Polish storefront does not finish US income reporting. Amazon.com sales still go through the Tax Information Interview, which builds the W-8 and signs it electronically.
We are a spółka komandytowa. Same form?
No. A spółka komandytowa is a partnership for this purpose. The IRS instructions for Form W-8BEN-E say a foreign partnership uses Form W-8IMY. The partners file their own certificates.
Sources
Last checked: 7 October 2026