W-8BEN-E for a Danish ApS or A/S: ordinary interest and royalties at 0%, and a sample PDF
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Treaty articles and rates on this page are checked against the US-Denmark Income Tax Convention signed at Washington on August 19, 1999, together with the Protocol signed at Copenhagen on May 2, 2006 — last verified October 2026. The 2006 Protocol omitted Article 10 (Dividends) and Article 22 (Limitation of Benefits) and substituted new text, and it changed "a resident or a national" to "a resident and a national" in Article 19(2)(b). Articles 7, 11, 12, 14, 18, 20, and 21 were not changed. The 1948 convention is not in force.
 AI-generated image
A Danish ApS invoices a US client, and accounts payable asks for a W-8BEN-E before they pay. Work the ApS does in Denmark is not US-source income: there is no US withholding on it, and Part III (Lines 14a, 14b, and 15) stays blank. Article 7(1) at 0% is for services the company performs in the United States with no US permanent establishment. A software license and a film royalty both cite Article 12(1) at 0%: Article 12(2) only defines royalties, and unlike the Austria treaty there is no separate film rate. When the company claims the treaty, Line 14b certifies a Limitation of Benefits test of the 2006 Protocol's Article 22. For an operating ApS that is usually Active trade or business, Article 22(4)(a). The 1999 Article 22 was omitted. "No LOB article in treaty" is the wrong box.
This guide uses the current IRS line numbers (Rev. October 2021). Its sample is the claim case: Baltic ApS, Active NFFE, whose consultants perform services on site in the United States, at a US client's office, with no US permanent establishment, claiming Article 7(1) at 0%. It also covers the protocol dividend split (5% / 15%, and 0% only in the cases of Article 10(3)), ordinary interest at 0% under Article 11(1), why contingent interest is not that 0% rate, and US pensions.
If you are not incorporated — an Enkeltmandsvirksomhed working under your own CPR number — you file Form W-8BEN, not this form: start the W-8BEN wizard. Services you perform in Denmark are not US-source income, so Part II of Form W-8BEN (Lines 9 and 10) stays blank. A treaty exemption for personal services you perform in the United States (Article 14(1), independent personal services) is claimed on Form 8233, not on Form W-8BEN. This page is for incorporated businesses.
Or skip the reading and start the W-8BEN-E wizard — guided questions, a suggested treaty article and rate, and a signature-ready PDF for $30.
Blank form or already filled in?
You can download the official blank form from the IRS and complete it yourself, or get the same file filled from your answers. Read the 1999 convention and the 2006 protocol together. The protocol is the operative text for dividends and Limitation of Benefits.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for an ApS or an A/S.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for an Enkeltmandsvirksomhed.
- 1999 Convention: Income Tax Treaty PDF on IRS.gov — Articles 7, 11, 12, 14, 18, 20, and 21. Do not use the 1999 Article 10 or Article 22.
- 2006 Protocol: Protocol PDF on IRS.gov — this replaced Article 10 and Article 22 in full and amended Article 19(2)(b).
- IRS treaty documents page: Denmark tax treaty documents. The 1948 convention is not the treaty in force.
- Already filled in (5–10 minutes): W-8BEN-E for Danish companies ($30) or W-8BEN for an individual ($5) — treaty article and rate suggested automatically, ready to sign as a PDF.
Which Danish company type are you actually dealing with?
The Chapter 3 box depends on the legal form, not on revenue:
- Aktieselskab (A/S) Always a Corporation for US tax purposes. 26 CFR 301.7701-2(b)(8)(i) lists "Denmark, Aktieselskab" as a per se corporation. There is no Form 8832 election.
- Anpartsselskab (ApS) The usual startup and small-company form, and the example name in the wizard is Baltic ApS. It is not on the per se list. Members have limited liability, so it defaults to Corporation, but it can elect a different US classification on Form 8832. A single-member ApS is not disregarded by default.
- Enkeltmandsvirksomhed An individual registration, not a separate legal entity. The person files Form W-8BEN, not this form. Services performed in Denmark leave Part II (Lines 9 and 10) blank. Personal services performed in the United States are claimed under Article 14(1) on Form 8233, never under Article 7.
- I/S and K/S An Interessentskab (I/S) or Kommanditselskab (K/S) is a partnership-style form, not a Corporation by default. Do not check Corporation only because the business has more than one owner.
An ApS that has not filed Form 8832 checks Corporation on Line 4. An A/S checks Corporation too, and it cannot elect out.
Do not put a personal CPR number on the company form. A CPR is 10 digits (the wizard example for a person is 1234567890). The company identifier is the CVR, 8 digits. The sample company uses 12345678.
Who actually needs to fill in W-8BEN-E?
Any Danish ApS or A/S that receives payments from a US business and wants to document non-US status. Common situations:
- Consulting or software invoices A US client asks for the form before paying service fees, even for work done in Denmark that needs no treaty claim and leaves Part III (Lines 14a, 14b and 15) blank.
- Royalties or a software license The payer needs a treaty claim before applying 0% instead of 30%.
- A broker or platform Danish investors meet Form W-8BEN at Saxo, Nordnet, Danske Bank, and similar brokers. Form W-8BEN-E is the company form, for an ApS or A/S billing US clients, not for a personal brokerage account.
What happens without a valid form?
Without a W-8BEN-E, a US payer withholds 30% of the gross amount of US-source FDAP income (dividends, interest, royalties, and pay for services performed in the United States), even when the treaty would reduce that rate. Services the ApS performs in Denmark are not US-source income, so there is no chapter 3 withholding on them, though some platforms hold the payment until a valid form is on file. With the form, services performed in the United States with no US permanent establishment are 0% under Article 7(1), ordinary interest is 0% under Article 11(1), a software license and a film royalty are 0% under Article 12(1), and ordinary dividends are 15% under Protocol Article 10(2)(b) unless a reduced-rate test is met.
The form stays with the US payer. It is not filed with SKAT or the IRS. Danish tax on the same income is a separate question.
W-8BEN-E line by line: what a Danish ApS actually enters
Official IRS line numbers for an operating ApS, Active NFFE. Services done in Denmark leave Part III (Lines 14a, 14b, and 15) blank. The sample shows the claim case: staff performing services on site in the United States, at a US client's office, with no US permanent establishment, claiming Article 7(1) at 0%. An A/S uses the same lines except that it cannot elect out of Corporation. An Enkeltmandsvirksomhed does not use this form.
| Line | What you enter |
|---|---|
| Line 1 | The company's legal name, for example Baltic ApS. |
| Line 2 | Country of incorporation: Denmark. |
| Line 3 | Leave blank unless a disregarded entity is receiving the payment for its owner. |
| Line 4 | Corporation for an A/S (always) or an ApS (the default, unless Form 8832 says otherwise). The hybrid follow-up is usually No. |
| Line 5 | Chapter 4 (FATCA) status. An operating company with no financial business is usually Active NFFE. |
| Line 6 | The registered office. The sample uses Ostergade 5, 2. th., Copenhagen, 1100. |
| Line 7 | Only if the mailing address differs from Line 6. |
| Line 8 | Usually blank. A US TIN is required only in the cases the payer names. |
| Line 9a | Leave blank. A GIIN is for financial institutions. |
| Line 9b | The company's CVR number, 8 digits, as the foreign TIN. Do not enter a personal CPR number, which is 10 digits. |
| Line 9c | Not checked for a registered company that has a CVR number. |
| Line 10 | Usually blank unless the payer asks for a reference number. |
| Part II (Lines 11–13) | Not completed for an ordinary ApS. Part II is for disregarded entities and branches. |
| Line 14a | Only when the company claims the treaty: country of residence for treaty purposes, Denmark. Services performed in Denmark leave Part III blank. |
| Line 14b | Only when the company claims the treaty: a Limitation of Benefits test of the 2006 Protocol's Article 22. An operating ApS usually certifies Active trade or business under Article 22(4)(a). When the income comes from a trade or business activity in the United States, Article 22(4)(b) also requires the Danish activity to be substantial in relation to that US activity. "No LOB article in treaty" is the wrong box. Article 22(2)(g) is a special test for a Danish taxable nonstock corporation, not the default for an ApS. |
| Line 14c | Not normally checked. |
| Line 15 | Only when the company claims the treaty. For services performed in the United States with no US permanent establishment: Article 7(1), 0%, Services. For a software license or a film royalty: Article 12(1), 0%, Royalties. Cite Article 12(1), not Article 12(2). Article 12(2) only defines royalties. Equipment rental in the company's trade or business, with no US permanent establishment and no activity in the United States, is Article 7(1), 0%, not Article 12. A lease outside any trade or business, with no activity in the United States, is other income, Article 21(1), 0%. With activity in the United States the claim stays blank. |
| Line 39 (Part XXV) | Check the Active NFFE certification if Line 5 is Active NFFE. |
| Part XXX | Signature, printed name, and date. The sample is signed by Mette Hansen. |
Line numbers match Rev. October 2021. If the IRS issues a new revision, follow the numbering on the PDF you sign.
The guided W-8BEN-E wizard fills these lines from your answers, including the article and rate on Line 15 when there is one to claim.
A/S, ApS, and an Enkeltmandsvirksomhed are not the same box
The per se list names only the Aktieselskab. An ApS is still a Corporation by default, and an Enkeltmandsvirksomhed is not a company at all.
| Point | What it means |
|---|---|
| Aktieselskab (A/S) | Per se corporation under 26 CFR 301.7701-2(b)(8)(i). Check Corporation. Form 8832 cannot change that. |
| Anpartsselskab (ApS) | Not on the per se list. Limited liability means the default is still Corporation. A different US classification requires a filed Form 8832. |
| Enkeltmandsvirksomhed | Individual registration. File Form W-8BEN. Services performed in Denmark need no claim, so Part II (Lines 9 and 10) stays blank; personal services performed in the United States go on Form 8233 under Article 14(1), never Article 7 and never Article 12. |
| CVR vs CPR | Line 9b on this form is the 8-digit CVR. The 10-digit CPR belongs on Form W-8BEN. |
Use the default that matches the company you actually registered, unless a Form 8832 election is already on file.
What a completed W-8BEN-E looks like for a Danish ApS
An anonymised example: Baltic ApS, Active NFFE, whose staff perform services on site in the United States with no US permanent establishment, claiming Article 7(1) at 0% and certifying Active trade or business on Line 14b. Services performed in Denmark would leave Part III blank. This is the PDF the wizard produces from the same inputs.
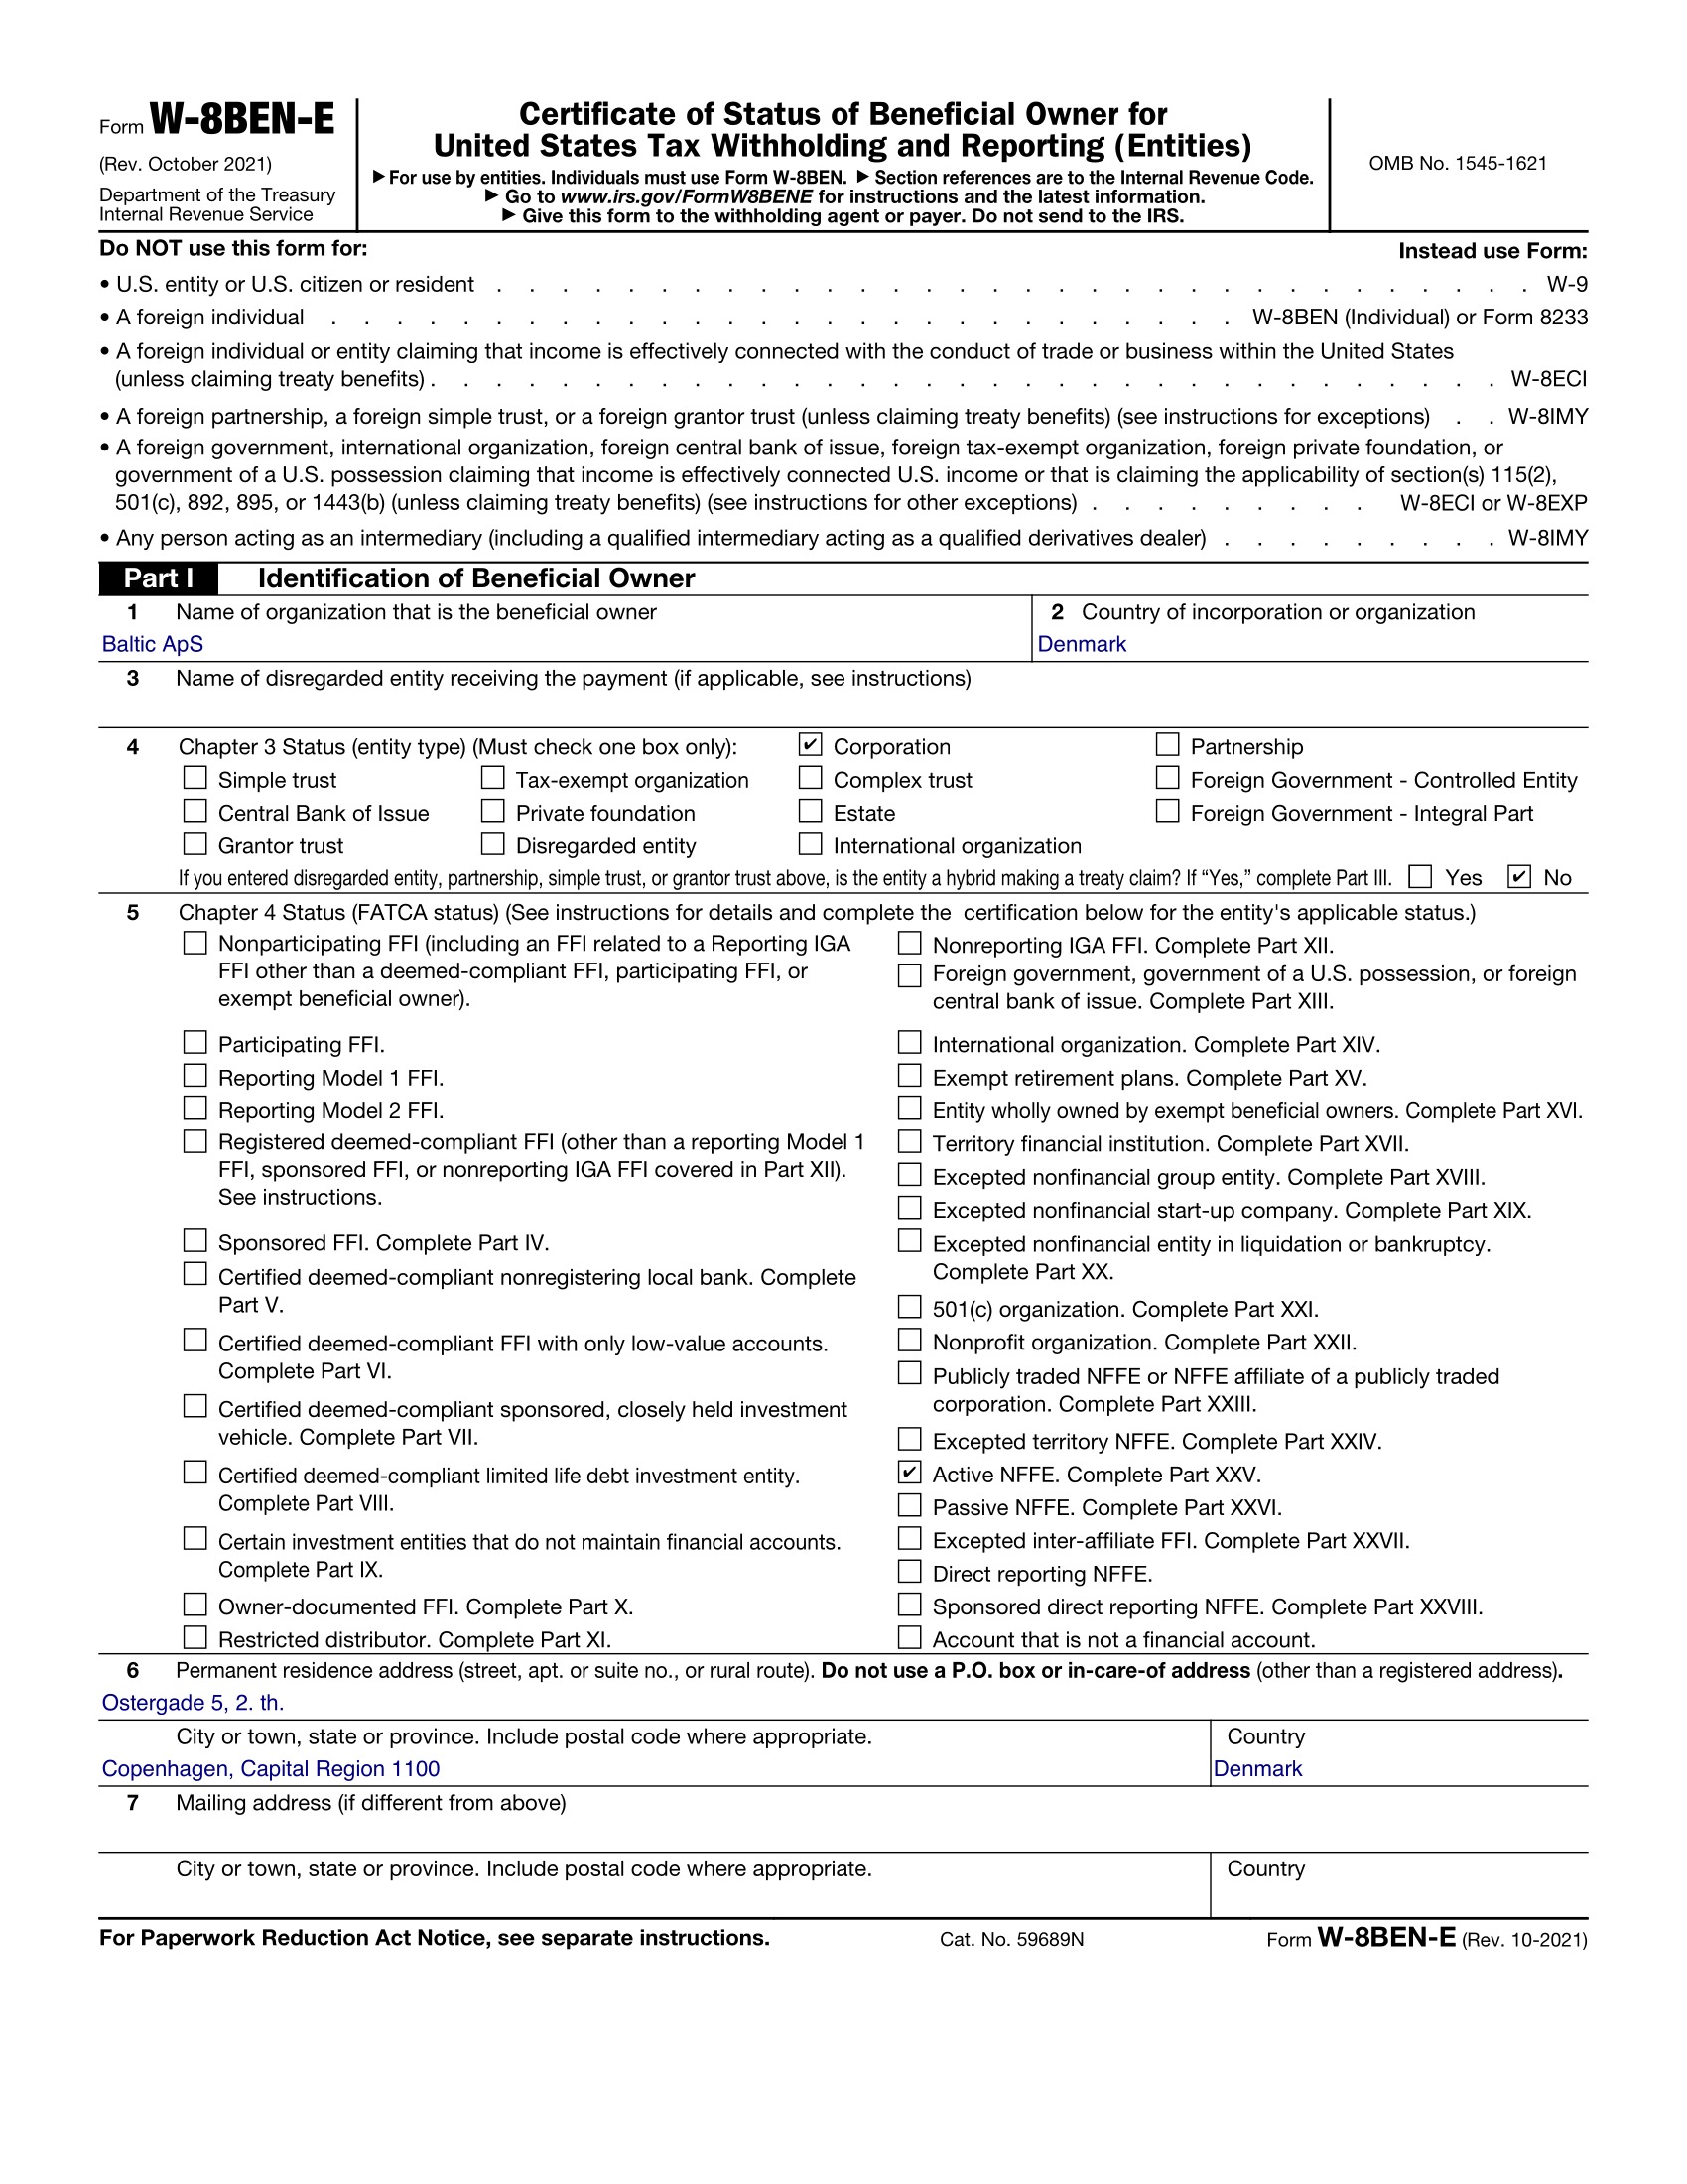
For illustration only. The company name, address, signer, and CVR number are fictional. Example: Baltic ApS, Copenhagen, CVR 12345678, Chapter 3 Corporation, FATCA Active NFFE, services performed in the United States with no US permanent establishment, US-Denmark treaty Article 7(1) (Business Profits) 0%, Limitation of Benefits Active trade or business.
Treaty rates by income type
These rates come from the 1999 Convention plus the 2006 Protocol. Dividends and Limitation of Benefits follow the protocol. Interest, royalties, business profits, independent personal services, and pensions follow the 1999 text.
| Income type | Article | Rate |
|---|---|---|
| Services performed in the United States (Business Profits, no US permanent establishment). Services performed in Denmark need no claim: Part III (Lines 14a, 14b and 15) stays blank | Article 7(1) | 0% |
| Equipment rental in a trade or business (tangible personal property; Article 7(7), not a royalty), no US permanent establishment and no activity in the United States. With activity in the United States the claim stays blank | Article 7(1) | 0% |
| Dividends, company holding directly at least 10% of the share capital | Article 10(2)(a) | 5% |
| Dividends, general rate (under 10% of the share capital, or any holder who does not meet 10(2)(a)) | Article 10(2)(b) | 15% |
| Dividends, company that has owned 80% or more of the voting power for 12 months and meets one of the Article 22 tests in 10(3)(a)(i)–(iv) | Article 10(3)(a) | 0% |
| Dividends, pension fund described in Article 22(2)(e), not derived from carrying on a business by the fund or through an associated enterprise | Article 10(3)(c) | 0% |
| Dividends from a US RIC: 10(2)(a) and 10(3)(a) do not apply | Article 10(2)(b) | 15% |
| Interest, ordinary cash loan (not contingent interest, not a REMIC excess inclusion) | Article 11(1) | 0% |
| Contingent interest (determined with reference to receipts, sales, income, profits or other cash flow of the debtor or a related person, to any change in the value of any property of the debtor or a related person, or to any dividend, partnership distribution or similar payment made by the debtor to a related person) | Article 11(5)(a) | 15% |
| Royalties, including software and cinematographic films (Article 12(2) is the definition) | Article 12(1) | 0% |
| Annuity paid to an individual, as Article 18(3) defines it: paid for adequate and full consideration other than services rendered | Article 18(3) | 0% |
| Other income not dealt with in another article, including equipment rental not derived in connection with a trade or business (a passive lease), with no activity in the United States. With activity in the United States the claim for that rent stays blank | Article 21(1) | 0% |
On Line 15, cite Article 12(1) for a software license and for a film royalty. Article 12(2) defines royalties and includes computer software and cinematographic films. It is not a rate paragraph, and Denmark has no Austria-style film rate of up to 10%. Do not copy Austria Article 12(2) onto Denmark. Equipment rental is not inside that definition. Article 7(7) puts rental of tangible personal property from a trade or business in business profits, so equipment rent in a trade or business, with no US permanent establishment and no activity in the United States, cites Article 7(1) at 0%. The Treasury technical explanation of Article 7(7) sends rent not derived in connection with a trade or business to Article 21 (Other Income), so a passive lease with no activity in the United States cites Article 21(1) at 0%. Ordinary interest cites Article 11(1) at 0%. Article 11(2) is the definition. Article 11(5)(a) taxes contingent interest at the Article 10(2)(b) rate of 15%, and under Article 11(5)(b) each state may tax a REMIC excess inclusion under its own domestic law. Do not cite Article 11(5) for an ordinary cash loan, and do not describe interest as having no exceptions. The 5% dividend rate is Protocol Article 10(2)(a), and the test is 10% of the share capital, not voting stock. The general rate is 10(2)(b) at 15%. Protocol Article 10(3) is 0% only for a company that has owned 80% or more of the voting power for 12 months, directly or through residents of either state, and meets one of the Article 22 tests listed in 10(3)(a)(i)–(iv), for a qualified governmental entity that does not control the payer (10(3)(b)), or for a pension fund described in Article 22(2)(e) whose dividends are not derived from carrying on a business by the fund or through an associated enterprise (10(3)(c)). Do not default an ordinary ApS to 0%. The 1999 Article 10(3) was a RIC/REIT rule; that paragraph was omitted. RIC and REIT rules are now Protocol Article 10(4)(a): a REIT dividend keeps 10(2)(b) only for an individual or a pension fund holding not more than 10%, a holder of not more than 5% of a publicly traded class, or a holder of not more than 10% of a diversified REIT; otherwise there is no treaty rate. Do not cite the branch-tax paragraphs for a company with no US permanent establishment.
An Enkeltmandsvirksomhed: Part II (Lines 9 and 10) blank for work in Denmark, Article 14(1) on Form 8233 for work in the United States
Article 14(1) applies to an individual resident performing personal services of an independent character. That income is taxable only in the residence state unless the individual has a fixed base regularly available in the other state. If the fixed base exists, only the income attributable to it from services performed in that other state may be taxed there. Article 14(2) only says that amount is determined under Article 7(3). There is no day-count test in Article 14; the day-count test for employment wages is in Article 15(2)(a). Services an Enkeltmandsvirksomhed performs in Denmark are not US-source income: there is no US withholding and Part II of Form W-8BEN (Lines 9 and 10) stays blank. The IRS takes a treaty claim for personal services performed in the United States on Form 8233, not on Form W-8BEN. An ApS does not cite Article 14.
A blog post, or the finished PDF?
Generic European guides often copy one royalty rate onto every country, or they still use the 1999 dividend article. The wizard asks those questions once and returns the PDF.
| Point | This page | A generic guide |
|---|---|---|
| Article numbers | Article 7(1) for services performed in the United States and for equipment rent in a trade or business with no activity in the United States, Article 21(1) for a passive lease with no activity there, Article 12(1) for software and films, Article 14(1) for a freelancer's US work on Form 8233. | Often cites Article 12(2) as a film rate, the way the Austria treaty does. |
| Line 14b | Only with a treaty claim: Active trade or business under Protocol Article 22(4)(a). | Sometimes uses the omitted 1999 Article 22, or says there is no LOB article. |
| Finished form | Sample PDF for Baltic ApS, for services performed on site in the United States with no US permanent establishment (work done in Denmark leaves Part III, Lines 14a, 14b and 15, blank), plus a wizard that fills yours. | A checklist you still have to type into the IRS PDF. |
Start the wizard and download the filled PDF.
Frequently asked questions about W-8BEN-E for Danish companies
Direct answers for an ApS or A/S billing US clients or receiving US investment income.
Which article do I cite for consulting fees?
None, when the work is done in Denmark: that is not US-source income, so there is no US withholding and Part III stays blank. For services the ApS performs in the United States with no US permanent establishment, cite Article 7(1) at 0%. Do not cite Article 12 or Article 14 for the company.
I am an Enkeltmandsvirksomhed, not an ApS. Which form and which article?
Form W-8BEN. Services you perform in Denmark need no treaty claim, so Part II (Lines 9 and 10) stays blank. For personal services you perform in the United States, the treaty article is Article 14(1) (taxable in the United States only with a fixed base regularly available to you there), and the claim goes on Form 8233, not on Form W-8BEN. Do not cite Article 7 for those services. Equipment you rent out is different. Rent from a trade or business of your own is business profits under Article 7(7), so with no US permanent establishment and no activity in the United States, Line 10 of Form W-8BEN is Article 7(1) at 0%. A passive lease, outside any trade or business, is other income: with no activity in the United States, Line 10 is Article 21(1) at 0%.
Is a software license 0%, and what about a film?
Both cite Article 12(1) at 0%. Article 12(2) defines royalties and includes computer software and cinematographic films. It is not the rate paragraph. Denmark does not have Austria's separate film rate of up to 10%.
Is equipment rental a royalty?
No. Article 7(7) treats rental of tangible personal property as business profits when it is income from a trade or business, for a company and for an individual. For a lease in a trade or business, with no US permanent establishment and no activity in the United States, cite Article 7(1) at 0%, not Article 12: an ApS on Line 15 of Form W-8BEN-E, an Enkeltmandsvirksomhed on Line 10 of Form W-8BEN. The Treasury technical explanation of Article 7(7) says rent not derived in connection with a trade or business is dealt with in Article 21 (Other Income), so a passive lease with no activity in the United States cites Article 21(1) at 0%. A lessor with activity in the United States leaves the treaty claim for the rent blank.
Is interest really 0% with no exceptions?
Ordinary interest is Article 11(1) at 0%. That is not every interest payment. Article 11(5)(a) lets the United States tax contingent interest at 15%, the Article 10(2)(b) rate. Under Article 11(5)(b) each state may tax a REMIC excess inclusion under its own domestic law. Do not cite Article 11(5) for an ordinary cash loan.
What do I check on Line 14b?
Only when the company claims the treaty: usually Active trade or business, which is Article 22(4)(a) of the 2006 Protocol. The 1999 Article 22 was omitted. "No LOB article in treaty" does not apply to Denmark. Article 22(2)(f) is the ownership-and-base-erosion test, not the default for an operating ApS. A company at least 50% of whose vote and value is owned, directly or indirectly, by five or fewer companies that meet the listing test of Article 22(2)(c)(i) or (ii), each intermediate owner resident in Denmark or the United States, may meet Article 22(2)(c)(iii). One at least 95% owned by seven or fewer equivalent beneficiaries, with less than 50% of its gross income paid in deductible payments to persons who are not equivalent beneficiaries, may meet the derivative benefits test of Article 22(3).
Why is the dividend rate 15%, not 0%?
Protocol Article 10(2)(b) is 15% for a holder who does not meet the 10% share-capital test. 10(2)(a) is 5% when a company holds directly at least 10% of the share capital. 10(3)(a) is 0% only when a company has owned 80% or more of the voting power for 12 months and meets one of the Article 22 tests named in that paragraph; 10(3)(c) is 0% for a pension fund described in Article 22(2)(e) whose dividends are not derived from carrying on a business by the fund or through an associated enterprise. The 1999 Article 10(3) was a RIC/REIT rule and is no longer the text.
Is a US pension paid to a resident of Denmark 0%?
Article 18(1)(a) makes a pension distribution, periodic or a single sum, taxable only in the state where it arises, and Article 18(1)(c) says it arises only where the paying pension scheme is established. A pension from a US scheme paid to a resident of Denmark is therefore taxable only in the United States: the treaty gives no reduced rate, so leave the treaty claim blank. The exception is Article 18(1)(b): a person who was already a resident of Denmark and receiving those pensions before the convention entered into force is taxed only in Denmark. US social security is taxable only in the United States under Article 18(2). An annuity is taxable only in the residence state under Article 18(3), which defines it as a stated sum paid periodically at stated times during a specified number of years or for life, in return for adequate and full consideration (other than services rendered): a payment for past services is a pension, even if the plan calls it an annuity. A US government-service pension is taxable only in the United States under Article 19(2)(a), unless the person is a resident and a national of Denmark (Article 19(2)(b), as amended by the 2006 Protocol).
A/S or ApS on Line 4?
Both check Corporation unless the ApS has filed Form 8832. Only "Denmark, Aktieselskab" is on the per se list. The ApS is a Corporation by default because of limited liability.
CPR or CVR on Line 9b?
The company's CVR, 8 digits. The sample uses 12345678. A CPR is the 10-digit personal number and belongs on Form W-8BEN, not on the company form.
Related guides
More on the form itself:
- Company form: W-8BEN-E wizard for an ApS or A/S
- Not a company: W-8BEN wizard for an individual ($5)
- Chapter 3 status: Chapter 3 status guide
Common mistakes to avoid
- Putting a CPR on the company form Line 9b is the 8-digit CVR. A CPR is 10 digits and belongs on Form W-8BEN.
- Claiming Article 7(1) for work done in Denmark Services performed in Denmark are not US-source income. Part III stays blank; Article 7(1) is for services performed in the United States.
- Citing Article 12(2) as the royalty rate The rate is Article 12(1) at 0%, including films and software. Paragraph 12(2) only defines royalties.
- Copying Austria's film rate Austria Article 12(2) can tax films at up to 10%. Denmark has no matching film paragraph.
- Calling every interest payment 0% Ordinary interest is Article 11(1) at 0%. Contingent interest is Article 11(5)(a) at 15%.
- Using the 1999 dividend article The 2006 Protocol replaced Article 10. The old Article 10(3) was a RIC/REIT rule, not the 0% parent-subsidiary rate.
- Checking No LOB article Protocol Article 22 is a real Limitation of Benefits article. An operating ApS that claims the treaty certifies Active trade or business under 22(4)(a).
- Claiming Article 14(1) on Form W-8BEN An individual's services performed in Denmark need no claim: Part II (Lines 9 and 10) stays blank. Personal services performed in the United States are claimed under Article 14(1) on Form 8233.
A note on Danish tax
This page is about US withholding. It does not determine how Denmark taxes the same income, and it does not calculate Danish tax on US dividends.
Company tax, VAT, and whether a dividend meets the 80% voting-power test are questions for a Danish accountant. The W-8BEN-E only tells the US payer which treaty rate to apply at source.
Ready to fill the form with the Danish article numbers?
The wizard asks the same questions as this page and suggests the article and rate on Line 15 when there is one to claim.