W-8BEN-E for a Greek IKE: the 1950 treaty does not cut US dividends
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Treaty articles and rates on this page are checked against the US-Greece income tax convention signed at Athens on February 20, 1950, and the Protocol signed April 20, 1953 (irs.gov/pub/irs-trty/greece.pdf) — last verified September 2026. Ratifications were exchanged on December 30, 1953. The convention is effective from January 1, 1953. The official text numbers articles with Roman numerals. This page cites the Arabic numbers that go on the form.
 AI-generated image
Many guides quote a 15% treaty rate for Greece. There isn't one. Dividends paid by US companies to Greek residents are withheld at the statutory 30%. The convention does not give a reduced rate for those dividends.
This guide is for a Greek Idiotiki Kefalaiouchiki Etaireia (IKE) or an Anonymi Etaireia (AE) that invoices US clients. Work done in Greece is not US-source income: Part III (Lines 14a, 14b and 15) stays blank. The guide covers which US-source income is exempt, why the form uses Arabic numbers (Article 3(1), Article 6(1), Article 7) instead of the Roman numerals of the 1950 text, why Line 14b is No LOB article in treaty when the company claims the treaty, and which number goes on Line 9b. The sample PDF further down shows the claim case: staff performing services on site in the United States, with no US permanent establishment, Article 3(1) at 0%.
If you are a self-employed person (atomiki epicheirisi), you file Form W-8BEN, not this one: start the W-8BEN wizard. Services you perform in Greece are foreign-source and have no US withholding: Part II (Lines 9 and 10) of Form W-8BEN stays blank. Pay for services you perform in the United States is claimed on Form 8233, not Form W-8BEN, under Article X of the convention (Article 10). Do not cite Article 14. A resident of Greece is exempt there only if present in the United States for no more than 183 days in the taxable year and either the services are performed as an employee of, or under contract with, a resident, corporation or other entity of Greece, or the compensation does not exceed $10,000. Your AFM, the same 9-digit number a company uses, goes on Line 6a of Form W-8BEN.
Start the W-8BEN-E wizard now. In a few minutes you have a signature-ready PDF for $30: Part III blank for work done in Greece, or, for services performed in the United States with no US permanent establishment, Article 3(1) at 0% and Line 14b set to No LOB article in treaty.
Blank form or already filled in?
You can download the official, blank form from the IRS and complete it yourself — or get the same file already filled in by our wizard.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for an IKE, an EPE, or an AE.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for a self-employed individual.
- Already filled in (5–10 minutes): W-8BEN-E for Greek companies ($30) or W-8BEN for individuals ($5).
- The convention: US-Greece Income Tax Treaty PDF on IRS.gov — signed February 20, 1950. Article III is industrial or commercial profits. There is no Limitation on Benefits article.
IKE, EPE, or AE?
Greek company law uses more than one limited company, and US tax classification does not follow the local label one-for-one:
- Anonymi Etaireia (AE / Α.Ε.): 26 CFR 301.7701-2(b)(8)(i) lists "Greece, Anonymos Etairia" as a per se corporation. It is a Corporation and cannot file Form 8832.
- Idiotiki Kefalaiouchiki Etaireia (IKE / ΙΚΕ): The usual private company. It is not on the per se list. It defaults to Corporation because its members have limited liability, and a different US classification is made on Form 8832. A single-member IKE is not disregarded by default.
- Etaireia Periorismenis Efthynis (EPE / ΕΠΕ): Also not on the per se list. It defaults to Corporation for the same reason, and Form 8832 is how a different US classification is made.
- Omorrythmi or Eterorrythmi Etaireia (OE / EE): Defaults to Partnership when at least one partner has unlimited liability, under 26 CFR 301.7701-3(b)(2). Check Partnership in Part I, line 4, not Corporation.
- Atomiki epicheirisi: Not a company. That person files Form W-8BEN; Part II (Lines 9 and 10) stays blank for work done in Greece, and pay for services performed in the United States goes on Form 8233 under Article 10, not Article 14.
The trap worth naming: an IKE is not the AE on the per se list. It defaults to Corporation and can leave that default on Form 8832. The treaty question is separate. Even a correctly classified Corporation writes Arabic article numbers, not the Roman numerals printed in the 1950 text.
Chapter 3 still decides which form you file. Part III is where the article and the rate go when the company claims the treaty, and Line 14b for this treaty is then the box that says the treaty has no Limitation on Benefits article. Work done in Greece needs no claim: Part III (Lines 14a, 14b and 15) stays blank.
Who actually needs to submit this form?
Any Greek IKE, EPE, or AE that receives payments from a US business and needs to document that it is not a US person. What you claim in Part III depends on the income:
- Services performed in Greece: Not US-source income, so there is no US withholding and Part III (Lines 14a, 14b and 15) stays blank.
- Services performed in the United States, with no US permanent establishment: Article III in the convention, written as Article 3(1) on the form, at 0%. Industrial or commercial profits of a Greek enterprise are not taxed by the United States unless the enterprise carries on business there through a permanent establishment.
- A US dividend: No treaty article and no reduced rate. The statutory 30% applies. Article IX is about dividends and interest paid by a Greek corporation. It does not cut a dividend from a US company. A W-8BEN-E is still the form that tells the payer you are foreign, which matters for backup withholding. It will not turn the statutory 30% into 15%.
- A software licence, not a film: Royalties for copyrights, patents, designs, secret processes, trademarks, and know-how, and rentals of industrial, commercial, or scientific equipment, are Article VII, written as Article 7, at 0% for a recipient with no US permanent establishment. Royalties for motion picture films are excluded and stay at 30%.
Roman numerals on the form, and no LOB article
The official text says Article III, Article VI, Article VII, and Article X. The forms ask for an Arabic article number. On Form W-8BEN-E write Article 3(1) for industrial or commercial profits from services performed in the United States, Article 6(1) for interest, and Article 7 for the royalties that the convention exempts. An individual's pay for services performed in the United States is Article 10, claimed on Form 8233. Do not write III, VI, VII, or X in the article box.
The 1950 convention has no Limitation on Benefits article. When the company claims the treaty, Line 14b is the checkbox "No LOB article in treaty". Do not certify active trade or business, ownership and base erosion, or publicly traded. Those tests are not in this treaty. With no claim, Line 14b stays blank.
| Step | Result |
|---|---|
| 1. Company services performed in Greece | Part III (Lines 14a, 14b and 15) stays blank. |
| 2. Company services performed in the United States, no US permanent establishment | Article 3(1) (III in the text), 0%. |
| 3. Interest from a US debtor | Article 6(1) (VI), 0%, for a recipient with no US permanent establishment, unless a US corporation pays it to a Greek company that controls, directly or indirectly, more than 50% of the entire voting power of that US corporation. |
| 4. Software, patents, trademarks, know-how, equipment rental | Article 7 (VII), 0%, for a recipient with no US permanent establishment. |
| 5. Motion picture film royalties | No exemption. Statutory 30%. |
| 6. Dividends from a US company | No article and no reduced rate. Statutory 30%. |
| 7. Line 14b | Only with a treaty claim: No LOB article in treaty. |
Why this treaty is still the 1950 text
The convention was signed at Athens on February 20, 1950. A protocol signed April 20, 1953 limits mutual assistance in collection. It does not add a dividend rate. Ratifications were exchanged on December 30, 1953, and the convention is effective from January 1, 1953. No later convention has replaced it as of 2026. Do not import a 5% or 15% dividend rate from a modern treaty.
Line by line for an operating IKE
Most IKEs invoice US clients for work done in Greece. That income is not US-source: Part III (Lines 14a, 14b and 15) stays blank. Lines 14a, 14b and 15 are filled only when the company claims the treaty, for example for interest under Article 6(1), royalties under Article 7, or services performed in the United States with no US permanent establishment under Article 3(1). The sample below is that last case.
| Line | What you enter |
|---|---|
| Line 1 | The legal name, for example Aegean IKE. |
| Line 2 | Greece. |
| Line 4 | Corporation for an IKE, an EPE, or an AE. Partnership for an OE or EE. A self-employed individual files Form W-8BEN. |
| Line 6 | The registered office in Latin letters (e.g., Panepistimiou 20, Athens, 106 71). |
| Line 9b | The AFM (ΑΦΜ), 9 digits, for example 123456783. A self-employed person's AFM has the same format, but it goes on Line 6a of Form W-8BEN, which has no Line 9b. 123456789 fails the check digit. Do not enter a ΓΕΜΗ (GEMI) number. Do not add EL unless the payer asked for a VAT ID. |
| Line 14a | Only when the company claims the treaty: Greece. Blank for services performed in Greece. |
| Line 14b | Only when the company claims the treaty: No LOB article in treaty. Do not check active trade or business, ownership and base erosion, or publicly traded. Blank for services performed in Greece. |
| Line 15 | Blank for services performed in Greece. For services performed in the United States with no US permanent establishment: Article 3(1), 0%, type of income Services. Do not write III. Interest is Article 6(1) at 0% for a company with no US permanent establishment, unless a US corporation the company controls (more than 50% of the entire voting power, directly or indirectly) pays it. A software licence is Article 7 at 0% for a company with no US permanent establishment. A US dividend has no article and no rate on this line. |
Read the AFM from the tax record before Line 9b. The company registry number at ΓΕΜΗ is not the TIN. EL followed by the AFM is the VAT number.
The guided W-8BEN-E wizard leaves Part III blank for work done in Greece. When the company claims the treaty, it writes Arabic article numbers and sets Line 14b to No LOB article in treaty.
Filled example: Aegean IKE
An IKE whose staff perform services on site in the United States, with no US permanent establishment. Chapter 3 Corporation, FATCA Active NFFE, Part III Article 3(1) at 0% for industrial or commercial profits from services performed in the United States, Line 14b No LOB article in treaty, AFM 123456783. Work done only in Greece would leave Part III blank.
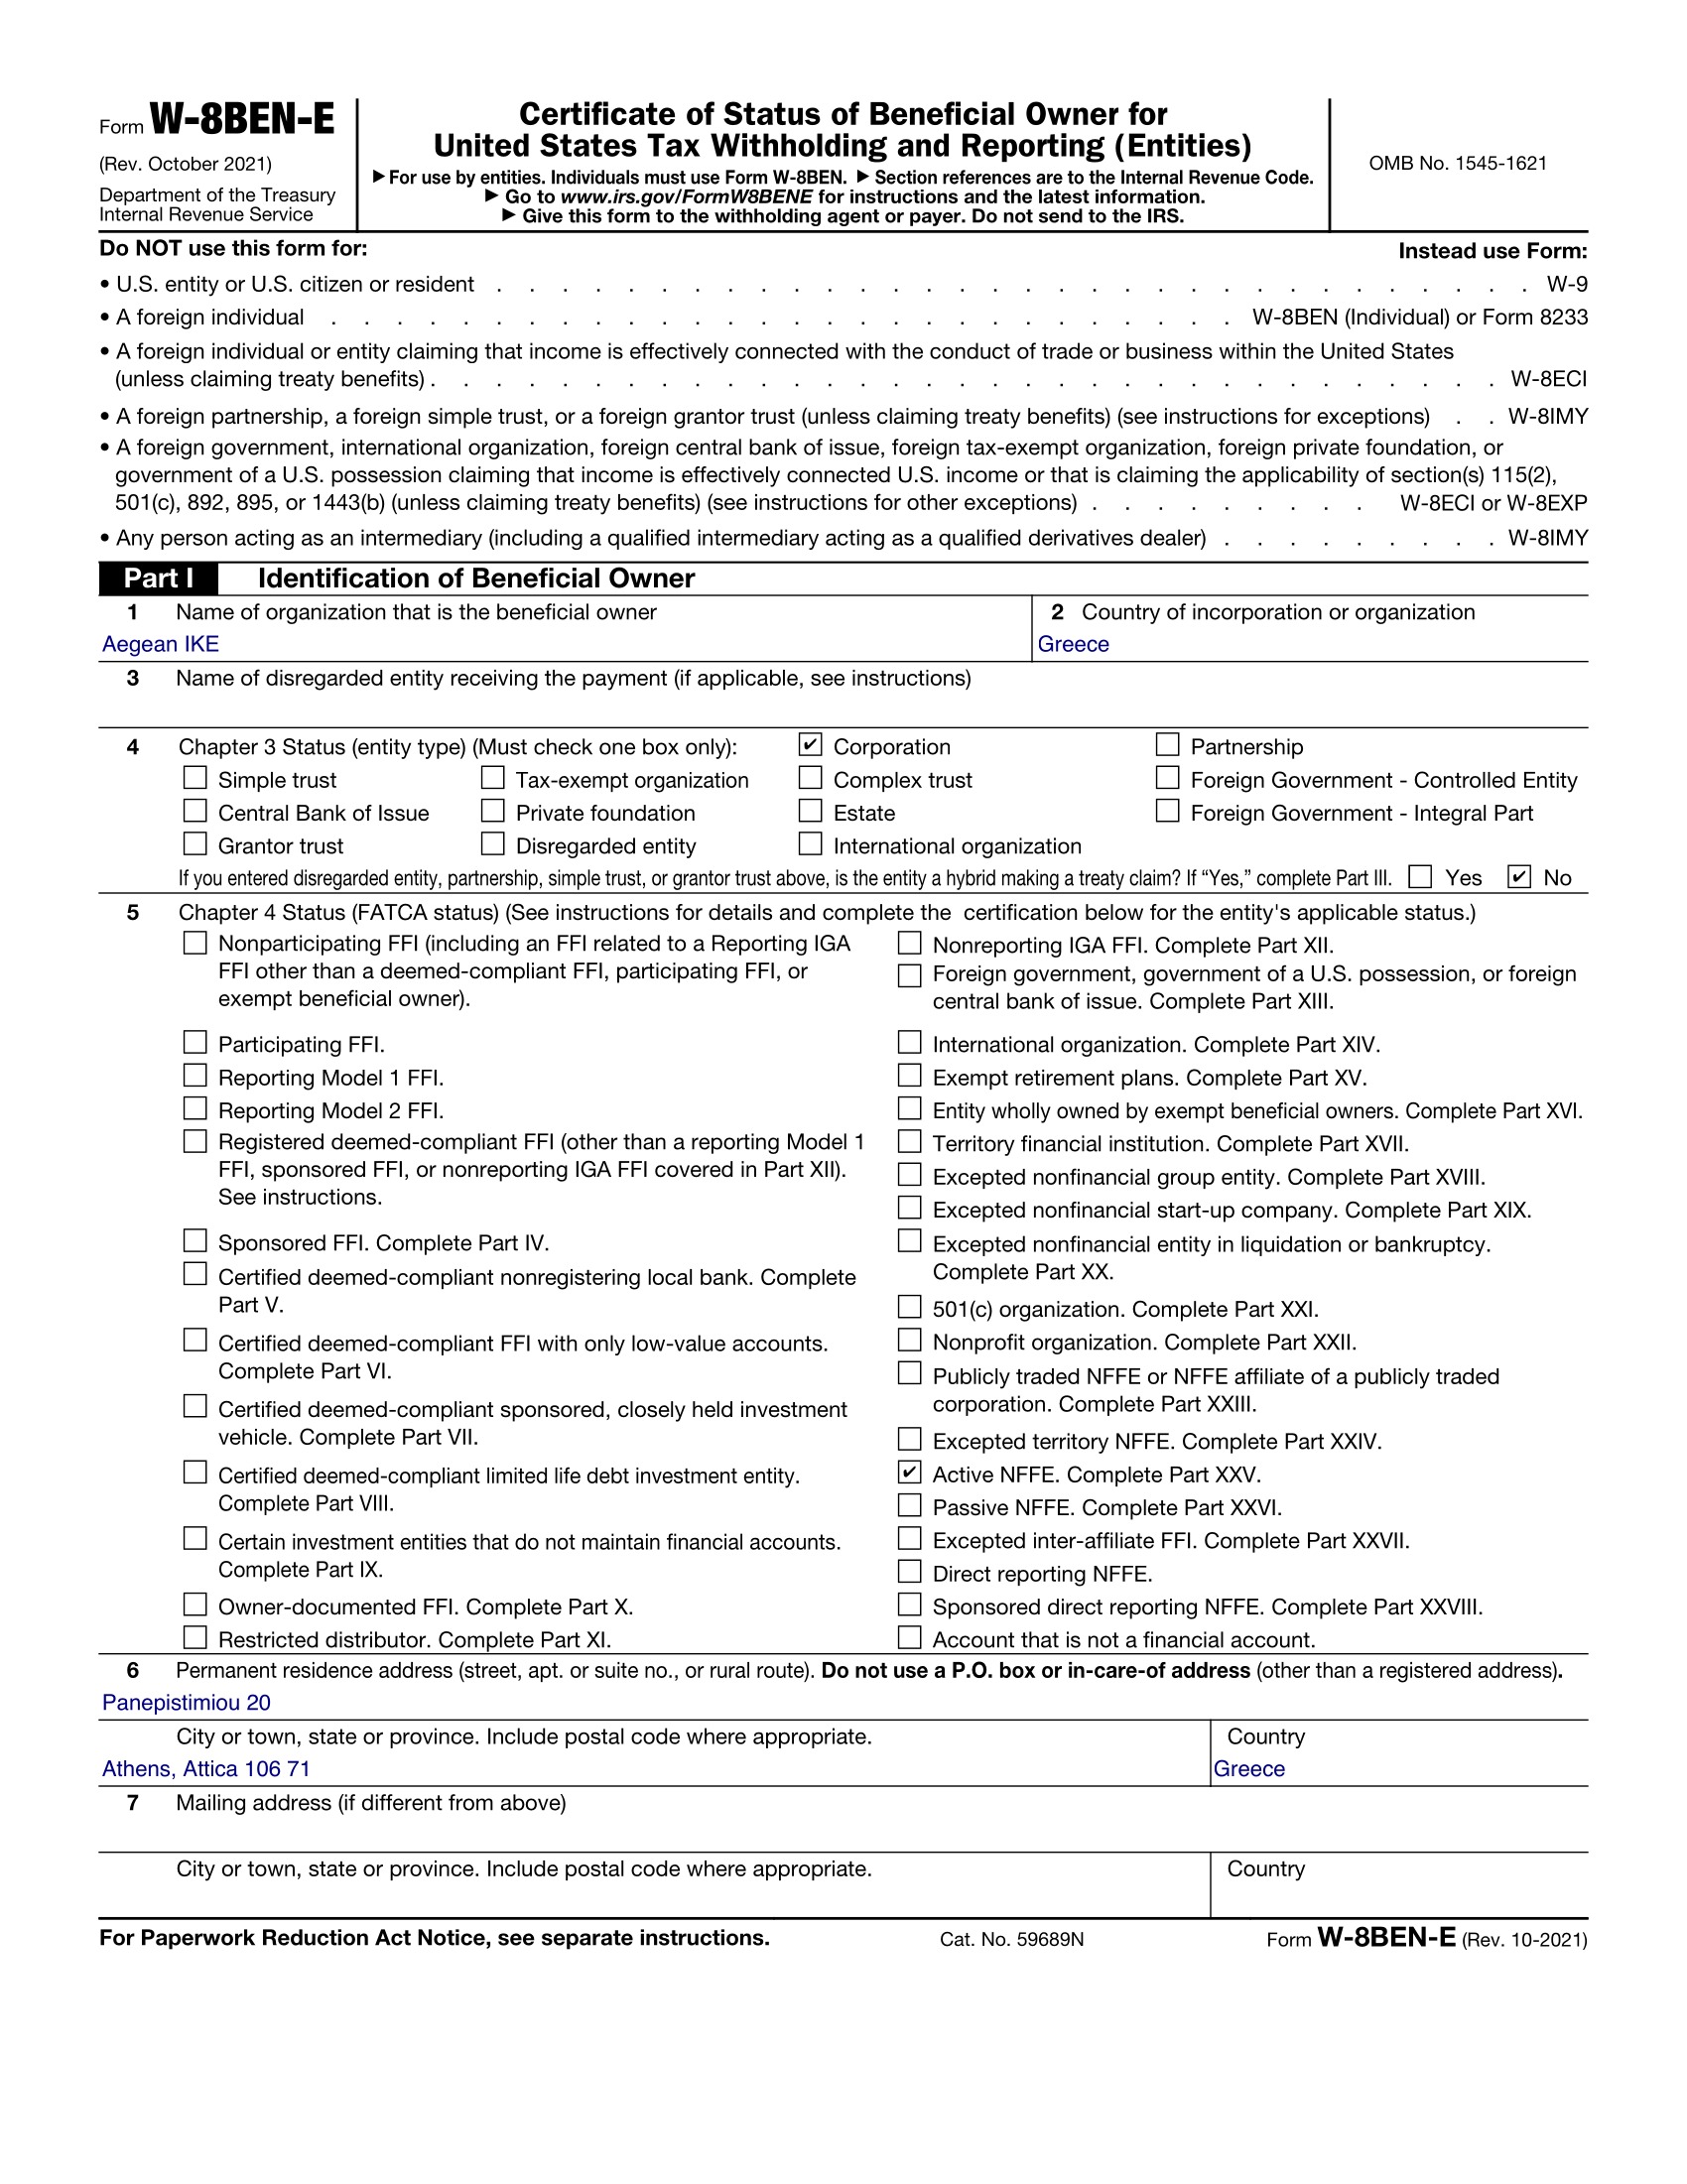
Sample only — uses a fictional company for illustration. Example: Aegean IKE, Panepistimiou 20, Athens 106 71, Greece, AFM 123456783, Chapter 3 Corporation, FATCA Active NFFE, Article 3(1) at 0% for services performed in the United States with no US permanent establishment, Line 14b No LOB article in treaty. A US dividend would not use this Part III rate.
What is exempt, and what stays at 30%
Use Arabic numbers on the form. The Roman numeral is the same article in the 1950 text.
| Income type | Article | Rate |
|---|---|---|
| Services of a company performed in Greece | No claim, Part III blank | No US withholding |
| Services of a company performed in the United States, no US permanent establishment | Article 3(1) | 0% |
| Interest of a recipient with no US permanent establishment, unless a US corporation pays it to a Greek company that controls, directly or indirectly, more than 50% of its entire voting power | Article 6(1) | 0% |
| Software, patents, trademarks, know-how, and equipment rental, recipient with no US permanent establishment | Article 7 | 0% |
| Motion picture film royalties | No article | 30% |
| Dividends paid by a US company | No article | 30% |
| Personal services of an individual performed in the United States (Form 8233, not Form W-8BEN) | Article 10(1) | 0% only if no more than 183 days and either work for, or under contract with, a resident, corporation or other entity of Greece, or no more than $10,000 |
Article 6(1) is 0% for US-source interest received by a Greek resident or corporation with no US permanent establishment, except interest paid by a US corporation to a Greek corporation that controls, directly or indirectly, more than 50% of the entire voting power in the paying corporation. That related-party interest has no treaty exemption. Article 7 does not cover motion picture films. Article 9 in the convention is about Greek-source dividends and interest. It is not a rate for a dividend from a US company. An individual claims Article 10 on Form 8233, for services performed in the United States, only when the 183-day test and either the Greek employer or contract test (a resident, corporation or other entity of Greece) or the $10,000 cap are met. Services performed in Greece are foreign-source: Part III of Form W-8BEN-E, or Part II (Lines 9 and 10) of Form W-8BEN, stays blank.
Questions people ask before they sign
Short answers for an IKE. A US office, a fund, or a financial institution needs an accountant, not a blog page.
Why does my broker withhold 30% on dividends if Greece has a treaty?
Because this treaty does not reduce dividends paid by US companies. The statutory 30% applies. Article IX covers dividends and interest paid by a Greek corporation. A form still documents foreign status, which can matter for backup withholding, but it does not create a 15% or 5% rate.
Which article for services — 7 or III?
None, for services performed in Greece: that income is not US-source, and Part III (Lines 14a, 14b and 15) stays blank. For a company's services performed in the United States with no US permanent establishment, Article III, written as Article 3(1), at 0%. Do not write the Roman numeral, and do not cite Article 7 for services. On this form Article 7 is the royalty article (VII in the text), not a modern Business Profits article.
Are film royalties exempt?
No. Royalties in respect of motion picture films are excluded from Article VII and stay at the statutory 30%. A software copyright, a patent, a trademark, know-how, and equipment rental can be Article 7 at 0% when the recipient has no US permanent establishment.
Is a new treaty coming?
No later convention has replaced the 1950 text as of 2026. The 1953 protocol limits collection assistance. It does not add a dividend rate.
I'm a freelancer in Greece — which article?
None, for work you do in Greece: it is not US-source income, so Part II (Lines 9 and 10) of Form W-8BEN stays blank. For services you perform in the United States, Article 10 (Article X in the convention), claimed on Form 8233, not Form W-8BEN. It covers labor and personal services, including the liberal and artistic professions. Exemption needs no more than 183 days in the United States and either services performed as an employee of, or under contract with, a resident, corporation or other entity of Greece, or compensation of no more than $10,000. Do not cite Article 14.
Which number goes on Line 9b?
The AFM, 9 digits, for example 123456783. A self-employed person's AFM has the same format, but it goes on Line 6a of Form W-8BEN, which has no Line 9b. 123456789 fails the check digit. ΓΕΜΗ (GEMI) is the registry, not the TIN. EL plus the AFM is the VAT number. Do not type the EL prefix unless the payer asked for a VAT ID.
Can an IKE file Form 8832?
Yes, when it needs a US classification other than Corporation. An AE is per se under "Greece, Anonymos Etairia" and cannot file Form 8832. An IKE and an EPE are not on that list. They default to Corporation, and Form 8832 is how they elect a different classification. A single-member IKE is not disregarded by default.
What if the Greek company owns the US payer?
Interest paid by a US corporation to a Greek corporation that controls, directly or indirectly, more than 50% of the entire voting power in the paying corporation has no treaty exemption: leave the claim blank for it, and withholding stays at 30%. Other interest can be Article 6(1) at 0% when there is no US permanent establishment. The wizard asks the company to confirm the payer is not such a corporation before it writes Article 6(1).
What to do next
- Fill out your W-8BEN-E in the guided wizard: Start the W-8BEN-E wizard ($30). It leaves Part III blank for work done in Greece, cites Article 3(1) for services performed in the United States with no US permanent establishment, and then sets Line 14b to No LOB article in treaty.
- Are you self-employed?: Use the W-8BEN wizard ($5). Part II (Lines 9 and 10) stays blank for work done in Greece; pay for services performed in the United States goes on Form 8233 under Article 10, not Article 14.
Mistakes that get the form sent back
- Writing 15% on a US dividend: This treaty has no reduced rate for dividends paid by US companies. The statutory rate is 30%.
- Filling Part III for work done in Greece: Services performed in Greece are not US-source income. Leave Part III (Lines 14a, 14b and 15) blank.
- Citing Article 7 for company services: Services performed in the United States with no US permanent establishment are Article 3(1). Article 7 on the form is royalties. The convention prints those as III and VII.
- Citing Article 14 for a freelancer: An individual's article is Article 10 (Article X), claimed on Form 8233 for services performed in the United States. For work done in Greece, Part II (Lines 9 and 10) of Form W-8BEN stays blank.
- Picking an LOB test: There is no Limitation on Benefits article. When the company claims the treaty, Line 14b is No LOB article in treaty.
- Typing an invalid AFM: Line 9b takes 9 digits that pass the check digit, for example 123456783. 123456789 fails. ΓΕΜΗ is not the TIN, and EL is the VAT prefix.