W-8BEN-E for an Icelandic ehf. (and W-8BEN for a Sole Proprietor): US–Iceland Treaty Guide (2026)
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Last checked: 29.09.2026 against the 2007 US–Iceland convention on home.treasury.gov (Treaty-Iceland-10-22-2007.pdf), signed at Washington on October 23, 2007. Under Article 27(2) it has effect for tax withheld at source on income derived from 1 January of the year after it entered into force. The IRS file irs.gov/pub/irs-trty/iceland.pdf is the superseded 1975 convention. This page follows the 2007 text.
 AI-generated image
Search results, and the PDF linked from the IRS treaty page, still show the 1975 US–Iceland treaty. The 2007 convention in force has different article numbers: business profits are Article 7, dividends Article 10, interest Article 11 and royalties Article 12.
This guide is for an einkahlutafélag (ehf.) that invoices US clients, licenses software, or holds US stocks, and for an einstaklingsrekstur. It covers which form you file, why an hf. is per se, and which kennitala goes on the tax line. Work an ehf. does in Iceland is not US-source income: there is no US withholding to reduce, and Part III of Form W-8BEN-E (Lines 14a, 14b and 15) stays blank. The filled sample PDF further down shows the other case: staff of the ehf. performing services on site in the United States, with no US permanent establishment, which claims Article 7(1) at 0%.
An einstaklingsrekstur is a person who carries on business under personal liability. That person files Form W-8BEN, not Form W-8BEN-E: start the W-8BEN wizard. Work done in Iceland is not US-source income, so Part II of Form W-8BEN (Lines 9 and 10) stays blank. Pay for personal services the person performs in the United States goes on Form 8233, not Form W-8BEN, under Article 7(1): the 2007 treaty has no independent personal services article, because Article 3(1)(k) folds those services into business. Article 14 is Income from Employment.
If you prefer to skip the reading, start the W-8BEN-E wizard. For services an ehf. performs in Iceland it leaves Part III blank. For services its staff perform in the United States with no US permanent establishment it cites Article 7(1) at 0%, and Line 14b is Ownership and base erosion when the ehf. meets both prongs of Article 21(2)(e): the Iceland-resident ownership test and the base-erosion test. A signature-ready PDF is $30. Form W-8BEN for a person is $5.
Blank form or already filled in?
You can download the official blank form from the IRS, or get the same file already filled in.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for an ehf. or an hf.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for an einstaklingsrekstur.
- Already filled in (5–10 minutes): W-8BEN-E for an Icelandic ehf. ($30) or W-8BEN for a sole proprietor ($5).
- The convention in force: 2007 US–Iceland Income Tax Treaty PDF on Treasury.gov — signed October 23, 2007. Business profits are Article 7.
- Do not use the 1975 PDF: irs-trty/iceland.pdf is the superseded 1975 convention. Its article numbers are not the ones on the form.
ehf., hf., sf., or a sole proprietor?
26 CFR 301.7701-2(b)(8)(i) lists Iceland, Hlutafelag. US classification does not follow the local abbreviation one-for-one:
- Hlutafélag (hf.): A public limited company. It is a per se corporation and it cannot file Form 8832. There is no ownership-change grandfather.
- Einkahlutafélag (ehf.): The usual private company, under its own statute. It defaults to Corporation. The IRS has not clarified whether Hlutafelag covers an ehf. Confirm with a tax advisor before filing Form 8832. A single-member ehf. is not disregarded by default.
- Sameignarfélag (sf.) or samlagsfélag (slf.): These default to Partnership.
- Einstaklingsrekstur: A person, not a company. That person files Form W-8BEN. Work done in Iceland leaves Part II (Lines 9 and 10) blank; pay for personal services performed in the United States goes on Form 8233.
Chapter 3 still decides which form you file. Part III is where the article and the rate go, and only when the company claims the treaty. On Line 14b, an operating ehf. owned by residents of Iceland can meet Ownership and base erosion under Article 21(2)(e). A US-resident owner does not count toward that test.
Article 21 and a foreign owner
Article 21(2)(e)(i) counts residents of Iceland who qualify under Article 21(2)(a), (b), (c)(i), or (d). On at least half the days of the year they must own at least 50% of each class. Each intermediate owner must be a resident of Iceland. A US-resident owner does not count. The base-erosion prong leaves out arm's-length payments for services or tangible property. A payment on a financial obligation to a bank in a third country is left out only when it is attributable to a permanent establishment of that bank in Iceland or in the United States. A payment to a bank that is itself a resident of Iceland or of the United States is left out even without a permanent establishment. A payment to a third-country bank with no such permanent establishment still counts.
Article 21(3) derivative benefits can apply when at least 95% of the vote and value is owned by seven or fewer equivalent beneficiaries in the EU, the EEA, a NAFTA country, or an EFTA state, and the base-erosion clause is met. Illustration only, not a conclusion for a named company: an ehf. owned 100% by a resident of Reykjavik meets the ownership prong of Article 21(2)(e). An ehf. owned 100% by a resident of Norway does not meet that ownership prong. Norway is an EFTA state, so derivative benefits may be available. The US–Norway dividend rate is 15%, so the not-higher-rate condition fails for Iceland's 5% dividend rate and can be met for a 0% software royalty. Confirm the item of income with a tax advisor.
Line 9b and Part III
Iceland uses one 10-digit kennitala for a person and for a company. Do not enter the VSK number. Part III (Lines 14a, 14b and 15) stays blank for services an ehf. performs in Iceland; it is filled only when the company claims the treaty, for example for services performed in the United States, dividends, interest or royalties.
| Line | What you enter |
|---|---|
| Line 9b of Form W-8BEN-E | The 10-digit kennitala, for example 5503101390. The day digits are the registration day plus 40. Weights 3, 2, 7, 6, 5, 4, 3, 2. 5503101390 passes. 4504013150 passes. Do not enter the VSK number. |
| Foreign TIN on Form W-8BEN | The person's 10-digit kennitala, for example 0101851229. 0101851229 passes. 1201743399 passes. 0101851228 fails. The company's kennitala does not replace the person's kennitala on Form W-8BEN. |
| Line 14a | Only when the company claims the treaty: Iceland. Blank for services performed in Iceland. |
| Line 14b | Only when the company claims the treaty: the Article 21 test the ehf. meets, for example Ownership and base erosion when residents of Iceland meet Article 21(2)(e). A US-resident owner does not count. Derivative benefits is a separate box, including an EFTA owner, and it is not the default. |
| Line 15 | Only when the company claims the treaty; blank for services performed in Iceland. For services the ehf.'s staff perform in the United States: Article 7(1), 0%, when the ehf. has no permanent establishment in the United States. A construction project is a permanent establishment only after 12 months. Do not cite Article 14. |
Read the kennitala from the company register before Line 9b. The form stores the name in Latin letters A–Z, so Norðurljós ehf. is written Nordurljos ehf.
Sample: completed W-8BEN-E for an Icelandic ehf.
A filled example of the claim case: a fictional ehf. in Reykjavik whose staff perform services on site in the United States, with no US office, dependent agent or other permanent establishment there. Chapter 3 Corporation, Line 14b Ownership and base erosion, Line 15 Article 7(1) at 0%. Services performed only in Iceland would leave Part III blank.
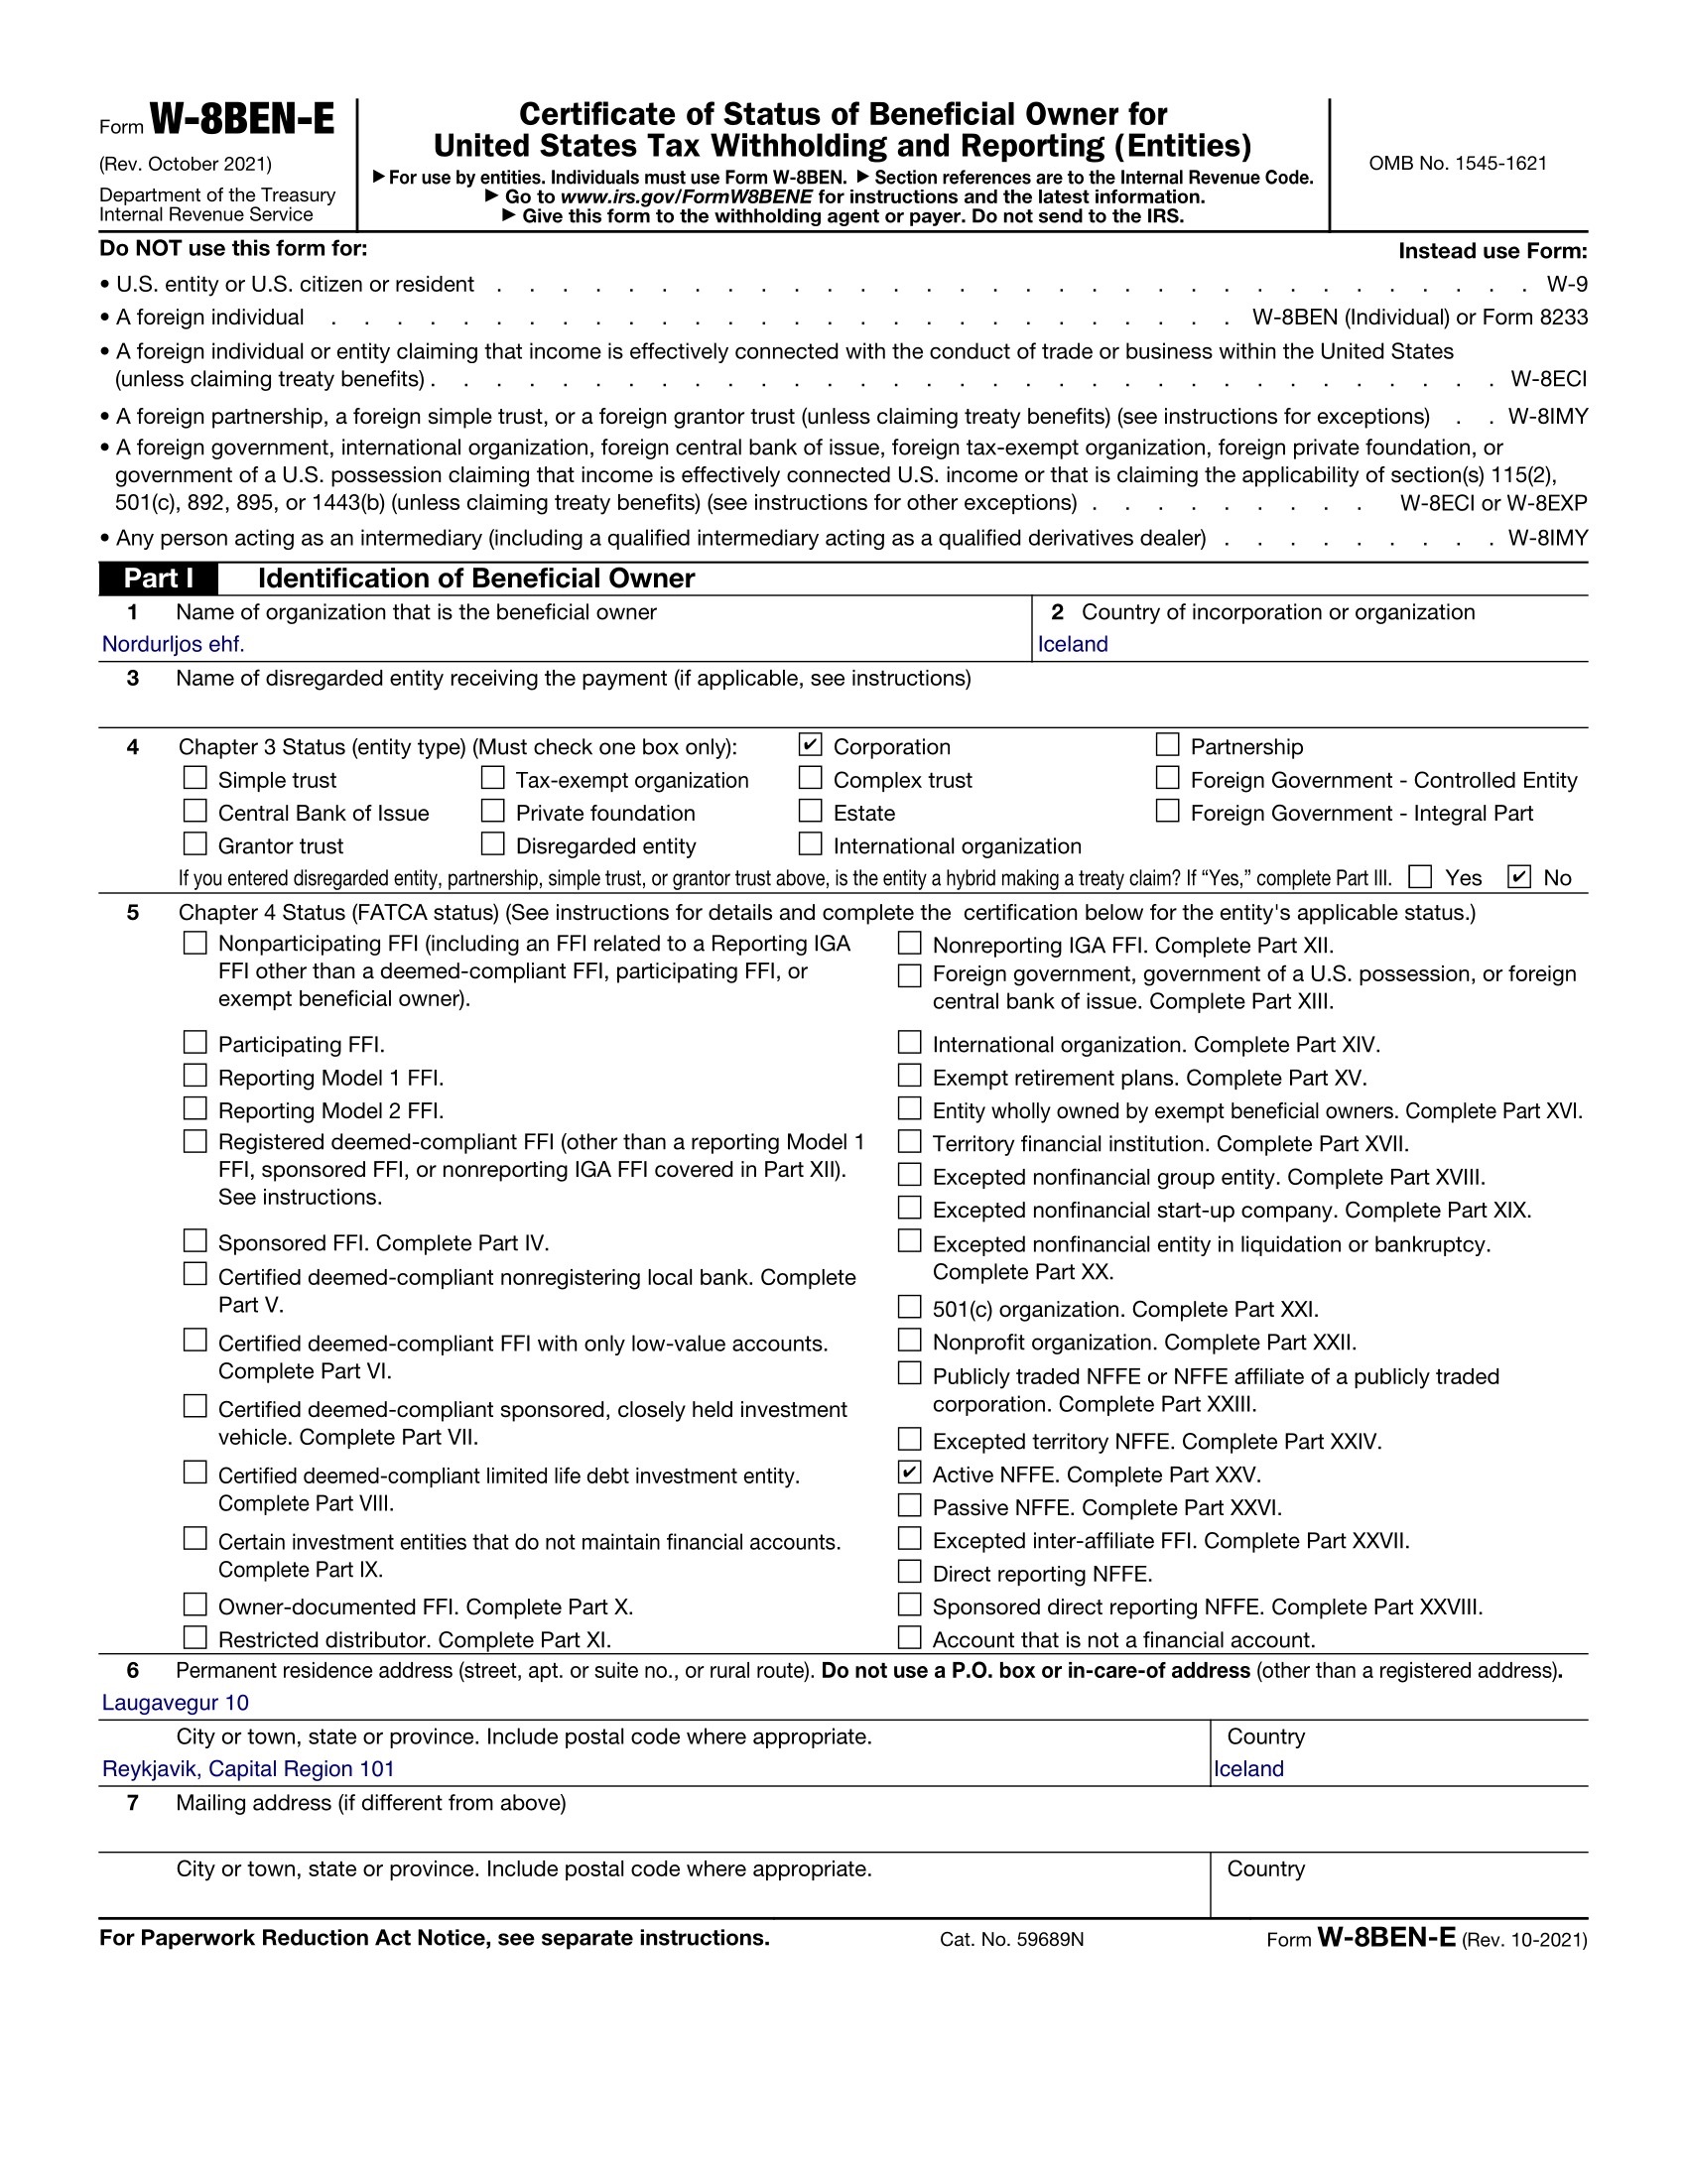
Sample only. Nordurljos ehf., Laugavegur 10, Reykjavik 101, Iceland, kennitala 5503101390, Chapter 3 Corporation, FATCA Active NFFE, Article 7(1) at 0% for services performed in the United States with no US permanent establishment, Ownership and base erosion.
What happens to the income
Each row stands on its own. Do not move a rate onto the neighbouring row. Do not cite the 1975 article numbers.
| Income | Article | Rate and condition |
|---|---|---|
| Services of an ehf. performed in Iceland | None | No US withholding: the income is not US-source. Part III (Lines 14a, 14b and 15) stays blank. |
| Services of an ehf. performed in the United States | Article 7(1) | 0% — only if the ehf. has no permanent establishment in the United States. A construction or installation project is a permanent establishment only after 12 months. Otherwise the United States may tax the profits attributable to that permanent establishment. |
| Services of a sole proprietor or freelancer | None on Form W-8BEN | Work done in Iceland: Part II (Lines 9 and 10) stays blank. Pay for personal services performed in the United States goes on Form 8233, under Article 7(1). Article 14 is Income from Employment. Do not cite Article 14 for these services. |
| Software licence, copyright, patents, know-how | Article 12(1) | 0% — a copyright of a literary, artistic, scientific or other work, including computer software, plus patents and know-how. Only the arm's-length amount between related parties. |
| Trademark plus know-how under a franchise or rental agreement | Article 12(2)(a) | Up to 5% — a trademark and information concerning industrial, commercial or scientific experience, when they are provided with a rental or franchise agreement that includes the right to use the trademark. |
| Film or video for use in connection with television | Article 12(2)(b) | Up to 5% — a motion picture film or a work on film, videotape, or other means of reproduction for use in connection with television. |
| Equipment rental in the course of the ehf.'s trade or business | Article 7(1) | 0% — only with no US permanent establishment and no US activity for the lease. A lessor with activity in the United States, with or without a permanent establishment there, makes no claim for that rent: Part III (Lines 14a, 14b and 15) stays blank. Equipment rental is not a royalty under Article 12. |
| Passive equipment rental | Article 20(1) | 0% as other income — only with no US activity for the lease. A lessor with activity in the United States, with or without a permanent establishment there, makes no claim for that rent: Part III (Lines 14a, 14b and 15) stays blank. Under Article 20(2), income connected with a US permanent establishment goes to Article 7. |
| Interest | Article 11(1) | 0% — taxable only in Iceland under Article 11(1). Up to 15% under Article 11(5)(a) when the interest is determined with reference to receipts, sales, income, profits or other cash flow of the debtor or a related person, to any change in the value of any property of the debtor or a related person, or to any dividend, partnership distribution or similar payment made by the debtor to a related person. Under Article 11(5)(b), an excess inclusion on a residual interest in a REMIC may be taxed by each State under its own law. |
| Dividends — company holding directly at least 10% of the share capital | Article 10(2)(a) | 5% — only when the beneficial owner is a company that holds directly at least 10% of the share capital. This rate does not apply to RIC or REIT dividends. An indirect holding does not qualify. |
| Dividends — all other cases | Article 10(2)(b) | 15% — when the company does not hold directly at least 10% of the share capital, and for an individual. RIC dividends are 15%. |
| REIT dividends | Article 10(3) | 15% only for an individual holding not more than 10% of the REIT, or a holder of not more than 5% of any class when the dividend is paid on a publicly traded class, or not more than 10% of a diversified REIT. Otherwise 30%. A pension scheme or employee benefit organization keeps 0% under Article 10(4). |
| Dividends — Icelandic pension scheme or employee benefit organization | Article 10(4) | 0% — for a resident described in Article 4(2)(a) or (b): a pension scheme as Article 3(1)(l) defines it (in Iceland, a pension fund or plan qualified under the Pension Act), or an arrangement operated exclusively to administer or provide employee benefits and generally exempt from income tax by reason of its nature. Only when the dividends are not derived from the carrying on of a business, directly or indirectly, by it. It applies notwithstanding paragraphs 2 or 3, so RIC and REIT dividends too. On Line 14b it qualifies under Article 21(2)(d) only when more than 50% of its beneficiaries, members or participants are individuals resident in Iceland or the United States. |
| Artists and athletes performing in the US | Article 16 | 0% if gross receipts from performances in the United States, including reimbursed expenses, do not exceed USD 20,000 in the tax year. Otherwise the United States may tax the income from activities exercised in the United States. |
Form W-8BEN-E cites the 2007 article numbers. An ehf. whose staff perform services in the United States with no US permanent establishment writes Article 7(1), not an article number from the 1975 PDF; for work done in Iceland, Part III stays blank.
Questions people ask before they sign
Short answers for an ehf. or a sole proprietor. A fund or a bank needs an accountant, not this page.
Why do some sites say Article 18 or 14 for freelancers?
Those numbers belong to the 1975 convention, which is the PDF at irs-trty/iceland.pdf. The treaty in force is the 2007 convention, and Article 14 of the 2007 text is Income from Employment. A freelancer working in Iceland has no US-source income: Part II of Form W-8BEN (Lines 9 and 10) stays blank. Pay for personal services performed in the United States goes on Form 8233, under Article 7(1).
Is my ehf. a per se corporation?
The eCFR names Hlutafelag, which is an hf. An hf. is per se and cannot file Form 8832. An ehf. defaults to Corporation. The IRS has not clarified whether Hlutafelag covers an ehf. Confirm with a tax advisor before filing Form 8832.
YouTube or AdSense?
A copyright royalty for the content can be Article 12(1) at 0%. If the payer qualifies the same payment as a film or video for use in connection with television, Article 12(2)(b) is up to 5%. This page does not pick Google's qualification. Website AdSense earned from work done in Iceland is not a royalty and not US-source: Part III (Lines 14a, 14b and 15) of Form W-8BEN-E, or Part II (Lines 9 and 10) of Form W-8BEN, stays blank.
US dividends at 10% ownership?
Article 10(2)(a) is 5% when the company holds directly at least 10% of the share capital. An indirect 10% holding stays at 15% under Article 10(2)(b). RIC and REIT dividends do not get the 5% rate.
What to do next
- Fill out W-8BEN-E in the guided wizard: Start the W-8BEN-E wizard ($30). For services an ehf.'s staff perform in the United States with no US permanent establishment it uses Article 7(1) at 0%; for work done in Iceland it leaves Part III blank.
- Are you a sole proprietor?: Use the W-8BEN wizard ($5). Work done in Iceland leaves Part II blank; pay for personal services performed in the United States goes on Form 8233.
Mistakes that get the form sent back
- Article numbers from 1975: irs-trty/iceland.pdf is not the treaty in force. Business profits are Article 7. Royalties are Article 12. Dividends are Article 10.
- Article 14 for a freelancer: Article 14 is Income from Employment. Work done in Iceland leaves Part II (Lines 9 and 10) blank; pay for personal services performed in the United States goes on Form 8233, under Article 7(1).
- Article 7(1) for services performed in Iceland: That income is not US-source. Part III (Lines 14a, 14b and 15) stays blank. Article 7(1) at 0% is for services performed in the United States with no US permanent establishment.
- 0% on a trademark franchise: Article 12(2)(a) is up to 5% when know-how travels with a rental or franchise agreement that includes the trademark.
- 5% on an indirect dividend holding: Article 10(2)(a) requires a direct holding of at least 10% of the share capital.
- A US owner in the ownership test: Article 21(2)(e)(i) counts residents of Iceland. A US-resident owner does not count.