W-8BEN-E for a Czech s.r.o. or a.s.: copyright royalties are 0%, industrial royalties are 10%
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Treaty articles and rates on this page are checked against the US-Czech Republic Income Tax Convention signed at Prague on September 16, 1993 (czech.pdf on IRS.gov) — last verified October 2026. Under Article 29(2) it entered into force on the exchange of instruments of ratification, and the IRS text gives January 1, 1993 as its general effective date. There is no protocol. Line 15 follows czech.pdf.
 AI-generated image
A Czech s.r.o. invoices a US client, and accounts payable asks for a W-8BEN-E before they pay. Work the s.r.o. does in the Czech Republic is not US-source income: there is no US withholding on it, nothing to claim, and Part III (Lines 14a, 14b and 15) stays blank. The company fills Part III only when it claims the treaty: for services its staff perform in the United States, for US dividends, interest or royalties, for a lease of containers used in international traffic (Article 8(3)), or for a rental of ships or aircraft under Article 8(2). Services performed in the United States, with no current and no former US permanent establishment, cite Article 7(1) at 0%. Article 7(1) says the enterprise "carries on or has carried on" business through a permanent establishment, and Article 5(3)(b) makes staff working on a US project for more than 9 months within any 12 month period a permanent establishment, except in a taxable year in which that work lasts less than 30 days. Royalties are not a flat 10% for every category. Copyrights, films, and a software copyright license cite Article 12(2) at 0%. Patents, trademarks, know-how, and equipment cite Article 12(2) at 10%. A lease of containers used in international traffic is not that royalty: it cites Article 8(3) at 0%. With a treaty claim, Line 14b certifies a Limitation on Benefits test under Article 17. For an operating s.r.o. that is usually Active trade or business, Article 17(1)(c). Article 16 is directors' fees. "No LOB article in treaty" is the wrong box. The country picker says Czechia. The treaty title says Czech Republic.
This guide uses the current IRS line numbers (Rev. October 2021) for the claim case in the sample: Bohemia s.r.o., Active NFFE, whose staff perform services on site in the United States, with no US permanent establishment, claiming Article 7(1) at 0% on those fees. It also covers the dividend split (5% when a company owns at least 10% of the voting shares, 15% otherwise, and no 0% exemption), ordinary interest at 0% under Article 11(1), and why a page that calls every royalty 10% is reading only the second sentence of Article 12(2).
If you are not incorporated — an OSVČ working under your own rodné číslo — you file Form W-8BEN, not this form: start the W-8BEN wizard. Work you do in the Czech Republic is not US-source income, so Part II (Lines 9 and 10) stays blank. Pay for independent personal services you perform in the United States is claimed under Article 14(1) on Form 8233, not on Form W-8BEN. This page is for incorporated businesses.
Or skip the reading and start the W-8BEN-E wizard — guided questions, a suggested treaty article and rate, and a signature-ready PDF for $30.
Blank form or already filled in?
You can download the official blank form from the IRS and complete it yourself, or get the same file filled from your answers. czech.pdf is the operative convention. There is no later protocol to read beside it.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for an s.r.o. or an a.s.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for an OSVČ.
- 1993 Convention: Income Tax Treaty PDF on IRS.gov — this PDF is operative for Articles 7, 10, 11, 12, 14, and 17. Do not replace it with a secondary summary.
- IRS treaty documents page: Czech Republic tax treaty documents. The operative withholding text is czech.pdf.
- Already filled in (5–10 minutes): W-8BEN-E for Czech companies ($30) or W-8BEN for an individual ($5) — treaty article and rate suggested automatically, ready to sign as a PDF.
Which Czech company type are you actually dealing with?
The Chapter 3 box depends on the legal form, not on revenue:
- Akciová společnost (a.s.) Always a Corporation for US tax purposes. 26 CFR 301.7701-2(b)(8)(i) lists "Czech Republic, Akciova Spolecnost" as a per se corporation. There is no Form 8832 election.
- Společnost s ručením omezeným (s.r.o.) The usual startup and small-company form, and the example name in the wizard is Bohemia s.r.o. It is not on the per se list. Members have limited liability, so it defaults to Corporation, but it can elect a different US classification on Form 8832. A single-member s.r.o. is not disregarded by default.
- OSVČ An individual registration, not a separate legal entity. The person files Form W-8BEN, not this form. Work done in the Czech Republic needs no treaty claim, so Part II of Form W-8BEN (Lines 9 and 10) stays blank; Article 14(1) for services performed in the United States is claimed on Form 8233, never Article 7.
- v.o.s. and k.s. A veřejná obchodní společnost (v.o.s.) or komanditní společnost (k.s.) is a partnership-style form, not a Corporation by default. Do not check Corporation only because the business has more than one owner.
An s.r.o. that has not filed Form 8832 checks Corporation on Line 4. An a.s. checks Corporation too, and it cannot elect out.
Do not put a rodné číslo on the company form. A valid personal example is 900101/1239 (9001011239 is divisible by 11). 9001011234 is not. The company identifier is the 8-digit IČO. The sample company uses 12345679. The check digit of 1234567 is 9, not 8. The company tax number DIČ is CZ plus that IČO. Line 9b uses the IČO.
Who actually needs to fill in W-8BEN-E?
Any Czech s.r.o. or a.s. that receives payments from a US business and wants to document non-US status. Common situations:
- Consulting or software invoices A US client asks for the form before paying service fees. For work done in the Czech Republic the form documents that the company is foreign, and Part III stays blank.
- A copyright, a patent, or equipment The payer needs a treaty claim before applying 0% or 10% instead of 30%. The two royalty classes are not the same rate.
- A broker or platform Czech investors meet Form W-8BEN at Interactive Brokers, XTB, Degiro, and Trading 212. Those platforms collect the form. They do not calculate the treaty rate for you. Form W-8BEN-E is the company form, for an s.r.o. or a.s. billing US clients, not for a personal brokerage account.
What happens without a valid form?
Without a W-8BEN-E, a US payer withholds 30% of the gross amount of US-source FDAP income (dividends, interest, royalties, and pay for services performed in the United States), even when the treaty would reduce that rate. Fees for work the s.r.o. does in the Czech Republic are not US-source and have no chapter 3 withholding, though the payer may hold the payment until a form is on file. Services performed in the United States with no US permanent establishment can be 0% under Article 7(1). Ordinary interest is 0% under Article 11(1). A copyright or film royalty is 0% under Article 12(2). A patent, know-how, or equipment royalty is 10% under Article 12(2). A lease of containers used in international traffic is 0% under Article 8(3). Ordinary dividends are still 15% under Article 10(2)(b) unless the company owns at least 10% of the voting shares. Some platforms hold the payment until a valid form is on file.
The form stays with the US payer. It is not filed with the Czech tax authority or the IRS. Czech tax on the same income is a separate question.
W-8BEN-E line by line: what a Czech s.r.o. actually enters
Official IRS line numbers for an operating s.r.o., Active NFFE. For work done in the Czech Republic, Part III (Lines 14a, 14b and 15) stays blank. The Lines 14a, 14b and 15 rows below are the claim case of the sample: services performed on site in the United States with no US permanent establishment. An a.s. uses the same lines except that it cannot elect out of Corporation. An OSVČ does not use this form.
| Line | What you enter |
|---|---|
| Line 1 | The company's legal name, for example Bohemia s.r.o. |
| Line 2 | Country of incorporation: Czechia. The treaty itself is titled Czech Republic. |
| Line 3 | Leave blank unless a disregarded entity is receiving the payment for its owner. |
| Line 4 | Corporation for an a.s. (always) or an s.r.o. (the default, unless Form 8832 says otherwise). The hybrid follow-up is usually No. |
| Line 5 | Chapter 4 (FATCA) status. An operating company with no financial business is usually Active NFFE. |
| Line 6 | The registered office. The sample uses Vaclavske namesti 1, Praha, 110 00. |
| Line 7 | Only if the mailing address differs from Line 6. |
| Line 8 | Usually blank. A US TIN is required only in the cases the payer names. |
| Line 9a | Leave blank. A GIIN is for financial institutions. |
| Line 9b | The company's IČO, 8 digits, as the foreign TIN. The sample is 12345679. Do not enter a rodné číslo and do not enter 12345678. |
| Line 9c | Not checked for a registered company that has an IČO. |
| Line 10 | Usually blank unless the payer asks for a reference number. |
| Part II (Lines 11–13) | Not completed for an ordinary s.r.o. Part II is for disregarded entities and branches. |
| Line 14a | Only when the company claims the treaty: country of residence for treaty purposes, Czechia. Leave Part III blank for work done in the Czech Republic. |
| Line 14b | Only when the company claims the treaty: the Limitation on Benefits test. Article 17 is the LOB article. An operating s.r.o. certifies Active trade or business under Article 17(1)(c). A company wholly owned, directly or indirectly, by a Czech resident in whose principal class of shares there is substantial and regular trading on a recognized securities exchange checks Subsidiary of a publicly traded corporation (Article 17(1)(d)). "No LOB article in treaty" is the wrong box. |
| Line 14c | Not normally checked. |
| Line 15 | Only when the company claims the treaty. For services performed in the United States with no US permanent establishment (staff there not more than 9 months within any 12 month period, or less than 30 days in the taxable year, Article 5(3)(b)): Article 7(1), 0%, Services, explained as "Enterprise lacking a permanent establishment in the US." For a copyright, a film, or a software copyright license: Article 12(2), 0%, Royalties. For a patent, know-how, or equipment rental: Article 12(2), 10%, Royalties. Cite Article 12(2), not Article 12(3). Equipment is a royalty, not Article 7. A lease of containers used in international traffic is not that royalty: Article 8(3), 0%, Container Rental. For a rental of ships or aircraft on a full (time or voyage) basis, or on a bareboat basis by an enterprise engaged in the operation of ships or aircraft in international traffic if that rental is incidental to that operation: Article 8(1), 0%, Ship/Aircraft Rental, explained as "Rental of ships or aircraft within Article 8(2)." Article 8(2) makes such profits operating profits, and Article 8(1) is the paragraph that makes them taxable only in the Czech Republic. The wizard writes no line for this rental, so type these fields by hand. |
| Line 39 (Part XXV) | Check the Active NFFE certification if Line 5 is Active NFFE. |
| Part XXX | Signature, printed name, and date. The sample is signed by Petr Novak. |
Line numbers match Rev. October 2021. If the IRS issues a new revision, follow the numbering on the PDF you sign.
The guided W-8BEN-E wizard fills these lines from your answers, including the article and rate on Line 15. A rental of ships or aircraft under Article 8(2) is the exception: the wizard writes no line for it, and you type Article 8(1), 0% by hand.
An a.s., an s.r.o., and an OSVČ are not the same box
The per se list names only the akciová společnost. An s.r.o. is still a Corporation by default, and an OSVČ is not a company at all.
| Point | What it means |
|---|---|
| Akciová společnost (a.s.) | Per se corporation under 26 CFR 301.7701-2(b)(8)(i), listed as "Czech Republic, Akciova Spolecnost". Check Corporation. Form 8832 cannot change that. |
| s.r.o. | Not on the per se list. Limited liability means the default is still Corporation. A different US classification requires a filed Form 8832. |
| OSVČ | Individual registration. File Form W-8BEN. Work done in the Czech Republic needs no claim: Part II (Lines 9 and 10) stays blank. Article 14(1) for independent services performed in the United States is claimed on Form 8233, never Article 7 and never Article 14(2). |
| IČO vs rodné číslo | Line 9b on this form is the IČO 12345679. The rodné číslo 900101/1239 belongs on Form W-8BEN. |
Use the default that matches the company you actually registered, unless a Form 8832 election is already on file.
What a completed W-8BEN-E looks like for a Czech s.r.o.
An anonymised example of the claim case: Bohemia s.r.o., Active NFFE, whose staff perform services on site in the United States with no US permanent establishment, claiming Article 7(1) at 0% on those fees and certifying Active trade or business on Line 14b. Fees for work done in the Czech Republic would leave Part III blank. This is the PDF the wizard produces from the same inputs.
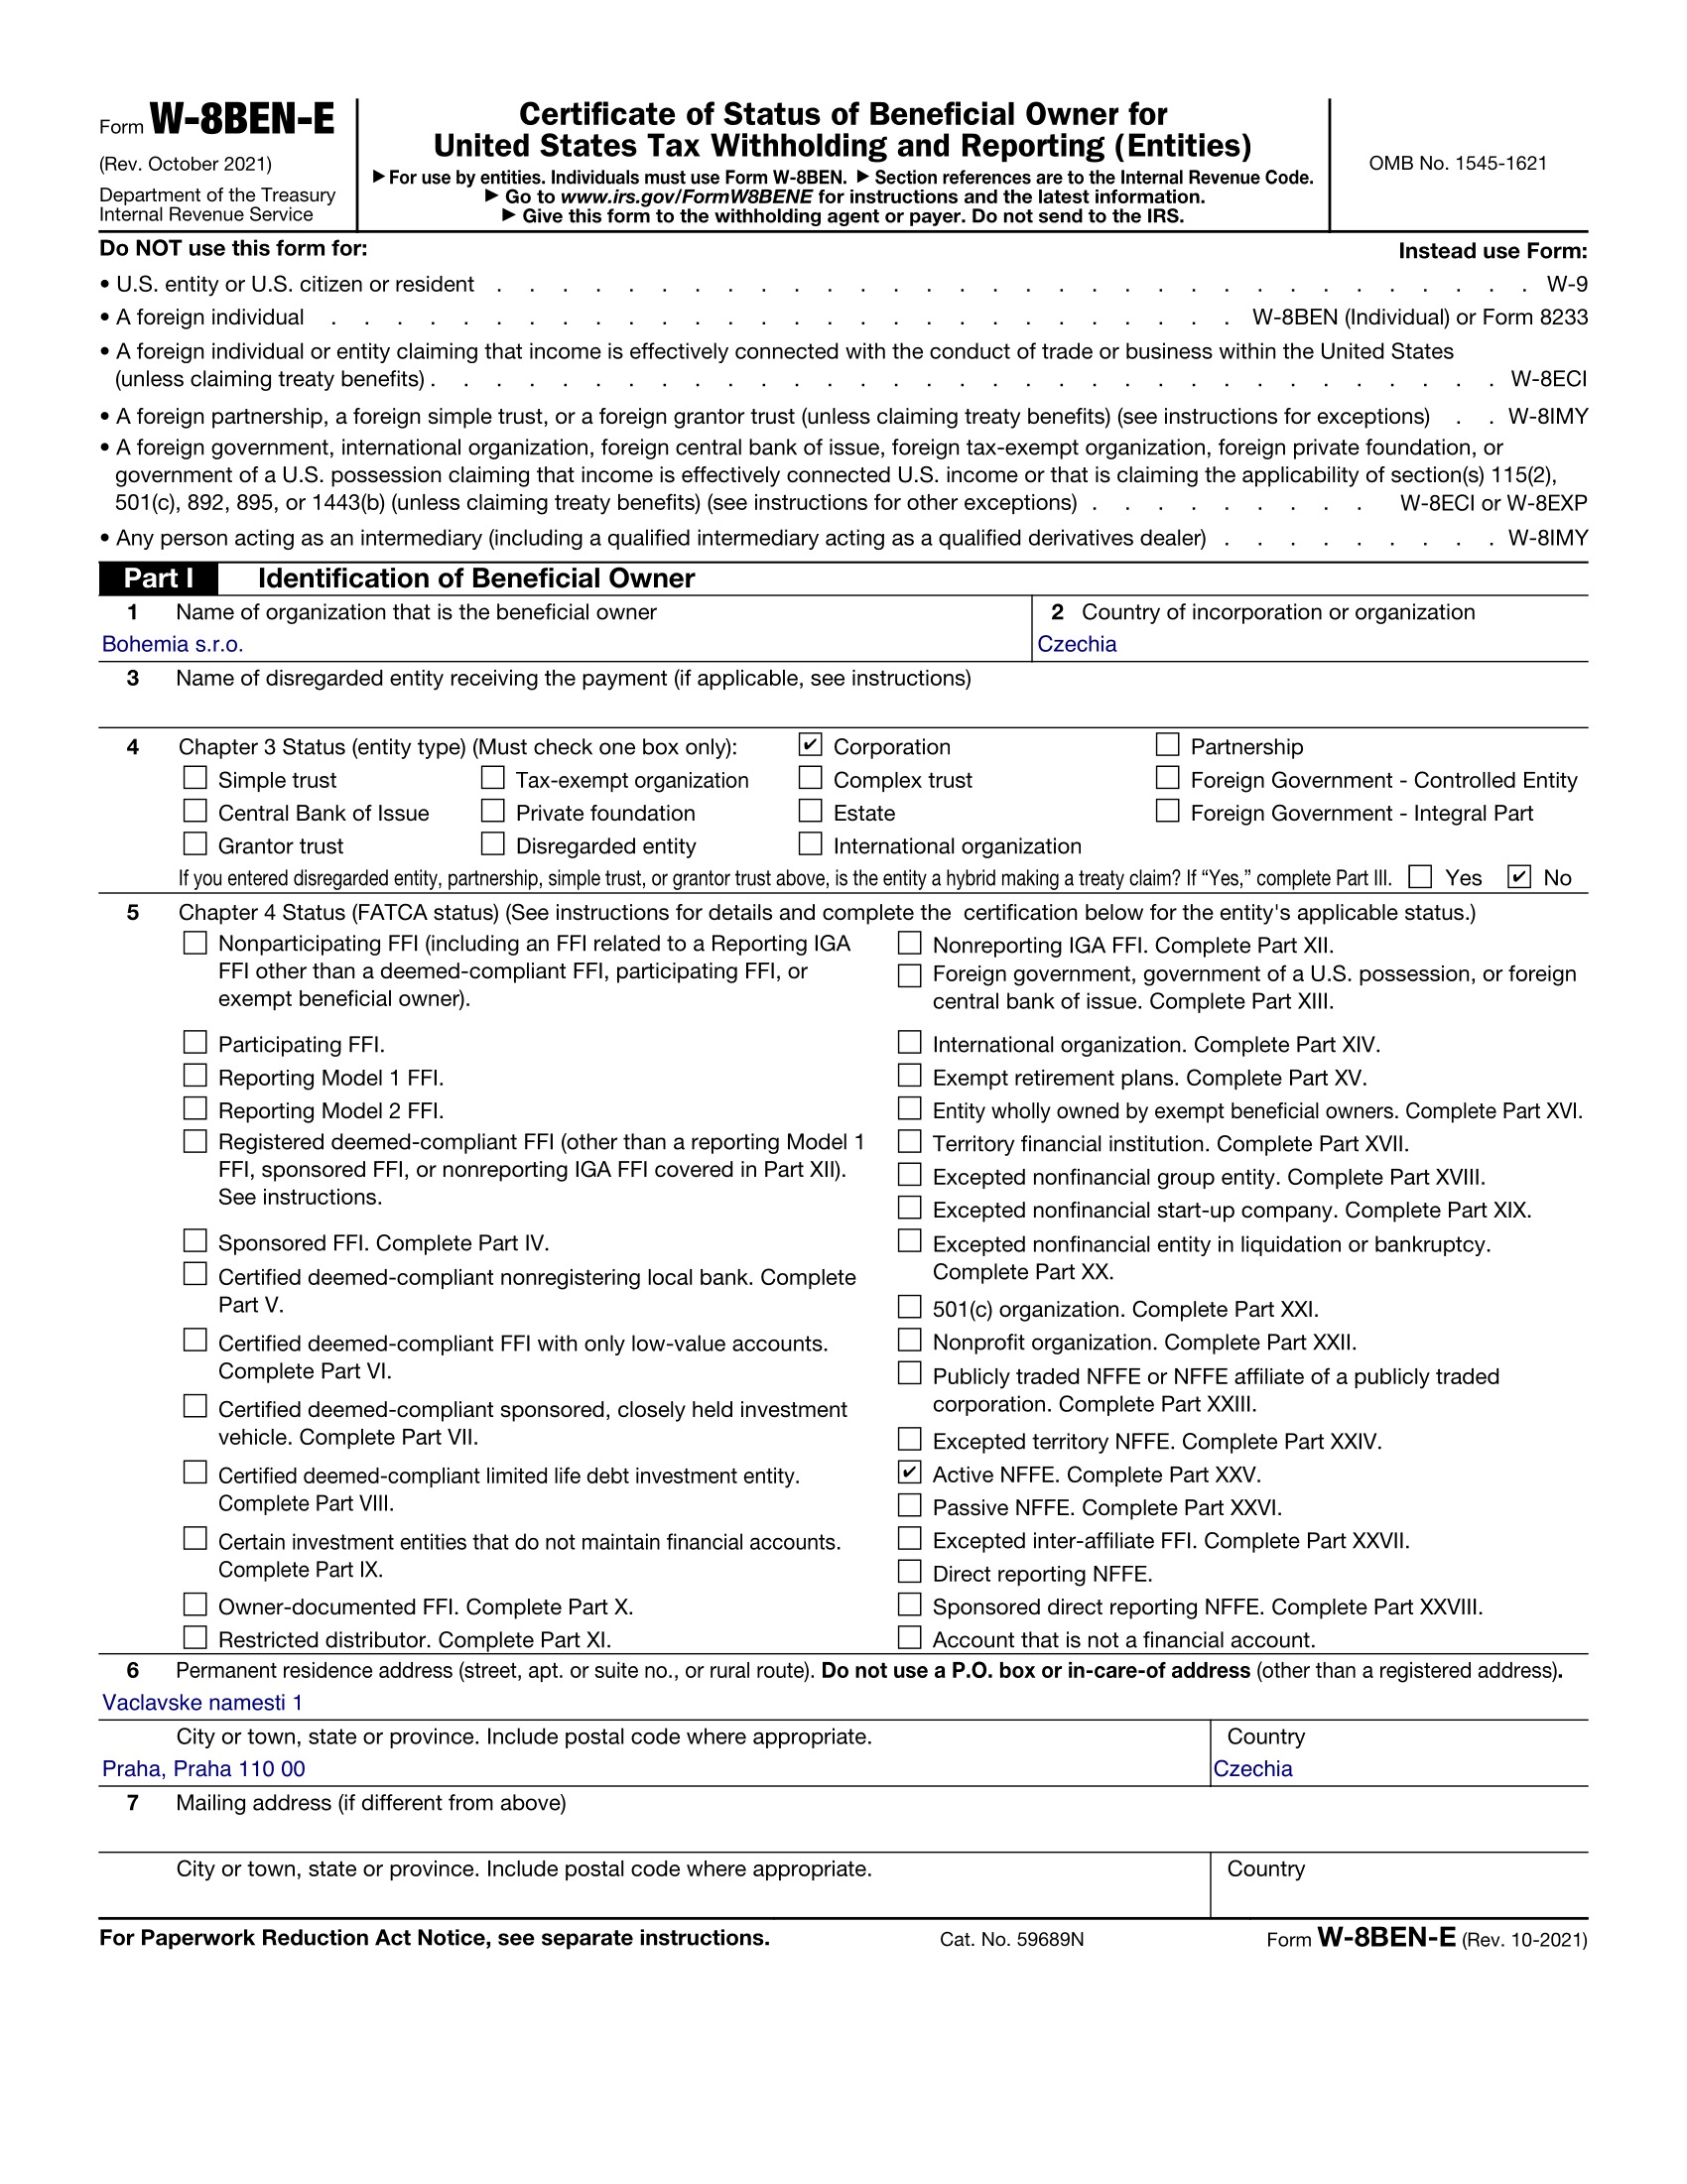
For illustration only. The company name, address, signer, and IČO are fictional. Example: Bohemia s.r.o., Praha, IČO 12345679, Chapter 3 Corporation, FATCA Active NFFE, services performed in the United States with no US permanent establishment, US-Czech Republic treaty Article 7(1) (Business Profits) 0%, Limitation on Benefits Active trade or business.
Treaty rates by income type
These rates come from the 1993 Convention (czech.pdf). They apply only to US-source income: fees for work done in the Czech Republic need no claim, and Part III (Lines 14a, 14b and 15) stays blank. Copyright royalties and industrial royalties are different sentences of the same paragraph.
| Income type | Article | Rate |
|---|---|---|
| Services / consulting performed in the Czech Republic (not US-source income: no US withholding, Part III blank) | None | No claim |
| Services / consulting performed in the United States (Business Profits, no current or former US permanent establishment, staff there not more than 9 months within any 12 month period or less than 30 days in the taxable year) | Article 7(1) | 0% |
| Dividends, company owning at least 10% of the voting shares | Article 10(2)(a) | 5% |
| Dividends, general rate (under 10% of the voting shares, or any holder who does not meet 10(2)(a)) | Article 10(2)(b) | 15% |
| Interest, ordinary cash loan (not a REMIC excess inclusion) | Article 11(1) | 0% |
| Royalties, copyrights, films, and a software copyright license | Article 12(2) | 0% |
| Royalties, patents, trademarks, know-how, and industrial, commercial, or scientific equipment | Article 12(2) | 10% |
| Use, maintenance, or rental of containers (including trailers, barges, and related equipment for the transport of containers) used in international traffic | Article 8(3) | 0%: taxable only in the Czech Republic |
| Rental of ships or aircraft on a full (time or voyage) basis, or on a bareboat basis by an enterprise engaged in the operation of ships or aircraft in international traffic if that rental is incidental to that operation | Article 8(1), read with Article 8(2) | 0%: taxable only in the Czech Republic |
| Independent personal services an individual performs in the United States, with no US fixed base and not present more than 183 days in any twelve month period (claimed on Form 8233, not Form W-8BEN) | Article 14(1) | 0% |
On Line 15, cite Article 12(2) for both royalty classes. Do not cite Article 12(3) as the rate paragraph. Article 12(2) has two sentences. The first sentence covers Article 12(3)(a): copyrights of a literary, artistic, or scientific work, including cinematographic films and films or tapes. That class is taxable only in the residence state, so the rate is 0%. The second sentence covers Article 12(3)(b): patents, trademarks, designs, models, plans, secret formulas or processes, industrial, commercial, or scientific equipment, and know-how. That class may be taxed at source at up to 10%. The convention does not say "computer software". A copyright license of software is the 0% class. A patent, know-how, or equipment rental is the 10% class. EQUIPMENT rental is a royalty, with one exception written in Article 8. Under Article 8(3), profits from the use, maintenance, or rental of containers (including trailers, barges, and related equipment for the transport of containers) used in international traffic are taxable only in the Czech Republic, so that lease goes on Line 15 as Article 8(3), 0%, Container Rental. Under Article 8(2), profits from a rental of ships or aircraft on a full (time or voyage) basis, or on a bareboat basis by an enterprise engaged in the operation of ships or aircraft in international traffic if that rental is incidental to that operation, are profits from that operation, taxable only in the Czech Republic under Article 8(1). Do not send it to Article 7, and do not copy Finland or Denmark, whose Article 7(7) names the rental of tangible personal property in the business-profits definition. A film is the copyright class at 0%, not the industrial 10%. Do not describe royalties as a flat 10% for every category. Ordinary interest cites Article 11(1) at 0%. Article 11(3) is the definition. Article 11(2) lets the United States tax a REMIC excess inclusion under domestic law. Do not cite Article 11(2) for an ordinary cash loan, and do not say interest has no exceptions. There is no contingent-interest 15% paragraph in this article. Dividends: Article 10(2)(a) is 5% when the beneficial owner is a company which owns at least 10% of the voting shares. The text says "owns", not "owns directly", and it does not require 12 months or a minimum Czech corporate tax rate. Article 10(2)(b) is 15% in all other cases. There is no 0% dividend exemption. A Wise.com/cz claim of a full dividend exemption is not this treaty. Article 10(3) is the RIC/REIT rule, not a 0% rate: the 5% of Article 10(2)(a) never applies to a dividend from a US Regulated Investment Company or Real Estate Investment Trust. A RIC dividend is 15% under Article 10(2)(b). A REIT dividend is 15% only when the beneficial owner is an individual holding less than 10% of the REIT; for an s.r.o. or an a.s. US withholding stays at 30%, and the claim stays blank. Do not cite Article 10(6) for a company with no US permanent establishment: that paragraph is a 5% branch-profits tax.
An OSVČ files Form W-8BEN; Article 14(1) for services in the United States goes on Form 8233
Article 14(1) taxes independent personal services only in the residence state unless the services are performed or were performed in the other state and either (a) the income is attributable to a fixed base regularly available there, or (b) the individual is present for a period or periods exceeding in the aggregate 183 days in any twelve month period. Either (a) or (b) is enough, but only together with that performance condition. The day-count is exceeding 183 days, not at least 183. Article 14(2) only defines personal services. Work an OSVČ does from the Czech Republic is not US-source income: there is no US withholding on it, and Part II of Form W-8BEN (Lines 9 and 10) stays blank. Under the IRS instructions for Form W-8BEN, pay for independent personal services performed in the United States is claimed on Form 8233, not on Form W-8BEN. That claim cites Article 14(1), not bare Article 14 and not Article 14(2). An s.r.o. does not cite Article 14. The employment day-count is in Article 15(2)(a), and all three wage conditions must be met.
A blog post, or the finished PDF?
Generic guides often call every Czech royalty 10%, or they copy a 0% dividend exemption onto this treaty. The wizard asks those questions once and returns the PDF.
| Point | This page | A generic guide |
|---|---|---|
| Article numbers | No claim and Part III (lines 14a, 14b and 15) blank for work done in the Czech Republic, Article 7(1) for services performed in the United States, Article 12(2) at 0% for copyrights and films, Article 12(2) at 10% for patents, know-how, and equipment, Article 8(3) at 0% for a lease of containers used in international traffic, Article 14(1) on Form 8233 for a freelancer's US services. | Often cites a flat 10% for every royalty, or sends equipment to Article 7. |
| Line 14b | Active trade or business under Article 17(1)(c), only when the company claims the treaty. | Sometimes checks Article 16, which is directors' fees, or says there is no LOB article. |
| Finished form | Sample PDF for Bohemia s.r.o., for services performed on site in the United States with no US permanent establishment (work done in the Czech Republic leaves Part III, Lines 14a, 14b and 15, blank), plus a wizard that fills yours. | A checklist you still have to type into the IRS PDF. |
Start the wizard and download the filled PDF.
Frequently asked questions about W-8BEN-E for Czech companies
Direct answers for an s.r.o. or a.s. billing US clients or receiving US investment income.
Which article do I cite for consulting fees?
None, when the work is done in the Czech Republic: those fees are not US-source income, there is no US withholding, and Part III stays blank. For services the s.r.o.'s staff perform in the United States: Article 7(1), at 0% if the s.r.o. has no current and no former permanent establishment there. The text says "carries on or has carried on". Article 5(3)(b) makes services furnished through employees or other personnel for more than 9 months within any 12 month period, for the same or a connected project, a permanent establishment, except in a taxable year in which they last less than 30 days. Do not cite Article 12 or Article 14 for the company.
I am an OSVČ, not an s.r.o. Which form and which article?
Form W-8BEN. Work you do in the Czech Republic is not US-source income, so Part II (Lines 9 and 10) stays blank. For services you perform in the United States, the IRS takes the treaty claim on Form 8233, not on Form W-8BEN. That claim is Article 14(1): the United States may tax only if the services are performed or were performed there and either the income is attributable to a fixed base regularly available to you there or you are present there for more than 183 days in the aggregate in any twelve month period. Do not cite Article 7 or Article 14(2).
Are royalties a flat 10%?
No. Article 12(2) has two sentences. Copyrights, films, and a software copyright license are 0%. Patents, trademarks, know-how, and equipment are 10%. A lease of containers used in international traffic is Article 8(3) at 0%, not this royalty. Cite Article 12(2) for both. Do not cite Article 12(3) as the rate paragraph.
Is a film royalty 10%?
No. A cinematographic film is in the copyright class, Article 12(3)(a), taxable only in the residence state. Cite Article 12(2) at 0%. The 10% sentence is the industrial class.
Is equipment rental a royalty?
Yes. Article 12(3)(b) includes industrial, commercial, or scientific equipment. Cite Article 12(2) at 10%. Do not cite Article 7. Article 7(7) does not put equipment rental in business profits. A lease of containers used in international traffic is different: Article 8(3) makes those profits taxable only in the Czech Republic, so cite Article 8(3) at 0%. Article 8(2) with Article 8(1) does the same for a rental of ships or aircraft on a full (time or voyage) basis, and for a rental on a bareboat basis by an enterprise engaged in the operation of ships or aircraft in international traffic if that rental is incidental to that operation.
Is interest really 0% with no exceptions?
Ordinary interest is Article 11(1) at 0%. That is not every interest payment. Article 11(2) lets the United States tax a REMIC excess inclusion under domestic law. Do not cite Article 11(2) for an ordinary cash loan. There is no contingent-interest 15% paragraph in this article.
What do I check on Line 14b?
Only when the company claims the treaty; for work done in the Czech Republic Part III stays blank. An operating s.r.o. checks Active trade or business, Article 17(1)(c), when the US income is derived in connection with, or is incidental to, its trade or business in the Czech Republic (other than making or managing investments, unless these are banking or insurance activities carried on by a bank or insurance company). A company wholly owned, directly or indirectly, by a Czech resident in whose principal class of shares there is substantial and regular trading on a recognized securities exchange checks Subsidiary of a publicly traded corporation, Article 17(1)(d). Article 17(1)(f) is the ownership-and-base-erosion test, not the default for an operating s.r.o. Article 16 is directors' fees. "No LOB article in treaty" does not apply.
Why is the dividend rate 15%, not 0%?
Article 10(2)(b) is 15% when the holder does not own at least 10% of the voting shares. Article 10(2)(a) is 5% when a company owns at least 10% of the voting shares. The verb is "owns", not "owns directly". There is no 0% dividend tier. Article 10(3) is RIC and REIT, not a 0% rate: a RIC dividend is 15%, and a REIT dividend to a company stays at 30%. A Wise.com/cz full-exemption claim is not this treaty.
a.s. or s.r.o. on Line 4?
Both check Corporation unless the s.r.o. has filed Form 8832. Only "Czech Republic, Akciova Spolecnost" is on the per se list. The s.r.o. is a Corporation by default because of limited liability.
Rodné číslo or IČO on Line 9b?
The company's IČO. The sample uses 12345679. The check digit of 1234567 is 9, not 8. A rodné číslo belongs on Form W-8BEN. The valid personal example is 900101/1239. 9001011234 fails the check.
Related guides
More on the form itself:
- Company form: W-8BEN-E wizard for an s.r.o. or a.s.
- Not a company: W-8BEN wizard for an individual ($5)
- Chapter 3 status: Chapter 3 status guide
Common mistakes to avoid
- Filling Part III for work done in Czechia Fees for services performed in the Czech Republic are not US-source income. Leave Lines 14a, 14b and 15 blank. Article 7(1), 0% is for services performed in the United States with no US permanent establishment.
- Putting a rodné číslo on the company form Line 9b is the IČO 12345679. A rodné číslo such as 900101/1239 belongs on Form W-8BEN.
- Calling every royalty 10% Copyrights, films, and a software copyright license are Article 12(2) at 0%. Patents, know-how, and equipment are Article 12(2) at 10%.
- Sending equipment to Article 7 Equipment rental is a royalty under Article 12(3)(b). Cite Article 12(2) at 10%. A lease of containers used in international traffic is Article 8(3) at 0%, not this royalty.
- Citing a 0% dividend exemption There is no 0% dividend tier. The general rate is Article 10(2)(b) at 15%. Article 10(3) is RIC and REIT.
- Checking No LOB article Article 17 is a real Limitation on Benefits article. With a treaty claim, an operating s.r.o. certifies Active trade or business under 17(1)(c).
- Putting an OSVČ's Article 14(1) claim on Form W-8BEN Work done from the Czech Republic needs no claim: Part II of Form W-8BEN (Lines 9 and 10) stays blank. Services performed in the United States are claimed under Article 14(1) on Form 8233, not under bare Article 14 or Article 14(2). The day-count is exceeding 183 days.
- Using 12345678 or 9001011234 The IČO check digit of 1234567 is 9. The rodné číslo 9001011234 is not divisible by 11. Use 12345679 and 900101/1239.
A note on Czech tax
This page is about US withholding. It does not determine how the Czech Republic taxes the same income, and it does not calculate Czech tax on US dividends.
Company tax, VAT, and whether a dividend meets the 10% voting-share test are questions for a Czech accountant. The W-8BEN-E only tells the US payer which treaty rate to apply at source.
Ready to fill the form with the Czech article numbers?
The wizard asks the same questions as this page and suggests the article and rate on Line 15. A rental of ships or aircraft under Article 8(2) is the exception: the wizard writes no line for it, and you type Article 8(1), 0% by hand.