W-8BEN-E for a Croatian d.o.o.: the US-Croatia treaty is signed, not in force
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Last checked September 28, 2026, against the IRS "United States Income Tax Treaties - A to Z" list. Croatia is not on that list. A convention was signed on December 7, 2022, and an amending protocol on April 28, 2026. Croatia's government approved a ratification bill on July 30, 2026. The US Senate has not given advice and consent, and the instruments of ratification have not been exchanged, so the treaty has not entered into force. This page does not quote article numbers or rates from that signed text. When the IRS lists the treaty as in force, this page and the wizard will be rewritten for the rates that then apply.
 AI-generated image
You may have read that Croatia now has a tax treaty with the US. It is signed — but until it enters into force, Part III of your W-8BEN-E stays blank. There is no article to name and no reduced rate to claim today.
This guide is for a Croatian d.o.o. or j.d.o.o. that invoices US clients or holds a US brokerage account. It covers what you file now, which company form is a per se corporation, which number goes on Line 9b, and what will change only after both countries finish ratification. A sample PDF is included further down.
If you are self-employed — an obrt, including a paušalni obrt — you file Form W-8BEN, not this one: start the W-8BEN wizard. The OIB is the same 11-digit number a company uses. Do not type the HR prefix. That prefix belongs to the VAT number.
If you prefer to skip the reading, you can start the W-8BEN-E wizard now. It already knows the US-Croatia treaty is not in force and, by default, leaves Part III (Lines 14–15) blank. In a few minutes you have a signature-ready PDF for $30.
Blank form or already filled in?
You can download the official, blank form from the IRS and complete it yourself — or get the same file already filled in by our wizard.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for a d.o.o., a j.d.o.o., or a d.d.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for an obrt, including a paušalni obrt.
- Already filled in (5–10 minutes): W-8BEN-E for Croatian companies ($30) or W-8BEN for individuals ($5) — the wizard leaves Part III blank while the treaty is not in force.
- IRS treaty list: United States Income Tax Treaties - A to Z — Croatia does not appear on this list.
Signed, approved in Zagreb, not yet in force
A signature is not entry into force. Croatia also did not inherit an in-force US income tax treaty from the former Yugoslavia.
- December 7, 2022: The United States and Croatia signed an income tax convention.
- April 28, 2026: An amending protocol was signed.
- July 30, 2026: Croatia's government approved a bill to ratify the convention and the protocol.
- Still outstanding: The US Senate has not given advice and consent, and the countries have not exchanged instruments of ratification.
- Entry into force, then the application date: Benefits start only after entry into force, and only from the effective date the treaty itself specifies. Until the IRS lists Croatia, Part III stays blank. This page will be updated when that happens.
d.o.o., j.d.o.o., d.d., or an obrt?
Croatian company law uses more than one limited company, and US tax classification does not follow the local abbreviation one-for-one:
- Dioničko društvo (d.d.): 26 CFR 301.7701-2(b)(8)(i) lists "Croatia, Dionicko Drustvo" as a per se corporation. Notice 2013-44 applies that rule to a d.d. formed on or after July 1, 2013, and such a company cannot file Form 8832. For a d.d. formed before that date, per se status begins only on a later date when persons who were not owners on July 1, 2013 together hold 50% or more of the equity, by vote or by value. A redistribution among people who already owned the d.d. on July 1, 2013 does not put it on the per se list, and Form 8832 stays available.
- Društvo s ograničenom odgovornošću (d.o.o.): The usual private company. It is not on the per se list. It defaults to Corporation because its members have limited liability, and a different US classification is made on Form 8832. A single-member d.o.o. is not disregarded by default.
- Jednostavno društvo s ograničenom odgovornošću (j.d.o.o.): The simple limited-liability company. It is also not on the per se list. It defaults to Corporation for the same reason, and Form 8832 is how a different classification is made.
- Javno trgovačko društvo (j.t.d.) or komanditno društvo (k.d.): These default to Partnership when at least one partner has unlimited liability, under 26 CFR 301.7701-3(b)(2). Check Partnership in Part I, line 4, not Corporation.
- Obrt, including a paušalni obrt: A sole trader, not a company. That person files Form W-8BEN, not W-8BEN-E.
The trap worth naming: a d.d. on the per se list is not the same as a d.o.o. The d.o.o. stays eligible for Form 8832. The absence of a treaty in force does not change that classification.
Chapter 3 still decides which form you file. Part III is where a treaty article would go, and today that part stays blank.
Who actually needs to submit this form?
Any Croatian d.o.o., j.d.o.o., or d.d. that receives payments from a US business and needs to document that it is not a US person. What you can claim in Part III does not depend on the signed text:
- Services performed in Croatia: Foreign-source income. US withholding does not apply, treaty or no treaty. The form documents foreign status so the payer does not withhold by mistake.
- A US dividend, US-source interest, or a royalty for IP used in the US: The statutory 30% applies until the treaty enters into force. Do not type an article or a reduced rate from articles about the signed convention.
- An obrt: Not this form. A paušalni obrt files Form W-8BEN.
What to put on the form today
Part III (Lines 14–15) stays blank. Do not enter an article number or a rate from the signed-but-not-in-force convention or its protocol. Part II (Lines 11–13) is a different section — disregarded entity or branch — and also stays blank for an ordinary d.o.o.
Income from services performed outside the United States, the common case for a d.o.o., j.d.o.o., or obrt invoicing a US client from Croatia, is foreign-source and is not subject to US withholding at all. Genuine US-source income is different: dividends on US stock, interest on US instruments, and royalties for IP used in the United States stay at the full 30% statutory rate until the treaty takes effect. The portfolio interest exemption (IRC section 871(h)/881(c)) is a separate non-treaty rule. Ask an accountant. Do not treat it as automatic.
What changes only after the treaty is in force
Nothing on this form changes because a text has been signed or because Zagreb has approved a bill. The practical difference is the date the treaty later specifies:
| Income type | Today | After entry into force |
|---|---|---|
| Services performed in Croatia | 0% US withholding, because the income is not US-source | Still not US-source. The form may then add a treaty statement only if the in-force text covers that income. |
| Dividends on US stock | 30%. No treaty article. | A reduced rate may become available from the application date. Do not guess it from the signed text. This page will be updated. |
| Interest and royalties that are US-source | 30%, unless a separate non-treaty exemption applies. | The in-force text will set the rate. Until then, leave Line 15 blank. |
From the application date you will be able to update the W-8BEN-E and claim the benefits the treaty then provides. We will update this page and the wizard at the same time. Until that date, copying a rate from a summary of the signed convention is the mistake to avoid.
Form W-8BEN-E, line by line, for a Croatian d.o.o.
The line numbers below match the current form (Rev. October 2021) for an operating d.o.o., Active NFFE, with no treaty claim. A fund or a financial institution follows different rules on some lines.
| Line | What you enter |
|---|---|
| Line 1 | The legal name exactly as registered (e.g., "Adriatic Code d.o.o."). |
| Line 2 | Country of incorporation: Croatia. |
| Line 3 | Leave blank unless a single-member d.o.o. has filed Form 8832 to elect disregarded status. That is not the default. A per se d.d. cannot make that election. |
| Line 4 | "Corporation" for a d.o.o. or j.d.o.o. (the default) and for a per se d.d. "Partnership" for a j.t.d. or k.d. An obrt does not use this form. |
| Line 5 | Chapter 4 (FATCA) status — almost always "Active NFFE" for an ordinary trading or services company. |
| Line 6 | The registered office in Croatia, in Latin letters (e.g., Ilica 25, Zagreb, City of Zagreb, 10000). |
| Line 7 | Leave blank if it matches line 6. |
| Line 8 | Leave blank unless the company has actually received a US EIN. |
| Line 9a | Leave blank unless the entity is itself a Foreign Financial Institution. |
| Line 9b | The OIB, 11 digits, for example 12345678903. The same format is used for a company and for a person. Do not type the HR prefix. HR plus the OIB is the VAT number. 12345678901 fails the check digit. |
| Line 9c | In practice this is not checked for a registered d.o.o. — the tax authority already issued the OIB. |
| Line 10 | Leave blank unless the withholding agent specifically asked for a reference number. |
| Part II (Lines 11-13) | Not completed for an ordinary d.o.o. This part is only for a disregarded entity or a branch receiving the payment. Do not confuse it with the treaty claim. |
| Line 14a | LEAVE BLANK. There is no US-Croatia income tax treaty in force, so there is no treaty country to cite. |
| Line 14b | LEAVE BLANK. Without a treaty in force there is no Limitation on Benefits test to certify. |
| Line 15 | LEAVE BLANK. Do not enter an article or a rate from the signed convention. Those figures are not available until the treaty enters into force. |
| Line 39 (Part XXV) | Check the "Active NFFE" certification, matching Line 5. |
| Part XXX | Signed by a director or other authorized person, with capacity stated. |
This reflects the Rev. October 2021 revision of Form W-8BEN-E. Cross-check the current IRS PDF before you submit.
Every field in the table above is filled in by our guided W-8BEN-E wizard — including the decision to leave Part III (Lines 14–15) blank.
OIB, without the HR prefix
Croatia uses one personal identification number for a person and for a company. The VAT number is a different string.
| Point | What it means |
|---|---|
| OIB | 11 digits, ISO 7064 Mod 11,10. The sample 12345678903 passes. 12345678901 fails. That number goes on Line 9b of Form W-8BEN-E and on Form W-8BEN. |
| HR prefix | HR plus the OIB is the VAT number. Do not type HR on Line 9b unless the payer asked for a VAT ID. |
| Obrt | A sole trader, including a paušalni obrt, is not a d.o.o. The person files Form W-8BEN and uses the same OIB. |
| d.d. versus d.o.o. | A d.d. formed on or after July 1, 2013 cannot file Form 8832. An older d.d. becomes per se, and loses Form 8832, only when persons who were not owners on July 1, 2013 later hold 50% or more together. A redistribution among persons who already owned the d.d. on July 1, 2013 leaves Form 8832 available. A d.o.o. and a j.d.o.o. default to Corporation and can file Form 8832. |
Read the OIB from the tax record before Line 9b. Do not invent an 11-digit string that fails the check digit.
Sample: completed W-8BEN-E for a Croatian d.o.o.
A filled example for a fictional d.o.o. with no US permanent establishment, Active NFFE status, and Part III left blank because the US-Croatia treaty is not in force.
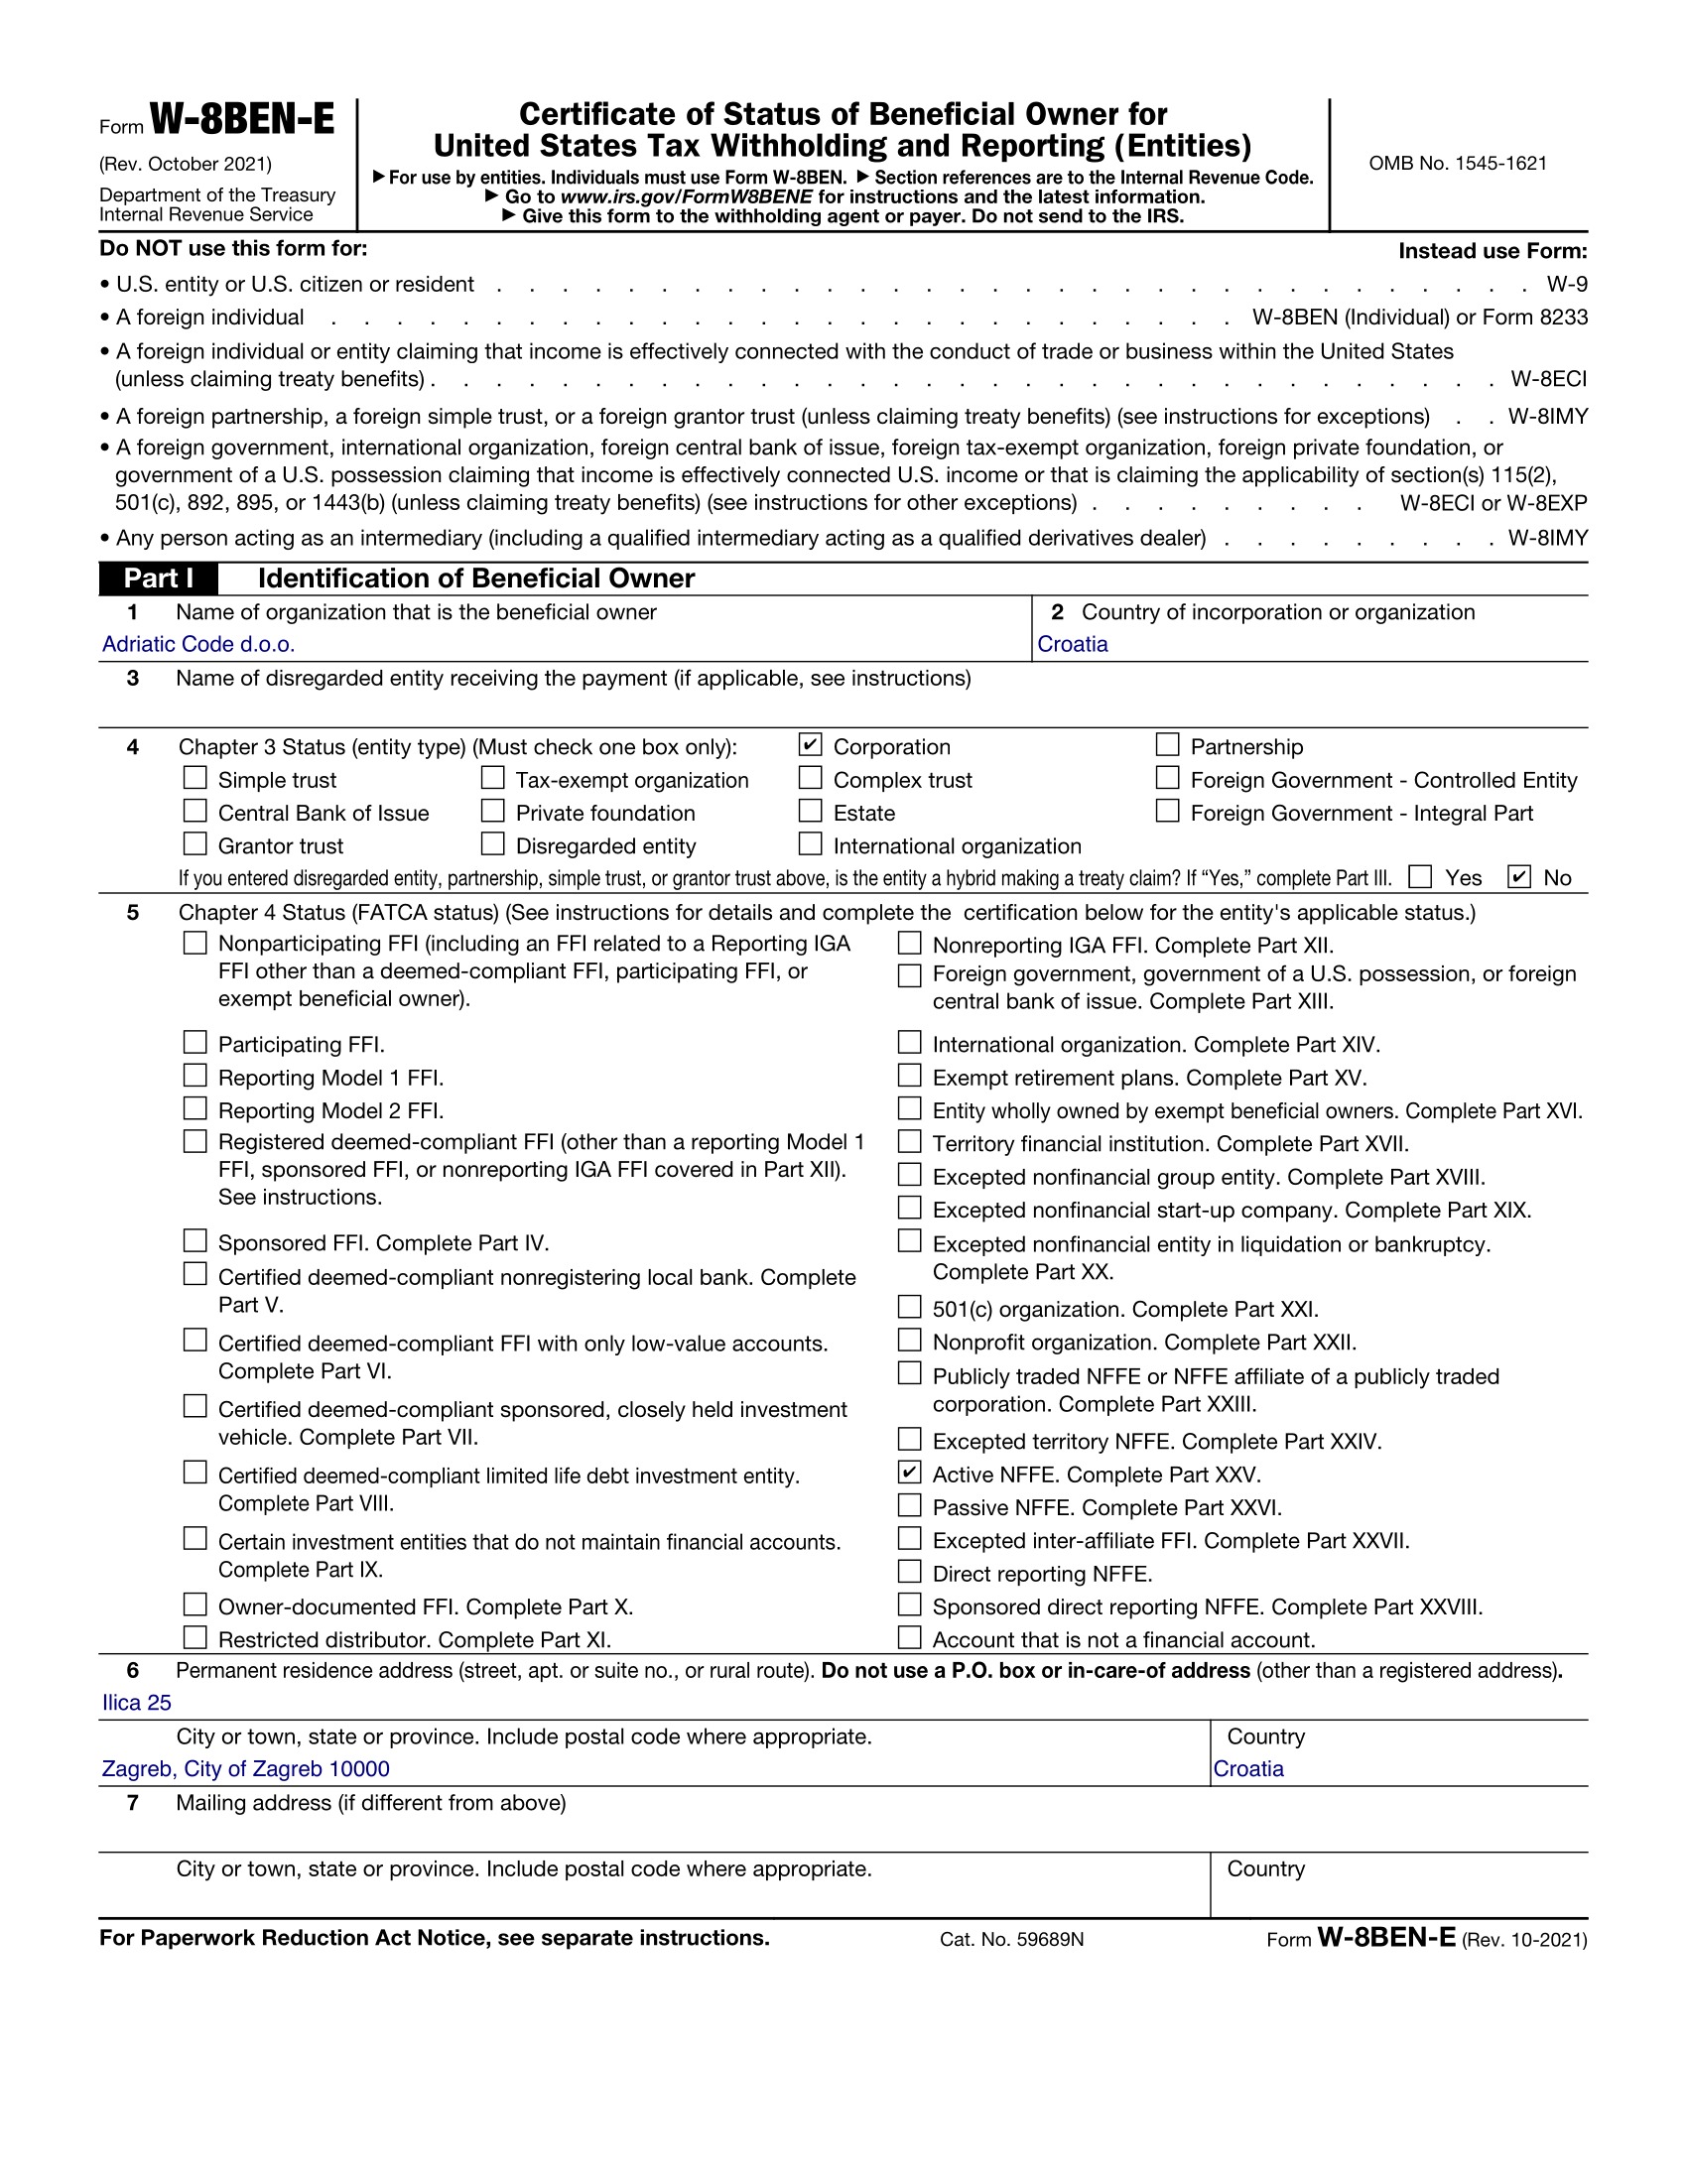
Sample only — uses a fictional company for illustration. Example: Adriatic Code d.o.o., Ilica 25, Zagreb 10000, Croatia, OIB 12345678903, Chapter 3 Corporation, FATCA Active NFFE, Part III blank.
What is withheld today
There is no treaty rate table to copy. What matters is whether the income is US-source.
| Income type | US withholding | Note |
|---|---|---|
| Services performed outside the United States | 0% (foreign-source) | Unchanged by the signature. The form documents foreign status. |
| Dividends on US stock | 30% | No treaty article until the convention enters into force. |
| Interest on most US instruments | 30% | A portfolio interest exemption is a question for an accountant. It is not a treaty benefit and it is not automatic. |
| Royalties for IP used in the US | 30% | Do not cite an article from the signed text. |
Form W-8BEN-E does not create a treaty rate that is not in force. It shows the payer that the company is foreign.
Questions people ask before they sign
Short answers for a d.o.o. A fund or a financial institution needs an accountant, not a blog page.
Can I already claim the treaty rate?
No. The convention and the 2026 protocol are signed, and Croatia's government approved ratification on July 30, 2026, but the treaty has not entered into force. Part III stays blank. Do not copy an article or a rate from descriptions of the signed text.
Will my US client withhold 30% on my invoices?
Not for services performed outside the United States. A d.o.o. that does the work in Croatia is earning foreign-source income. The 30% rate is for genuine US-source income, such as US dividends, US-source interest, and royalties for IP used in the United States.
I'm a paušalni obrt — W-8BEN or W-8BEN-E?
Form W-8BEN. An obrt, including a paušalni obrt, is a sole trader, not a d.o.o. The OIB on that form is the same 11-digit number, without an HR prefix.
When will the treaty apply?
Only after both countries finish ratification and exchange instruments, and then from the effective date the treaty specifies. Check the IRS A-to-Z list. This page and the wizard will be updated when Croatia appears there.
Which number goes on Line 9b?
The OIB, for example 12345678903. 12345678901 fails the check digit. Do not type HR. That prefix is the VAT number, not the TIN.
Can a d.o.o. file Form 8832?
Yes, when it needs a US classification other than Corporation. A d.d. formed on or after July 1, 2013 cannot. A d.d. formed earlier becomes per se, and loses Form 8832, only on a later date when persons who were not owners on July 1, 2013 together hold 50% or more. A redistribution among persons who already owned the d.d. on July 1, 2013 does not do that, and Form 8832 stays available. A single-member d.o.o. is not disregarded by default.
What to do next
- Fill out your W-8BEN-E in the guided wizard: Start the W-8BEN-E wizard ($30). It leaves Part III blank while the treaty is not in force.
- Are you an obrt?: Use the W-8BEN wizard ($5).
Mistakes that get the form sent back
- Filling Part III from the signed convention: Lines 14a, 14b, and 15 stay blank until the treaty enters into force. A signature in 2022 and a protocol in 2026 do not create a rate you can claim today.
- Typing the OIB with an HR prefix: Line 9b takes 11 digits, for example 12345678903. HR plus the OIB is the VAT number.
- Filing W-8BEN-E for an obrt: A paušalni obrt files Form W-8BEN.
- Treating every d.d. like a d.o.o.: A d.d. on the per se list cannot file Form 8832. A d.o.o. and a j.d.o.o. can.