W-8BEN-E for a New Zealand Company: Ltd, Look-Through Company, or Sole Trader — Why Your LTC Is Still a Corporation
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Treaty articles and rates on this page are checked against the 1982 US–New Zealand Convention and the Protocol signed 1 December 2008 — last verified September 2026. The commonly linked IRS PDF (irs.gov/pub/irs-trty/newzld.pdf) is the 1982 text only and does not include those Protocol rates.
 AI-generated image
Your New Zealand Limited Company just invoiced a US client for consulting, software, or agency work — and the client's finance team is now asking for a completed W-8BEN-E before they'll release payment. If that company is a Look-Through Company, the next mistake is almost automatic.
This guide walks through the actual IRS line numbers for that scenario, using the current 2021 revision of the form, shows a filled example, and covers the two points generic guides get wrong: your LTC is still a Corporation on this form, and the treaty rates that apply are the 2008 Protocol figures — not the stale 1982 royalty rate still sitting in the IRS treaty PDF.
If you're not incorporated — a sole trader operating under your own IRD number — the shorter W-8BEN applies instead: start the W-8BEN wizard. This page covers incorporated businesses: Limited Company (Ltd) and Look-Through Company (LTC).
Or skip the reading and start the W-8BEN-E wizard — guided questions, an automatically suggested treaty article and rate (post-2008 Protocol), and a signature-ready PDF for $30.
Blank form or already filled in?
You can download the official, blank form from the IRS and complete it yourself — or get the same file already filled in correctly by our wizard in a few minutes.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for Limited Companies and LTCs.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for sole traders.
- 1982 Convention (base text only): Income Tax Treaty PDF on IRS.gov — do not use its royalty rate on its own.
- 2008 Protocol (the rates that apply today): Protocol signed 1 December 2008 on Treasury.gov.
- Already filled in (5–10 minutes): W-8BEN-E for New Zealand companies ($30) or W-8BEN for sole traders ($5) — treaty article and rate suggested automatically, ready to sign as a PDF.
The mistake almost every LTC owner makes
A Look-Through Company does not pay New Zealand company tax on its own income. That income is taxed in the owners' hands. So when Chapter 3 of Form W-8BEN-E asks for the entity type, the intuitive click is Partnership or Disregarded Entity. That is wrong.
- Sole trader: Not a separate legal entity — you're treated as an individual for US tax purposes. You use the shorter W-8BEN, with your personal IRD number, not W-8BEN-E.
- Limited Company (Ltd): Always a Corporation for US tax purposes, with no exceptions and no Form 8832 election. 26 CFR 301.7701-2(b)(8)(i) lists "New Zealand, Limited Company" — not "Public Limited Company" — as a per se corporation. Public or private does not matter.
- Look-Through Company (LTC): Still a Limited Company under the Companies Act 1993. The pass-through treatment is a New Zealand-only election via IRD Form IR862. It does not exist for US classification. An LTC is still a Corporation on this form.
- Limited Partnership (LP): Registered under the Limited Partnerships Act 2008. It has at least one general partner with unlimited liability, so it defaults to Partnership — this is the form that actually belongs on that checkbox, not an LTC.
US classification follows 26 CFR 301.7701-2 and -3, not how Inland Revenue taxes the income. An LTC remains a "Limited Company" at Companies Office. That name is on the US per se corporation list, so there is no election available at all.
Because New Zealand has a real treaty, this distinction matters: getting the entity type right determines not just which form you file, but which article and rate you can claim in Part III (Lines 14–15).
Who actually needs to fill in W-8BEN-E?
In short, any New Zealand Ltd or LTC that receives payments from a US business and wants to document its non-US tax status. Common situations:
- Invoicing US clients directly: Your company bills a US-based business for consulting, development, design, or other services.
- US payment platforms: Payouts from Stripe, Amazon, YouTube/AdSense, or similar US-headquartered platforms.
- US shares via a broker: Your company holds US securities through a broker. Sharesies and Hatch already ask individuals for a W-8BEN — a company account needs W-8BEN-E instead.
- Royalty or interest income: Your company receives royalty or interest payments from a US source — ordinary interest is generally 10% and IP royalties 5% after the 2008 Protocol; leased equipment is Article 7 / 0%, not a royalty (see rates below).
What happens without a valid form?
Without a submitted W-8BEN-E, the US payer generally withholds 30% of the gross payment under the nonresident-alien presumption rules — not because it treats you as a US person, and even if a lower rate (or 0%) would otherwise apply under the treaty. Services can be 0% with no US permanent establishment; dividends stay 5%/15%; interest is generally 10%; IP royalties are 5% after the 2008 Protocol (not the 10% in the 1982 IRS PDF); leased equipment is Article 7 / 0%, not a royalty. Some US platforms and brokers pause payment entirely until a valid form is on file.
The form is never sent to Inland Revenue or the IRS — it stays with the US payer as their own compliance record. Your company still reports the US income as normal on its New Zealand return; W-8BEN-E only affects US withholding at source.
W-8BEN-E line by line: what a New Zealand Ltd actually enters
Below is the official IRS "Line X" numbering exactly as printed on the current form, for the standard case: an operating Ltd (or LTC), Active NFFE, claiming treaty benefits under the US–New Zealand treaty as amended by the 2008 Protocol. Holding structures and financial institutions follow different rules on some lines — our wizard determines the right answer automatically from your answers.
| Line | What you enter |
|---|---|
| Line 1 | Your company's full legal name exactly as registered with the Companies Office (for example, Kiwi Ventures Ltd.). |
| Line 2 | Country of incorporation: New Zealand. |
| Line 3 | Leave blank — only applies if a disregarded entity is receiving the payment on behalf of its owner. |
| Line 4 | Check "Corporation" for every New Zealand Limited Company, including an LTC. There is no Form 8832 election. A registered Limited Partnership checks "Partnership" instead. The "hybrid entity" follow-up question is usually "No". |
| Line 5 | Chapter 4 (FATCA) status — for a normal operating company with no financial activity, usually "Active NFFE". |
| Line 6 | Your company's actual registered office address (not a virtual mailbox used only for correspondence). |
| Line 7 | Only complete if your mailing address differs from Line 6. |
| Line 8 | Usually blank — a US TIN (EIN) is only required in specific cases your payer will tell you about. |
| Line 9a | Leave blank — a GIIN only applies to financial institutions. |
| Line 9b | Your company's IRD number (8 or 9 digits, often written 99-999-999 or 999-999-999). This is NOT the 13-digit NZBN, which is a public business number, not a tax ID. |
| Line 9c | In practice this is never checked for a registered Ltd — an IRD number is assigned when the company is registered. |
| Line 10 | Usually blank — only completed at the payer's explicit request. |
| Part II (Lines 11–13) | Not completed for a normal Ltd or LTC — only applies to a disregarded entity or a branch. |
| Line 14a | Country of residence for treaty purposes: New Zealand. |
| Line 14b | Limitation on Benefits (LOB) category — Article 16 of the treaty (as replaced by the 2008 Protocol) exists, so "No LOB Article In Treaty" is not valid here. An ordinary trading Ltd typically uses the active-trade-or-business test. |
| Line 14c | Not normally checked — a narrow special case. |
| Line 15 | Treaty article, paragraph, rate, and income type (e.g. "Article 7(1)", 0%, "Services" for service income with no US permanent establishment). Suggested automatically by the wizard. Never cite the pre-2008 10% royalty rate from the 1982 IRS PDF alone. |
| Line 39 (Part XXV) | Check the "Active NFFE" certification, matching Line 5. |
| Part XXX | Signature, printed name, date. Normally signed by a director or other authorised signatory. |
Line numbers match the form currently in force (Rev. October 2021). If the IRS issues a new revision, always defer to the numbering on the actual PDF you download.
Every field in the table above is filled in automatically by our guided W-8BEN-E wizard based on your answers — including the treaty article and rate on Line 15.
The IRD number vs NZBN trap on Line 9b
This is the identifier mistake New Zealand companies make most often — and it is unlike most other countries in this product, because the IRD number is the same length for individuals and companies.
| Point | What it means |
|---|---|
| What each number is | The IRD number (8 or 9 digits) is issued by Inland Revenue to both individuals and companies and is New Zealand's official tax identifier. The NZBN (13 digits) is a public business number — it is not a tax ID and does not go on this form. |
| Why this is confusing | Unlike most countries here, New Zealand's IRD number is the SAME LENGTH for individuals and companies — so an incorrect entry doesn't "look wrong" the way a 10-digit vs 11-digit mix-up would elsewhere. The real question is IRD versus NZBN, not which format to use. |
| What to enter on Line 9b | The company's IRD number. Our sample PDF uses 123-456-789. Do not put the NZBN here. |
| The sole trader trap | A sole trader has an IRD number too, but it does not make them a separate entity — they still file the individual Form W-8BEN, never this form. |
| No Form 8832 angle | A New Zealand Limited Company, including an LTC, cannot elect partnership or disregarded-entity treatment by filing Form 8832. It is per se a Corporation. |
Form 8832 cannot change the Ltd default. If the company is registered as Limited, use Corporation.
What a completed W-8BEN-E looks like for a New Zealand Ltd
An anonymised example: a Limited Company providing software consulting to US clients, Active NFFE, no US permanent establishment, claiming treaty benefits under Article 7(1) — 0% withholding on US service income, using the treaty as amended by the 2008 Protocol. Kiwi Ventures Ltd. could be an ordinary Ltd or an LTC — the W-8BEN-E looks identical either way. This is the same signature-ready PDF our wizard produces automatically from the same inputs.
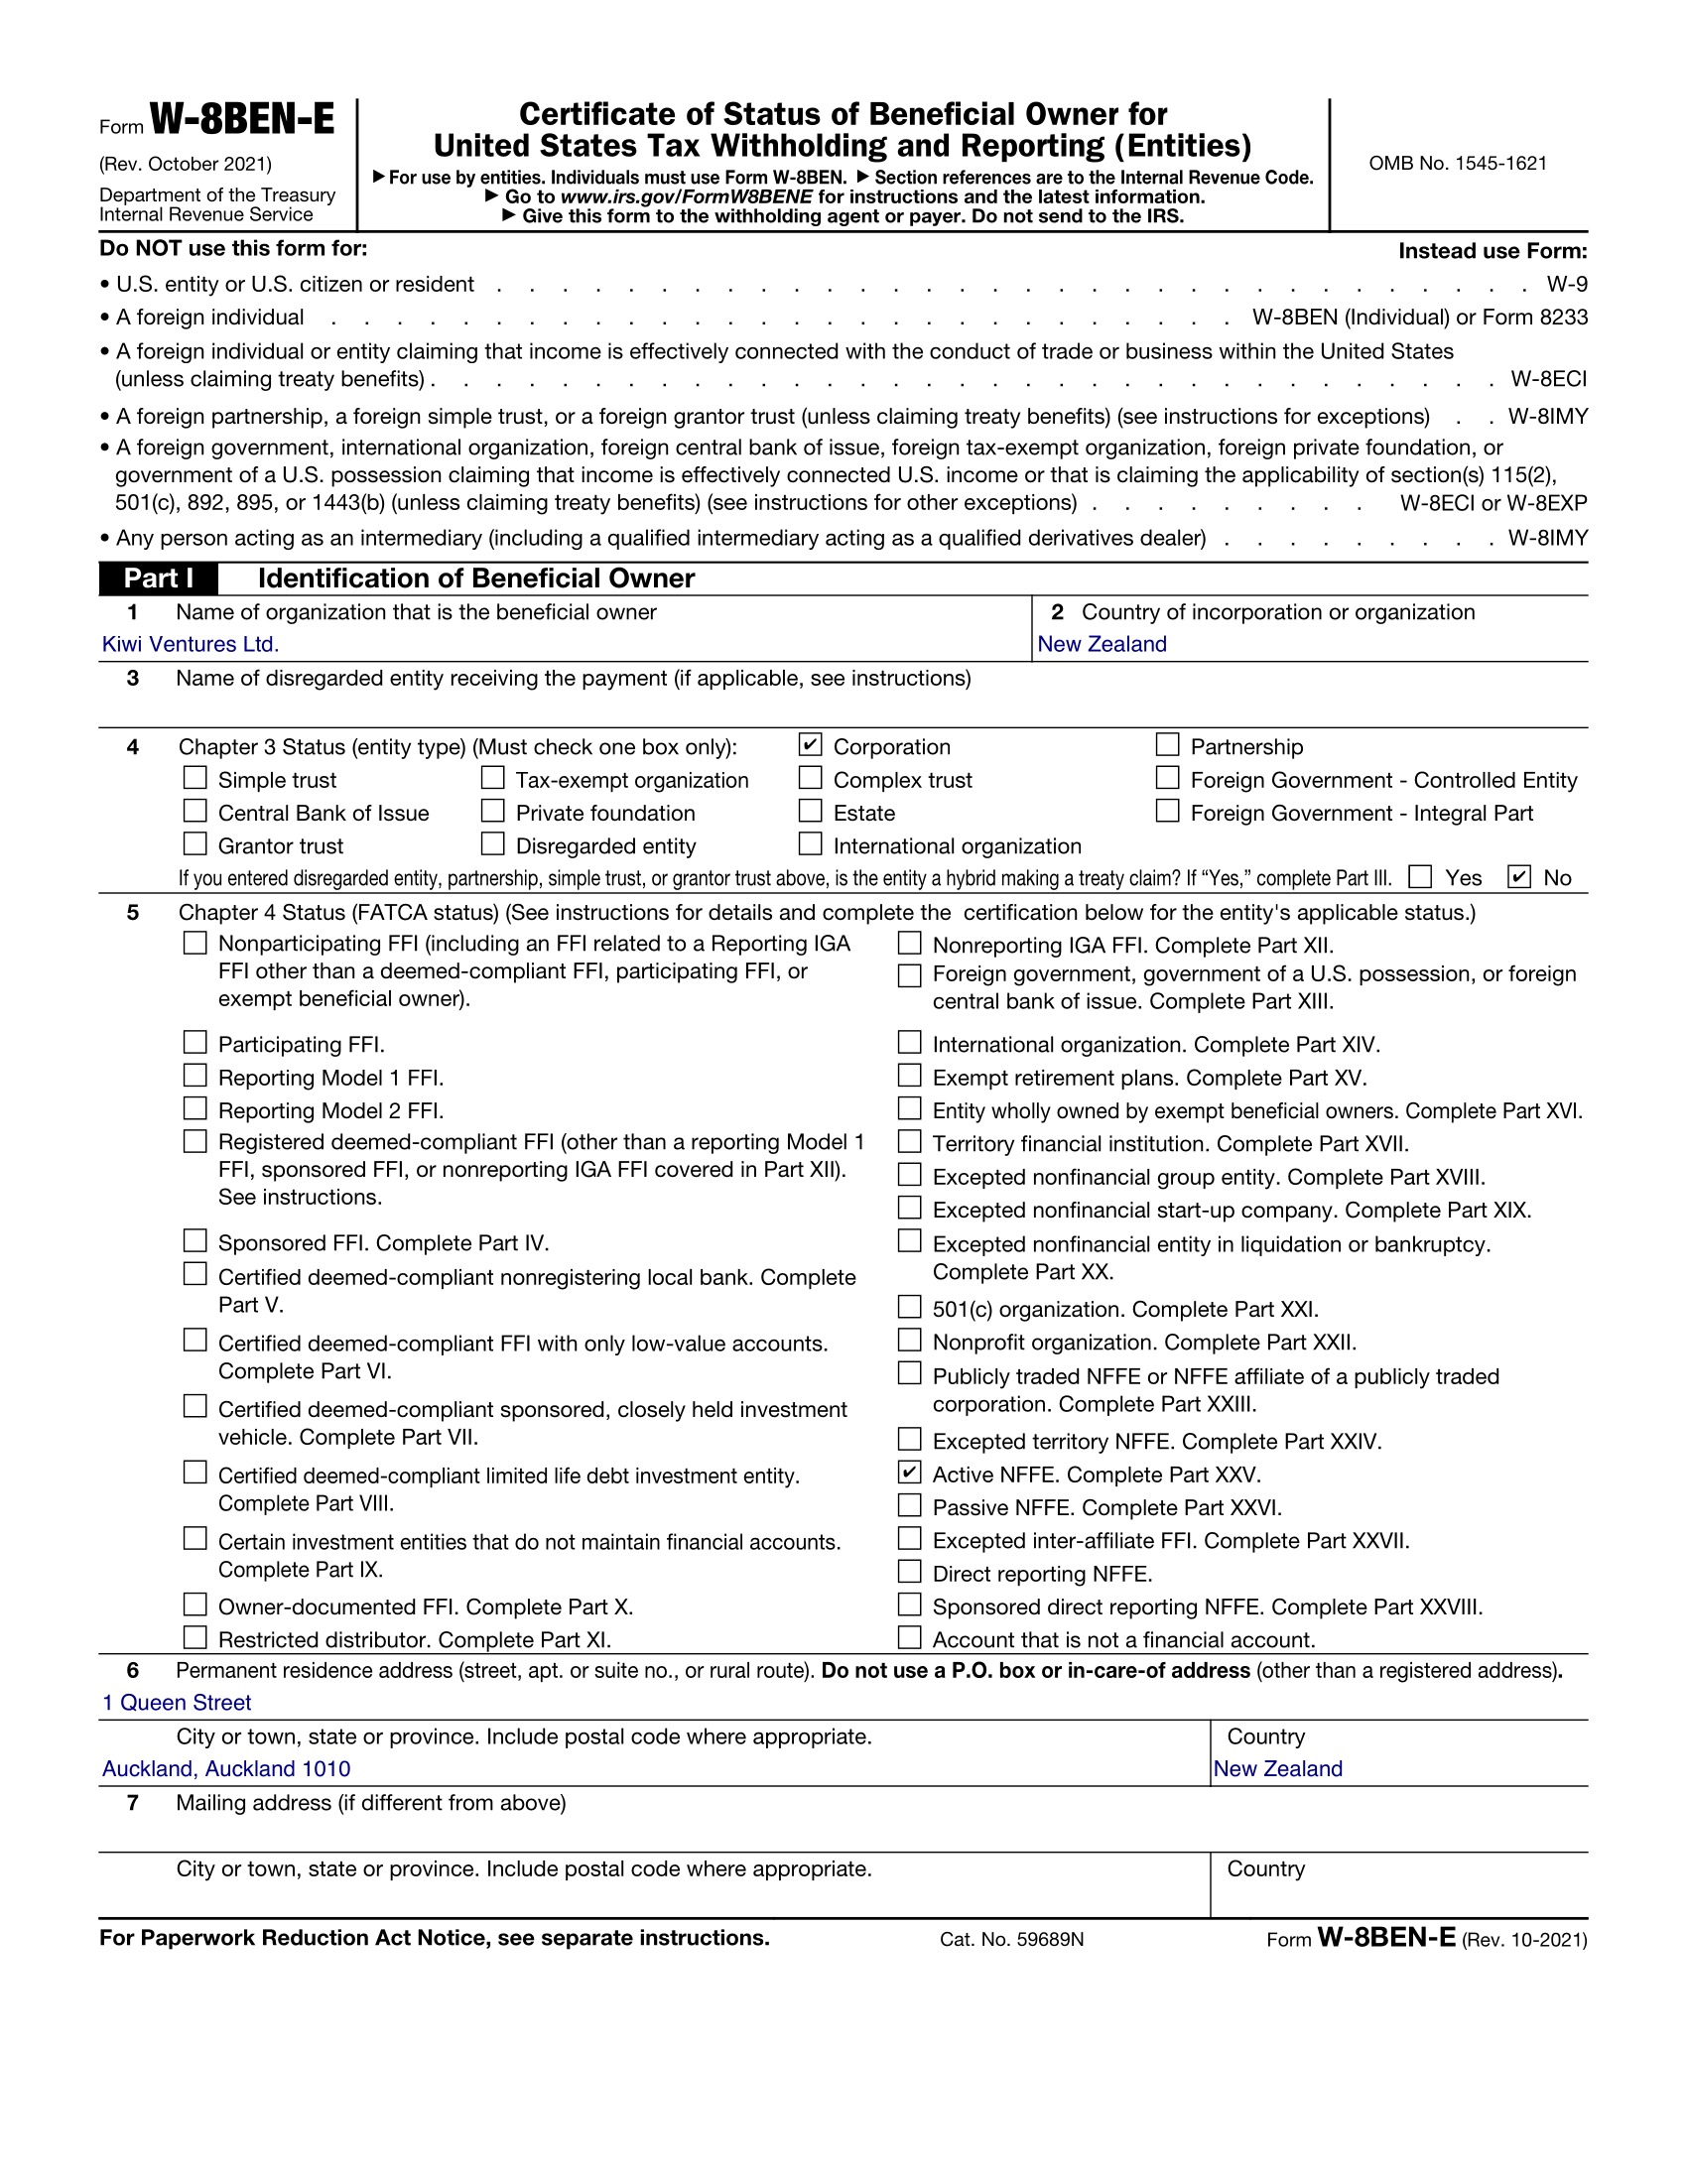
For illustration only — company name, address, director, and IRD number are fictional. Example: Kiwi Ventures Ltd., Auckland, IRD 123-456-789, Chapter 3 Corporation, FATCA Active NFFE, US–New Zealand treaty Article 7(1) (Business Profits) 0%, Active trade or business.
Treaty rates by income type — after the 2008 Protocol
The commonly linked IRS treaty PDF still shows the original 1982 rates. The figures below are the treaty as amended by the Protocol signed 1 December 2008:
| Income type | Article | Rate |
|---|---|---|
| Services / consulting / software (Business Profits) | Article 7 | 0% (with no US permanent establishment) |
| Dividends (company holding ≥10% of the payer's voting power) | Article 10(2)(a) | 5% |
| Dividends (all other ordinary cases, including individuals) | Article 10(2)(b) | 15% |
| Interest (ordinary) | Article 11(2) | 10% of the gross amount |
| Interest (government, government-guaranteed, or qualifying bank / lending-or-finance) | Article 11(3) | 0% — includes 11(3)(c) for a bank or an unrelated lending-or-finance enterprise; not the typical case for a consulting Ltd |
| Royalties — IP only (copyright, patent, trademark, know-how) | Article 12(2) | 5% — reduced from the original 1982 rate of 10%; Article 12(3) is IP only |
| Rental of tangible equipment / leased equipment | Article 7 | 0% (Business Profits — leased equipment is excluded from Article 12(3)) |
If a source cites a 10% royalty rate for New Zealand, that is the pre-2008 rate. The Protocol reduced IP royalties to 5%. Article 12(3) lists only intellectual property — leased equipment is excluded and cites Article 7 at 0% with no US PE. Do not write "Royalties (all types) 5%". A sole trader also cites Article 7: Protocol Article X deleted Article 14, and there is no 183-day presence test. A narrow 0% dividend exception exists under Article 10(3) for 80%+ ownership held for 12 months; it is not the default for an ordinary small or medium business. Article 16 is the Limitation on Benefits article (same number as Australia after its protocol, with updated content).
A blog post explaining the form, or the finished PDF right away?
The New Zealand-specific guides we found are broker or investor notes aimed at Sharesies and Hatch account holders, or generic global guides that still quote the 1982 IRS PDF. Our wizard asks the right questions once and hands you the signature-ready PDF immediately.
| Criterion | Published guides | Our wizard |
|---|---|---|
| What you get | A general explanation, often aimed at individual investors | The completed, signature-ready PDF itself |
| Ltd vs LTC vs sole trader | LTC pass-through is easy to confuse with Partnership | Explained with the exact per se Corporation rule, built into the Chapter 3 step |
| IRD number vs NZBN on Line 9b | Not distinguished — risk of using the public business number | Asks for the IRD number, the actual tax identifier |
| Treaty article & rate (Line 15) | Worked out manually — easy to cite the 1982 PDF | Suggested automatically from the 2008 Protocol facts |
Start the wizard now and get your finished PDF in minutes.
Frequently asked questions about W-8BEN-E for New Zealand companies
Direct answers to the questions New Zealand company owners run into most often when filling this in.
My LTC is taxed like a partnership in NZ — why does the form say Corporation?
Because US classification follows 26 CFR 301.7701-2(b)(8)(i), not Inland Revenue. An LTC is still a Limited Company under the Companies Act 1993. "New Zealand, Limited Company" is on the US per se corporation list, so it is always Corporation on W-8BEN-E. The IR862 election is a New Zealand-only tax treatment.
Is there really no election available at all?
Correct. In most other countries only a Public Limited Company is per se; a private company can file Form 8832. New Zealand lists "Limited Company" itself. Public or private, ordinary Ltd or LTC — no Form 8832 election exists.
What's the difference between IRD number and NZBN?
The IRD number (8 or 9 digits) is the tax identifier and goes on Line 9b. The NZBN is a 13-digit public business number and is not a TIN. Do not put the NZBN on this form.
My broker (Sharesies/Hatch) already asked for a W-8BEN — do I need a different form for my business?
Yes, if the US income is paid to the company. Sharesies and Hatch collect W-8BEN for individual accounts. A company account, including an LTC, needs Form W-8BEN-E.
Does the 2008 Protocol change my dividend rate?
Yes. Article 10 was fully replaced: 5% if a company directly owns at least 10% of the payer's voting power, otherwise 15%. The 1982 IRS PDF does not show that split. A narrow 0% carve-out in Article 10(3) for 80%+ ownership over 12 months is not the default for an ordinary small business.
Is the US–New Zealand tax treaty still the 1982 version?
The 1982 Convention is still the base document, but a 2008 Protocol fully replaced the dividends, interest, royalties, and Limitation on Benefits articles, narrowed royalties to IP only (leased equipment now falls under Article 7), and deleted Article 14. Always apply the Protocol's rates, not the original 1982 figures in irs.gov/pub/irs-trty/newzld.pdf.
Do I need a US EIN, or is the IRD number enough?
For most Ltd companies, the IRD number is sufficient as the "Foreign TIN" on Line 9b. A US EIN is only needed in specific cases your payer will tell you about.
Which Line 14b box should my company check?
For a typical operating Ltd with no complex ownership structure, "Active trade or business" (Article 16) is usually the applicable one. "No LOB Article In Treaty" is not valid — Article 16 exists after the 2008 Protocol.
What's Chapter 4 / Active NFFE?
It's a separate FATCA classification from your entity type. A normal trading company with under 50% passive income and assets is usually "Active NFFE".
What treaty rates typically apply?
Under the US–New Zealand treaty as amended by the 2008 Protocol: 0% on standard service income with no US permanent establishment (Article 7 — a sole trader cites this same article; Article 14 was deleted), 5% on dividends where your company directly holds at least 10% of the voting power, 15% otherwise (Article 10), 10% on ordinary interest (Article 11(2); 0% under 11(3) for government or government-guaranteed debt, or for a qualifying bank / lending-or-finance enterprise under 11(3)(c)), 5% on IP royalties (Article 12(2) — not the pre-2008 10%), and 0% on leased equipment (Article 7; excluded from 12(3)). Our wizard suggests the right one automatically.
Does the form go to Inland Revenue or the IRS?
No — W-8BEN-E goes only to the US payer (client, platform, or broker), never to Inland Revenue or the IRS directly.
How long is W-8BEN-E valid for?
Generally until the end of the third calendar year after signing — a form signed in 2026 is valid through 31 December 2029, provided none of the underlying details change.
What if my company details change?
A change of name, address, entity type, or ownership structure invalidates the existing form, and a new W-8BEN-E is required regardless of the usual three-year cycle.
I'm a sole trader, not a company — which form do I use?
The shorter W-8BEN, using your personal IRD number. Treaty benefits for independent services are Article 7 — the same article as a company — 0% with no US permanent establishment. The 2008 Protocol deleted Article 14; there is no 183-day presence test. This page's line-by-line guidance is for incorporated companies (Ltd and LTC).
Do I need an accountant to complete this?
Not necessarily for standard cases — an ordinary trading Ltd, Active NFFE, common income types can usually be completed with a guided wizard. A holding structure or a complex ownership situation is worth a brief check with a New Zealand tax advisor first.
What does it cost to get W-8BEN-E right?
With our guided wizard, $30 per finished, signature-ready PDF for companies (or $5 for sole traders) — no subscription.
Related guides
For more detail on specific parts of the form:
- Entity type on Line 4 in detail: Full guide to Line 4
- Chapter 3 status in detail: Chapter 3 status guide
- W-8BEN vs W-8BEN-E compared directly: The difference between W-8BEN and W-8BEN-E
- You're a sole trader, not a company: W-8BEN wizard for sole traders ($5)
Common mistakes to avoid
- Selecting Partnership or Disregarded Entity for an LTC: An LTC is still a Limited Company. Check Corporation. The New Zealand pass-through election does not change the US box.
- Citing the pre-2008 10% royalty rate, or treating equipment as a 5% royalty: Article 12(2) is 5% for IP only. Article 12(3) excludes leased equipment — that cites Article 7 at 0%. If a source still says 10% for all royalties, it is reading the 1982 IRS PDF alone.
- Citing deleted Article 14 for a sole trader: Protocol Article X deleted Independent Personal Services. A sole trader cites Article 7 / PE on W-8BEN Line 10, the same article as a company. There is no 183-day test.
- Entering the NZBN instead of the IRD number on Line 9b: The NZBN is a 13-digit public business number, not a tax ID. Line 9b wants the IRD number.
- Treating a sole trader as eligible for W-8BEN-E: A sole trader is not a separate entity. File W-8BEN, not W-8BEN-E.
- Assuming the Article 10(3) 0% dividend carve-out applies: That exception is for 80%+ ownership held for 12 months. It is not the default for an ordinary small or medium business.
A quick note on New Zealand company tax
This page focuses entirely on US withholding tax — the reason your company needs to fill in W-8BEN-E at all. It doesn't cover New Zealand's own tax treatment of that income. The company tax rate is a flat 28%. An LTC is taxed in the owners' hands in New Zealand; that still does not change the US Corporation box.
How that income is actually taxed once it reaches your New Zealand company is a question for a New Zealand tax advisor, not something this page — or our wizard — determines for you. W-8BEN-E only affects what a US payer withholds at source; it has no bearing on how New Zealand taxes your company's profits.
- Company tax rate: 28% flat for a standard company.
- GST: 15%, generally not relevant to the US W-8BEN-E itself.
Ready to finish your own W-8BEN-E instead of reading more guides?
The guided wizard asks the same questions covered on this page — directly inside your own form, with the treaty article and rate suggested automatically from the 2008 Protocol.