W-8BEN-E for a Lithuanian UAB: Services, Software at 10% and Line 14b
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Treaty articles and rates on this page are checked against the US-Lithuania Income Tax Convention signed at Washington on January 15, 1998 (irs.gov/pub/irs-trty/lith.pdf) — last verified October 2026. The PDF header states a general effective date of 1 January 2000 under Article 29. The IRS lists no protocol.
 AI-generated image
UAB, MB, or IĮ? Your legal form decides whether you file W-8BEN-E at all. Services your UAB performs in Lithuania are not US-source income, so there is no US withholding and no treaty claim: Part III (lines 14a, 14b and 15) stays blank. Services performed in the United States are Article 7(1) at 0% with no US permanent establishment, and a software licence is 10%. Do not copy a Danish, Austrian, Finnish, Czech, or Slovak guide that quotes 0% on interest or on software. In this treaty Limitation on Benefits is Article 23, and its test goes on line 14b only when the company claims the treaty.
This guide is for a Lithuanian uždaroji akcinė bendrovė (UAB) or a mažoji bendrija (MB) that invoices US clients. It covers why an individuali įmonė (IĮ) is a different form (Form W-8BEN), when Part III stays blank and when services are Article 7(1), why a software licence and ordinary interest are 10%, why equipment rental is a royalty at 5% (a lease of containers by an enterprise that operates ships or aircraft in international traffic, under Article 8(3), is not), which number goes on Line 9b, and why Limitation on Benefits is Article 23 rather than Article 22. Work done in Lithuania leaves Part III (Lines 14a, 14b and 15) blank. The sample PDF further down shows the other case, a UAB whose developers perform services on site in the United States with no US permanent establishment and claim Article 7(1) at 0% on Line 15.
If you are an individual — individuali veikla, or the owner of an IĮ — you file Form W-8BEN, not this one: start the W-8BEN wizard. A person uses an 11-digit asmens kodas, for example 38501011239. A company uses a 9-digit juridinio asmens kodas. This page is for the company form.
If you prefer to skip the reading, you can start the W-8BEN-E wizard now. In a few minutes you have a signature-ready PDF for $30: Part III blank for services performed in Lithuania, or Article 7(1) at 0% for services performed in the United States with no US permanent establishment.
Blank form or already filled in?
You can download the official, blank form from the IRS and complete it yourself — or get the same file already filled in by our wizard.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for a UAB, an AB, or an MB.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for the owner of an IĮ, or for individuali veikla.
- Already filled in (5–10 minutes): W-8BEN-E for Lithuanian companies ($30) or W-8BEN for individuals ($5).
- The convention: US-Lithuania Income Tax Treaty PDF on IRS.gov — signed January 15, 1998.
- A Latvian company instead: W-8BEN-E for a Latvian SIA follows the US-Latvia convention. The company-form rules on this page are Lithuanian.
UAB, MB, AB, or an IĮ?
Lithuanian company law uses several forms, and US tax classification does not follow the local abbreviation one-for-one:
- Akcinė bendrovė (AB): The public company limited by shares. Under Lithuanian company law an akcinė bendrovė is this public AB, not a private UAB. 26 CFR 301.7701-2(b)(8)(i) lists "Lithuania, Akcine Bendroves" as a per se corporation. Notice 2004-68 added public companies limited by shares. An AB formed on or after October 7, 2004 is a per se corporation and cannot file Form 8832. An AB formed before October 7, 2004 becomes a per se corporation only from the date on which persons who were not owners of that AB as of October 7, 2004 own, in the aggregate, a 50 percent or greater interest in it. Until that date — including while interests move only among persons who were already owners as of October 7, 2004 — that AB remains an eligible entity and may file Form 8832.
- Uždaroji akcinė bendrovė (UAB): The usual private company. Lithuanian company law treats it as its own form, separate from the public akcinė bendrovė. A UAB is not on the per se list. It defaults to Corporation because its members have limited liability, and a different US classification is made on Form 8832. A single-member UAB is not disregarded by default.
- Mažoji bendrija (MB): A small partnership-style company whose members have limited liability. It is not named on the per se list. It defaults to Corporation, and a different US classification requires Form 8832. A single-member MB is not disregarded by default.
- Individuali įmonė (IĮ): A legal person under Lithuanian law, but the owner has unlimited liability. For US tax purposes a single-owner IĮ is disregarded by default. The owner is the beneficial owner and files Form W-8BEN personally. Do not file Form W-8BEN-E for the IĮ.
- Individuali veikla: An individual activity certificate or business licence. Not a separate entity. The person files Form W-8BEN: work done in Lithuania leaves Part II (Lines 9 and 10) blank, and independent personal services performed in the United States are claimed under Article 14(1) on Form 8233. The foreign TIN on Line 6a is an asmens kodas.
- Tikroji ūkinė bendrija (TŪB) or komanditinė ūkinė bendrija (KŪB): Partnership forms. Check "Partnership" in Part I, line 4, not "Corporation."
The trap worth naming: Lithuanian law calling an IĮ a legal person does not make it a corporation for the IRS. A UAB and an MB both default to Corporation because the members have limited liability, and both can leave that default on Form 8832. An AB formed on or after October 7, 2004 is a per se corporation and cannot file Form 8832. An AB formed before October 7, 2004 becomes a per se corporation only from the date on which persons who were not owners of that AB as of October 7, 2004 own, in the aggregate, a 50 percent or greater interest in it. Until that date — including while interests move only among persons who were already owners as of October 7, 2004 — that AB remains an eligible entity and may file Form 8832.
Chapter 3 still decides which form you file and how the payer reads the certificate. The treaty rates sit in Part III, not in the Chapter 3 checkbox.
Who actually needs to submit this form?
Any Lithuanian UAB, AB, or MB that receives payments from a US business and needs to document that it is not a US person. Common situations:
- Invoicing US clients from Lithuania: Your UAB bills a US company for consulting, design, or similar work performed in Lithuania. That income is not from US sources, so there is no US withholding and Part III stays blank. Work your staff perform on site in the United States is US-source: with no US permanent establishment, that is Article 7(1) at 0%.
- A software licence, not a service invoice: A licence to use computer software is a royalty. Article 12(2)(b) caps US withholding at 10%. Article 12(3) only defines royalties. It is not the rate paragraph.
- US payment platforms: Payouts from Stripe, Amazon, YouTube/AdSense, or similar US-headquartered platforms. A Revolut Business account does not change the form or the rate. What matters is the residence of the company, not the bank that receives the payment.
- A US brokerage account: A broker that holds US stock for a Lithuanian company typically wants a current W-8BEN-E before it applies a treaty rate. An investor who is not a company uses Form W-8BEN and an asmens kodas, for example 38501011239.
What the payer withholds, and what the treaty actually changes
Without a submitted W-8BEN-E, a US payer generally withholds 30% of the gross amount of US-source FDAP income: royalties, dividends, interest, and pay for services performed in the United States. Services performed in Lithuania and sales of goods are not US-source FDAP income, so they carry no chapter 3 withholding; without a form the payer may still hold the payment. Filing the form is how the payer knows you are a foreign company and, when the facts fit, which treaty article and rate to apply.
Services performed in Lithuania are foreign-source income. The United States does not tax them, so Part III stays blank and no treaty article is cited. Services your staff perform in the United States are business profits under Article 7(1): with no permanent establishment in the United States, the US rate on the form is 0%. That is not a royalty, and it is not Article 14. Article 14 is for an individual, including the owner of an IĮ. A software licence is different: the convention names computer software inside the Article 12(3) definition, and the rate in Article 12(2)(b) is 10%. Interest the UAB receives on a loan to a US company is Article 11(2) at 10%. That is not the 0% residence-only rule in Austria, Denmark, Finland, Czechia, or Slovakia. The IRS instructions for Form W-8BEN-E say interest on bank deposits is not an amount subject to chapter 3 withholding, so a deposit in a US bank needs no treaty claim, and Article 11(2) does not raise it to 10%.
Form W-8BEN-E, line by line, for a Lithuanian UAB
The line numbers below match the current form (Rev. October 2021). An operating UAB, Active NFFE, that performs its services in Lithuania leaves Part III blank (lines 14a, 14b and 15). The sample below is the other case: a UAB whose developers work on site in the United States and claim Article 7(1) at 0% with no US permanent establishment. Holding companies and financial institutions follow different rules on some lines.
| Line | What you enter |
|---|---|
| Line 1 | The legal name exactly as registered (e.g., "Neris Software UAB"). |
| Line 2 | Country of incorporation: Lithuania. |
| Line 3 | Leave blank for an ordinary UAB or MB. A single-member UAB or MB is not disregarded by default. Disregarded status requires Form 8832. An AB formed on or after October 7, 2004 cannot make that election. |
| Line 4 | "Corporation" for a UAB and an MB (the default), and for an AB that is per se if formed on or after October 7, 2004. An older AB may still file Form 8832 until persons who were not owners as of October 7, 2004 together hold 50 percent or more. "Partnership" for a TŪB or a KŪB. Never check "Corporation" for an IĮ — the owner files Form W-8BEN. |
| Line 5 | Chapter 4 (FATCA) status — almost always "Active NFFE" for an ordinary trading or services company. Ask an accountant if the company mainly holds investments. |
| Line 6 | The registered office in Lithuania, in Latin letters (e.g., Gedimino pr. 1-5, Vilnius, LT-01103). |
| Line 7 | Leave blank if it matches line 6. |
| Line 8 | Leave blank unless the company has actually received a US EIN. |
| Line 9a | Leave blank unless the entity is itself a Foreign Financial Institution. |
| Line 9b | The company's juridinio asmens kodas, 9 digits, for example 304123455. A number starting with 30 is common for a newer company. Do not require the prefix 30. Do not add an LT prefix: that is the PVM (VAT number), and only if the payer asked for a VAT ID. Do not enter an asmens kodas. That 11-digit number belongs on Form W-8BEN, for example 38501011239. |
| Line 9c | In practice this is not checked for a registered UAB — the Register of Legal Entities already issued the number. |
| Line 10 | Leave blank unless the withholding agent specifically asked for a reference number. |
| Part II (Lines 11-13) | Not completed for an ordinary UAB. This part is only for a disregarded entity or a branch receiving the payment. The owner of an IĮ does not use this part: that person files Form W-8BEN. |
| Line 14a | Only when the company claims the treaty: Lithuania. Services performed in Lithuania leave lines 14a, 14b and 15 blank. |
| Line 14b | Only when the company claims the treaty: the Limitation on Benefits test it meets under Article 23. The ownership and base erosion test is Article 23(2)(c), the publicly traded and subsidiary tests are Article 23(2)(e), and active trade or business is Article 23(3). The sample company checks Active trade or business under Article 23(3). "No LOB article in treaty" is the wrong box. Do not cite Article 22: in this treaty Article 22 is Other Income. |
| Line 15 | Blank for services performed in Lithuania. For services performed in the United States with no US permanent establishment: Article 7(1), 0%, type of income Services. A software licence is Article 12(2)(b) at 10%. Equipment rental is Article 12(2)(a) at 5%. Interest on a loan to a US company is Article 11(2) at 10%. Interest on a deposit in a US bank is not subject to chapter 3 withholding and needs no claim. Dividends under 10% of the voting shares of an ordinary company are Article 10(2)(b) at 15%. A RIC dividend is also 15%. A REIT dividend paid to the UAB follows US domestic law, not Article 10(2)(b): the claim stays blank. A lease of containers (including trailers, barges, and related equipment for the transport of containers) used in international traffic, by an enterprise engaged in the operation of ships or aircraft in international traffic, is not that royalty: Article 8(3), 0%, Container Rental. Article 12(6)(c) deems another payment for the use of such containers, not dealt with in Article 8, to arise in neither state: it does not take the 5%, and the wizard writes no line for it. For a rental of ships or aircraft on a full (time or voyage) basis, or on a bareboat basis by an enterprise engaged in the operation of ships or aircraft in international traffic if that rental is incidental to that operation: Article 8(1), 0%, Ship/Aircraft Rental, explained as "Rental of ships or aircraft within Article 8(2)." Article 8(2) makes such profits operating profits, and Article 8(1) is the paragraph that makes them taxable only in Lithuania. The wizard writes no line for this rental, so type these fields by hand. |
Read the juridinio asmens kodas from the register extract before Line 9b. Keep all 9 digits. Do not substitute a director's asmens kodas, and do not type the PVM with an LT prefix unless the payer asked for the VAT ID.
The guided W-8BEN-E wizard fills these lines from your answers, including the article and rate on Line 15. A rental of ships or aircraft under Article 8(2) is the exception: the wizard writes no line for it, and you type Article 8(1), 0% by hand.
Filled example: Neris Software UAB
An operating UAB whose developers work on site in the United States, Chapter 3 Corporation, FATCA Active NFFE, Part III Article 7(1) at 0% for services with no US permanent establishment, Line 14b active trade or business under Article 23(3). Services performed in Lithuania would leave Part III blank.
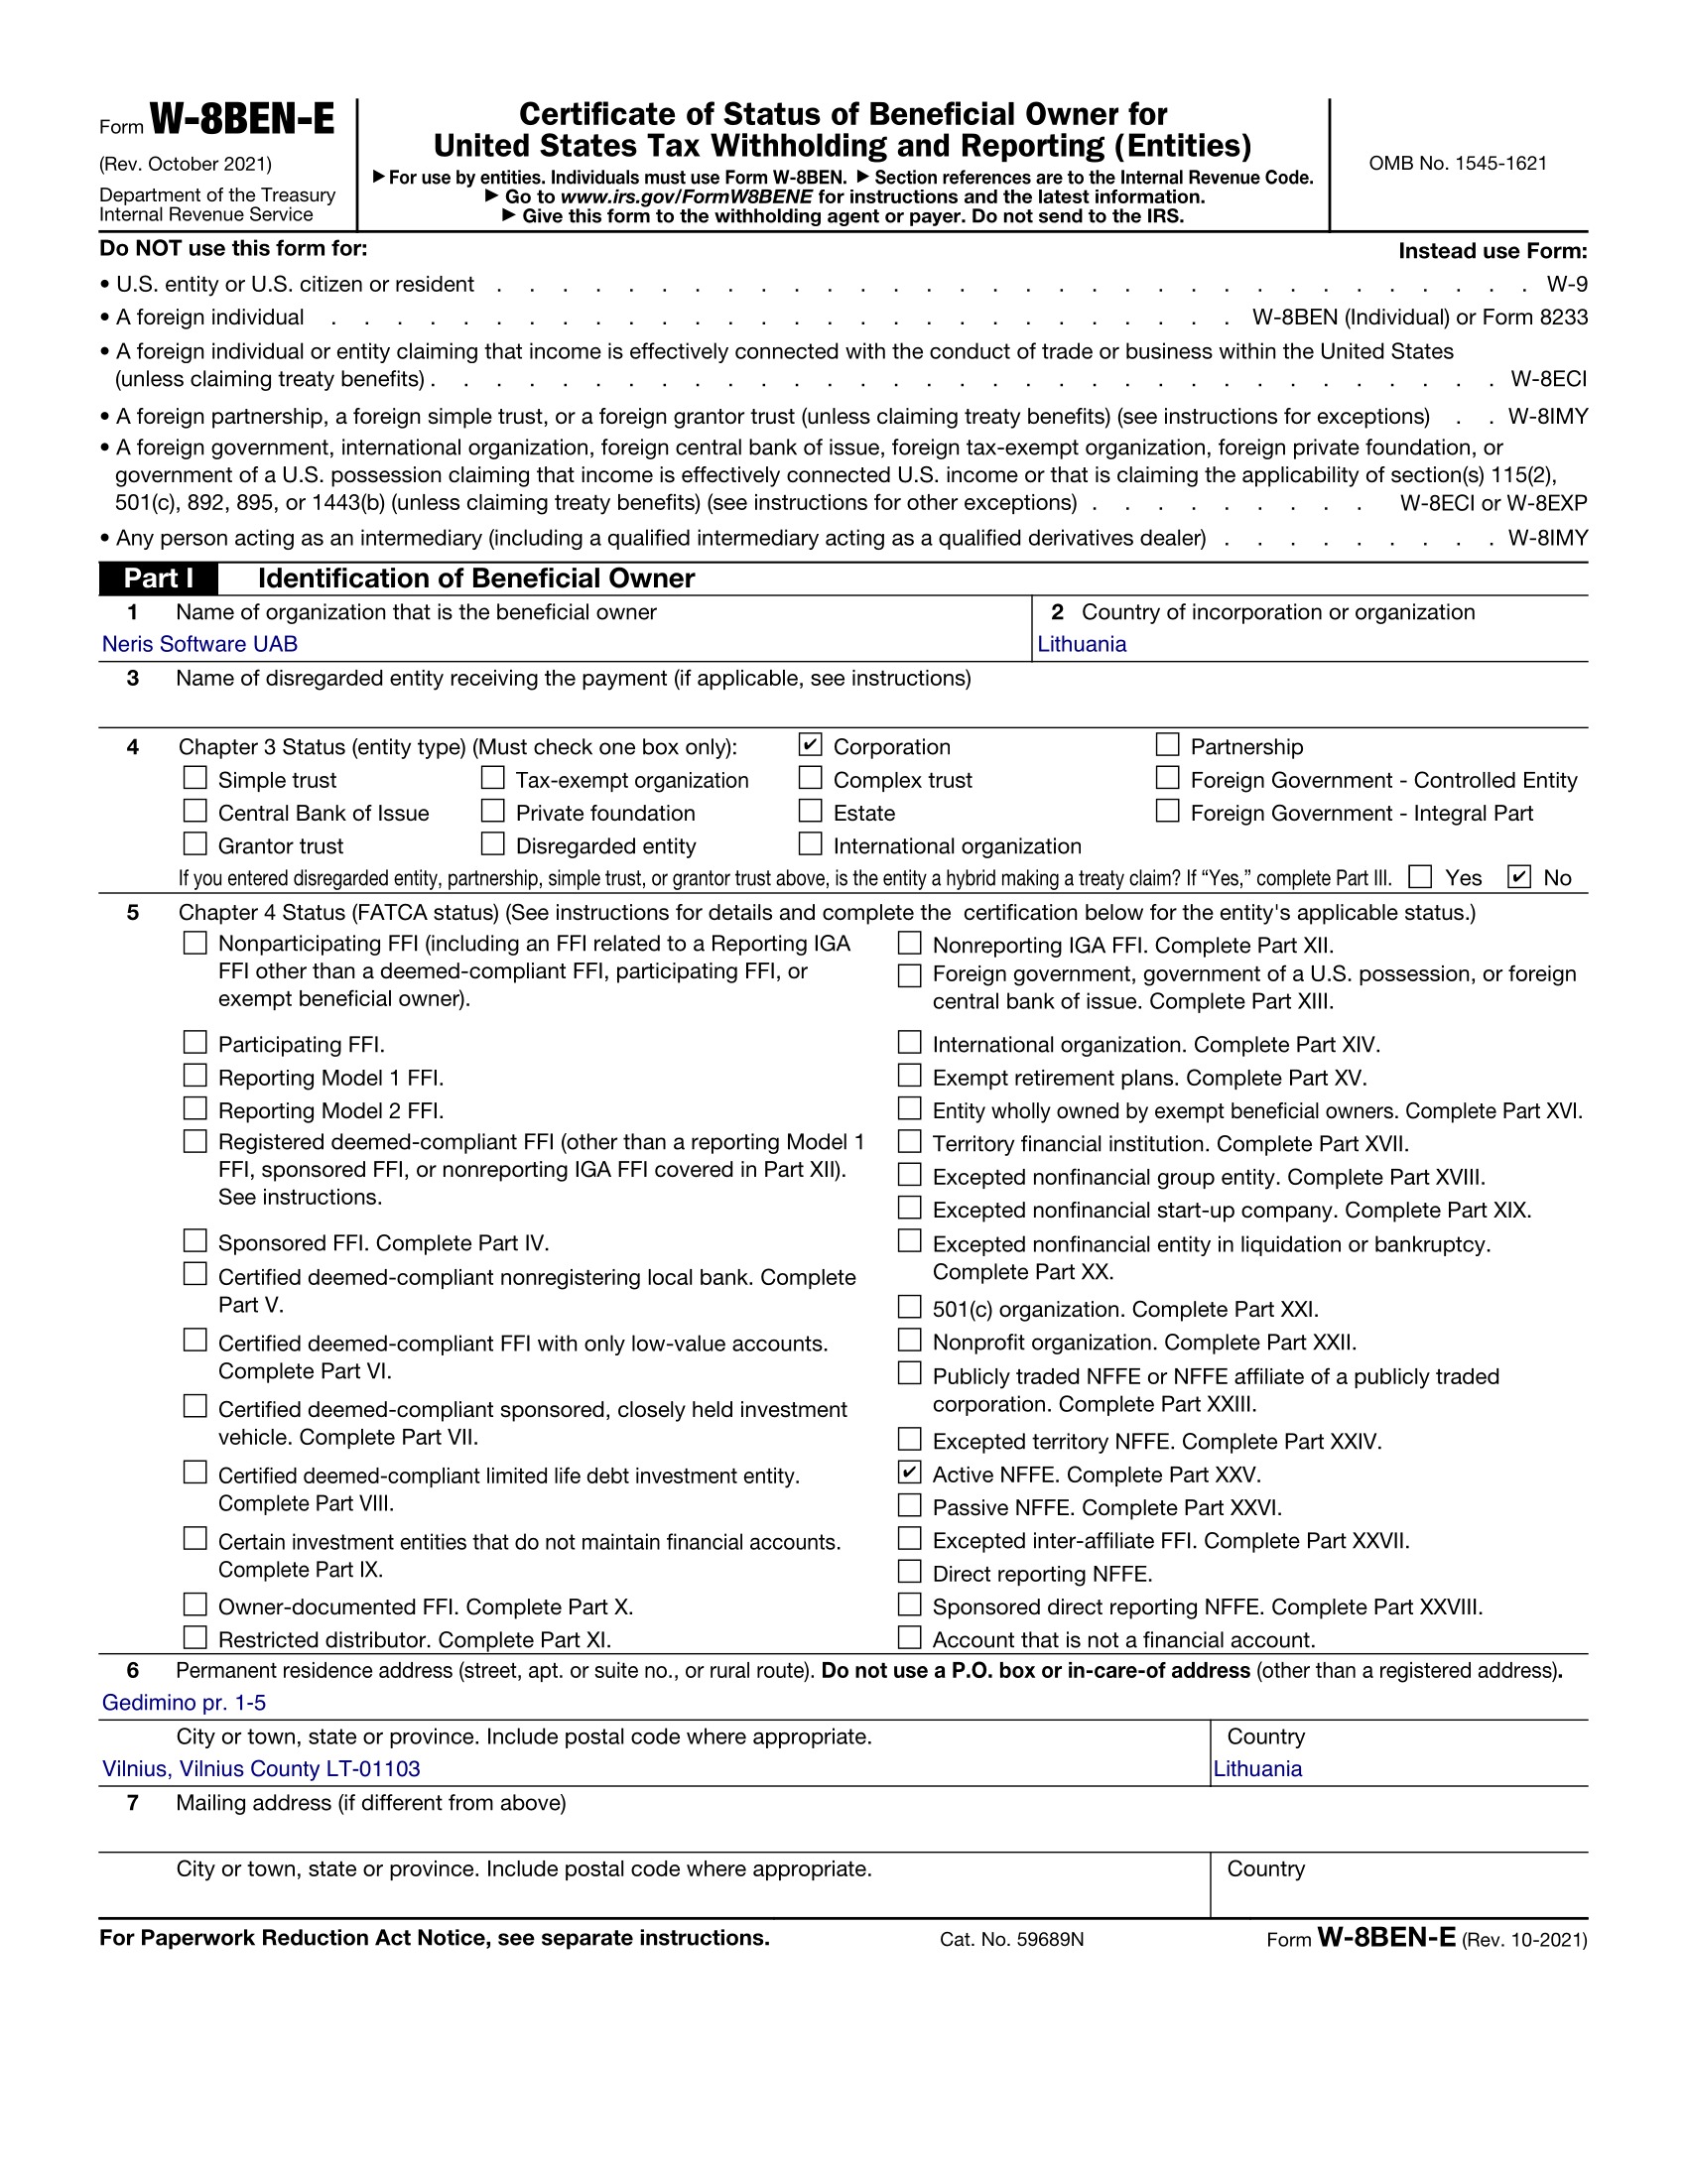
Sample only — uses a fictional company for illustration. Example: Neris Software UAB, Gedimino pr. 1-5, Vilnius LT-01103, Lithuania, juridinio asmens kodas 304123455, Chapter 3 Corporation, FATCA Active NFFE, Article 7(1) at 0% for services performed in the United States with no US permanent establishment, Line 14b active trade or business under Article 23(3).
The rates on Line 15
Use this table for an operating UAB or MB with no permanent establishment in the United States. Do not paste a Danish or Finnish 0% rate onto the Lithuanian form. The wizard writes each of these lines from the treaty and asks you to confirm any condition before it does.
| Income type | Article | Rate |
|---|---|---|
| Services performed in Lithuania | No treaty claim: not US-source, Part III blank | No US withholding |
| Services performed in the United States, no US permanent establishment | Article 7(1) | 0% |
| Software licences, copyrights, patents, trademarks, and know-how | Article 12(2)(b) | 10% |
| Rental of industrial, commercial, or scientific equipment | Article 12(2)(a) | 5% |
| Use, maintenance, or rental of containers (including trailers, barges, and related equipment for the transport of containers) used in international traffic, by an enterprise engaged in the operation of ships or aircraft in international traffic | Article 8(3) | 0% |
| Ordinary interest on a loan to a US company | Article 11(2) | 10% |
| Interest on a deposit in a US bank | Not a treaty claim: not subject to chapter 3 withholding (IRS instructions) | No US withholding |
| Interest owned by the Government of Lithuania, its Central Bank or a financial institution wholly owned by that Government, or on a loan one of them guaranteed or insured | Article 11(3)(a) | 0% |
| Interest on a sale on credit of merchandise or equipment by a Lithuanian enterprise to a US enterprise, not between related persons | Article 11(3)(b) | 0% |
| Interest determined with reference to receipts, sales, income, profits or other cash flow of the debtor or a related person, a change in the value of any property of the debtor or a related person, or a dividend, partnership distribution or similar payment made by the debtor to a related person | Article 11(3)(d) | 15% |
| Dividends, company holding directly at least 10% of the voting shares of an ordinary company (not a RIC or a REIT) | Article 10(2)(a) | 5% |
| Dividends, under 10% of the voting shares of an ordinary company, and every RIC dividend | Article 10(2)(b) | 15% |
| Dividends from a US REIT paid to a UAB or any company | US domestic law, not Article 10(2)(b): the treaty claim stays blank | 30% |
| Independent personal services of an individual performed in the United States | Article 14(1), claimed on Form 8233, not Form W-8BEN | — |
Interest on a deposit in a US bank is not an amount subject to chapter 3 withholding (IRS instructions for Form W-8BEN-E). Do not cite Article 11(2) for that deposit, and do not treat the treaty ceiling as a reason to withhold 10%. Equipment rental is a royalty in this treaty: Article 12(3) names the use of industrial, commercial or scientific equipment, and Article 7(7) defines business profits without it. Do not cite Article 7 at 0% for a lease of that equipment. Cite Article 12(2)(a) at 5%. A SaaS subscription that is a service, with no licence to copy or distribute the software, is not a royalty. When the UAB runs it from Lithuania, Part III stays blank. When the UAB has operations in the United States, that subscription income is business profits under Article 7(1) at 0% with no US permanent establishment. A licence to copy or distribute software is Article 12(2)(b) at 10%. If you are unsure which one you sold, ask an accountant before you certify Line 15. Interest determined with reference to receipts, sales, income, profits or other cash flow of the debtor or a related person, a change in the value of any property of the debtor or a related person, or a dividend, partnership distribution or similar payment made by the debtor to a related person may be taxed at up to 15% under Article 11(3)(d). That includes interest set by the profits of the borrower's parent or another related person, not only by the borrower's own figures. Do not cite 10% for that kind of interest, and do not cite Article 11(3) as the rate for an ordinary cash loan.
Line 14b, and Article 14 for a freelancer
Limitation on Benefits is Article 23. Article 21 is Offshore Activities, so Other Income is Article 22. Do not certify "No LOB article in treaty." Line 14b is filled only when the company claims the treaty, and no test is the default. A UAB or MB meets the ownership and base erosion test of Article 23(2)(c) when, on at least half the days of the taxable year, the beneficial owners of at least 50 percent of each class of its shares are qualified residents under Article 23(2)(a), (b), (e) or (f) (an individual resident, for example) or U.S. citizens, each intermediate owner entitled to benefits under Article 23(2), and when its amounts paid or accrued in the taxable year to persons that are neither qualified residents nor U.S. citizens, and deductible in Lithuania, do not exceed 50 percent of its gross income (arm's length payments in the ordinary course of business for services or tangible property do not count). A company at least 50 percent of the value of each class of whose interests is substantially and regularly traded on a recognized stock exchange (the National Stock Exchange of Lithuania, NASDAQ, a US national securities exchange, or one the competent authorities agree upon) meets Article 23(2)(e)(i). A company whose direct or indirect owners of at least 50 percent of each class of interests are persons entitled to benefits under that clause, each intermediate owner entitled to benefits under Article 23(2), meets Article 23(2)(e)(ii). Otherwise check active trade or business under Article 23(3): an active business in Lithuania, the US income connected with or incidental to it, and that business substantial compared with the US activity. The safe harbour looks at assets, gross income, and payroll in Lithuania, each at least 7.5% of the related US activity, with the average of those three ratios above 10%. Making or managing investments is not an active trade unless a bank, an insurance company, or a registered securities dealer carries it on. Article 23(4) lets the US competent authority grant benefits anyway: only a company that has received that determination checks the discretionary-determination box. An individual who personally performs the work, including the owner of an IĮ and a person on individuali veikla, files Form W-8BEN. Work done in Lithuania is not US-source: Part II stays blank. Pay for services performed in the United States is claimed on Form 8233, not Form W-8BEN, under Article 14(1): the United States may tax it when the person has a fixed base regularly available there, and a stay of more than 183 days in any twelve-month period that begins or ends in the tax year is deemed to create that fixed base.
Questions people ask before they sign
Short answers for an operating UAB. Unusual facts — a US office, a holding company, or a financial institution — need an accountant, not a blog page.
Which rates does the Lithuanian treaty give a UAB?
Services performed in Lithuania have no US withholding and no claim: Part III (lines 14a, 14b and 15) stays blank. Services performed in the United States are Article 7(1) at 0% with no US permanent establishment. Software is Article 12(2)(b) at 10%. Equipment rental is Article 12(2)(a) at 5%. A lease of containers (including trailers, barges, and related equipment for the transport of containers) used in international traffic, by an enterprise engaged in the operation of ships or aircraft in international traffic, is Article 8(3) at 0%, not that royalty. Ordinary loan interest is Article 11(2) at 10%. Dividends are 5% under Article 10(2)(a) or 15% under Article 10(2)(b). Limitation on Benefits is Article 23; its test goes on line 14b only when the UAB claims the treaty. A Lithuanian UAB defaults to Corporation and makes a different classification on Form 8832. An AB formed on or after October 7, 2004 is a per se corporation and cannot file Form 8832. An AB formed before October 7, 2004 becomes a per se corporation only from the date on which persons who were not owners of that AB as of October 7, 2004 own, in the aggregate, a 50 percent or greater interest in it. Until that date — including while interests move only among persons who were already owners as of October 7, 2004 — that AB remains an eligible entity and may file Form 8832.
My US platform asks my IĮ for W-8BEN-E — what now?
An individuali įmonė is a legal person under Lithuanian law, but the owner has unlimited liability. A single-owner IĮ is disregarded by default for US tax purposes. The owner is the beneficial owner and files Form W-8BEN personally. Do not file Form W-8BEN-E in the name of the IĮ. Work done in Lithuania is not US-source, so Part II of Form W-8BEN stays blank. Pay for services performed in the United States is claimed on Form 8233, not Form W-8BEN, under Article 14(1), which looks at a fixed base and at a stay of more than 183 days.
Does Revolut Business change anything?
No. A Lithuanian bank account, including Revolut Business, does not choose the form or the treaty rate. The residence of the company does. A UAB that is a Lithuanian resident still files Form W-8BEN-E. It cites the US-Lithuania convention only when it claims the treaty: for US-source royalties, dividends or interest, for services performed in the United States with no US permanent establishment, for a lease of containers used in international traffic by an enterprise that operates ships or aircraft in international traffic (Article 8(3)), or a rental of ships or aircraft under Article 8(2). Work done in Lithuania leaves Part III (Lines 14a, 14b and 15) blank.
Which Limitation on Benefits article applies?
Article 23. Article 21 of this treaty is Offshore Activities, so Article 22 is Other Income, not Limitation on Benefits. Line 14b is filled only with a treaty claim: the ownership and base erosion test of Article 23(2)(c), the listed-company tests of Article 23(2)(e), or active trade or business under Article 23(3), whichever the company meets. "No LOB article in treaty" does not apply.
Is my SaaS subscription a royalty?
Usually no. A subscription for a service, with no licence to copy or distribute the software, is not a royalty. Run from Lithuania, it has no US withholding and Part III stays blank. With operations in the United States, it is business profits under Article 7(1) at 0% when the UAB has no US permanent establishment. A licence to copy or distribute software is a royalty. The convention names computer software in Article 12(3), and the rate is Article 12(2)(b) at 10%. If you are not sure which one you sold, ask an accountant before you certify Line 15.
Is interest on my US bank deposit withheld?
No. The IRS instructions for Form W-8BEN-E say interest on bank deposits is not an amount subject to chapter 3 withholding. It needs no treaty claim, and Article 11(2) does not raise it to 10%. Do not cite Article 11 on Line 15 for that deposit. A loan the UAB makes to a US company is different: the treaty ceiling is Article 11(2) at 10%. Article 11(3)(a) is 0% only for interest the Government of Lithuania, its political subdivisions or local authorities, its Central Bank or a financial institution wholly owned by that Government own, or interest on a loan one of them guaranteed or insured. Article 11(3)(b) is 0% only for interest on a sale on credit of merchandise or industrial, commercial or scientific equipment by a Lithuanian enterprise to a US enterprise, not between related persons. Do not copy a 0% treaty rule for that loan from Austria, Denmark, Finland, Czechia, or Slovakia.
Which number goes on Line 9b?
The company's juridinio asmens kodas, 9 digits, for example 304123455. A number starting with 30 is common. Do not require that prefix. Do not add LT. That prefix is the PVM. An asmens kodas belongs on Form W-8BEN. It is 11 digits, for example 38501011239. The company example 304123456 fails the check digit, and the personal example 38501011234 fails the personal-code check.
Is equipment rental Article 7?
No. Rental of industrial, commercial, or scientific equipment is a royalty. Cite Article 12(2)(a) at 5%. Do not cite Article 7, and do not use the 10% software rate. A lease of containers (including trailers, barges, and related equipment for the transport of containers) used in international traffic, by an enterprise engaged in the operation of ships or aircraft in international traffic, is different: Article 8(3) makes those profits taxable only in Lithuania, so cite Article 8(3) at 0%. Article 8(2) with Article 8(1) does the same for a rental of ships or aircraft on a full (time or voyage) basis, and for a rental on a bareboat basis by an enterprise engaged in the operation of ships or aircraft in international traffic if that rental is incidental to that operation. Article 12(6)(c) deems another payment for the use of such containers, not dealt with in Article 8, to arise in neither state, so it does not take the 5%.
Can a UAB file Form 8832?
Yes, when it needs a US classification other than Corporation. A UAB is a private company, separate from the public akcinė bendrovė. 26 CFR 301.7701-2(b)(8)(i) lists only "Lithuania, Akcine Bendroves". Notice 2004-68 added public companies limited by shares. An AB formed on or after October 7, 2004 is a per se corporation and cannot file Form 8832. An AB formed before October 7, 2004 becomes a per se corporation only from the date on which persons who were not owners of that AB as of October 7, 2004 own, in the aggregate, a 50 percent or greater interest in it. Until that date — including while interests move only among persons who were already owners as of October 7, 2004 — that AB remains an eligible entity and may file Form 8832. A UAB defaults to Corporation because its members have limited liability. Form 8832 is how it elects partnership or disregarded-entity treatment. A single-member UAB is not disregarded by default. An MB uses the same default and the same election.
What dividend rate applies if we own less than 10%?
Article 10(2)(b) at 15% when the payer is an ordinary US company, and the same 15% for every dividend from a US RIC. Article 10(2)(a) is 5% only when the beneficial owner is a company that holds directly at least 10% of the voting shares of an ordinary company. That 5% does not apply to a RIC or a REIT. A REIT dividend paid to a UAB follows the US domestic-law rate: the treaty claim stays blank and withholding is 30%. Article 10(2)(b) at 15% applies to a REIT only when the owner is an individual holding less than 10% of the REIT. There is no 0% dividend tier. Do not cite Article 10(5): that is a branch-profits tax, not the portfolio rate.
What to do next
- Fill out your W-8BEN-E in the guided wizard: Start the W-8BEN-E wizard ($30)
- Are you the owner of an IĮ?: Use the W-8BEN wizard ($5). Work done in Lithuania leaves Part II blank; pay for services performed in the United States goes on Form 8233 under Article 14(1).
- A Latvian company?: Read the Latvian SIA guide. It follows the US-Latvia convention. A UAB defaults to Corporation and can file Form 8832. An AB formed on or after October 7, 2004 cannot.
Mistakes that get the form sent back
- Filing W-8BEN-E in the name of an IĮ: An individuali įmonė with one owner is disregarded by default. The owner files Form W-8BEN. Lithuanian law calling the IĮ a legal person does not make it a corporation for the IRS.
- Putting 0% on a software royalty: A software licence is Article 12(2)(b) at 10%. Article 12(3) is the definition, including the words computer software. It is not the rate.
- Citing Article 22 as Limitation on Benefits: In the Lithuania treaty, Article 22 is Other Income. Limitation on Benefits is Article 23, and line 14b names the Article 23 test the company meets.
- Sending equipment rental to Article 7: Equipment rental is Article 12(2)(a) at 5%. Article 12(3) names the use of industrial, commercial or scientific equipment, and Article 7(7) defines business profits without it. A lease of containers (including trailers, barges, and related equipment for the transport of containers) used in international traffic, by an enterprise engaged in the operation of ships or aircraft in international traffic, is Article 8(3) at 0%, not that royalty.
- Claiming Article 7(1) for work done in Lithuania: Services performed in Lithuania are not US-source income and have no US withholding. Leave Part III blank. Article 7(1) at 0% is for services performed in the United States with no US permanent establishment.
- Typing an asmens kodas or a PVM on the company form: Line 9b takes the 9-digit juridinio asmens kodas, for example 304123455. The PVM adds an LT prefix. An asmens kodas is 11 digits, for example 38501011239, and it belongs on Form W-8BEN.
- Treating a UAB as per se: The per se row is the public AB, "Lithuania, Akcine Bendroves". A UAB defaults to Corporation and elects a different classification on Form 8832. An AB formed on or after October 7, 2004 is a per se corporation and cannot file Form 8832. An AB formed before October 7, 2004 becomes a per se corporation only from the date on which persons who were not owners of that AB as of October 7, 2004 own, in the aggregate, a 50 percent or greater interest in it. Until that date — including while interests move only among persons who were already owners as of October 7, 2004 — that AB remains an eligible entity and may file Form 8832.