W-8BEN-E for a Korean Company: Chusik Hoesa, Yuhan Hoesa, or Sole Proprietor — Real Treaty Rates, Line-by-Line, and a Sample PDF
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Treaty articles and rates on this page are checked against the 1976 US–Korea Convention signed at Seoul on 4 June 1976 (in force 20 October 1979) — last verified September 2026. The IRS PDF (irs.gov/pub/irs-trty/korea.pdf) is the currently-in-force text. A 1998 renegotiation never produced a signed replacement, so this is not a stale-source trap like Italy or Australia: the 1970s article numbers (Business Profits = Article 8, not 7) are still the ones that apply.
 AI-generated image
Your Korean Chusik Hoesa (주식회사) just invoiced a US client — an MCN, game studio, SaaS company, or agency — and the client's finance team is now asking for a completed W-8BEN-E before they'll release payment. That's one of the two most common reasons Korean company owners end up on this page.
The other is the 서학개미 (overseas-stock retail investor) path: a Korean company or high-net-worth account at Toss Securities, Mirae Asset, Kiwoom, or Interactive Brokers Korea that holds US securities. The broker asks for a W-8BEN or W-8BEN-E so it can apply the correct US withholding on dividends — 15% under Article 12(2)(a) in the ordinary case, not a made-up 0%.
If you're not incorporated — a 개인사업자 (individual business registration) operating under your own name, even if you also have a Business Registration Number — the shorter W-8BEN applies instead: start the W-8BEN wizard. This page covers incorporated businesses: Chusik Hoesa, Yuhan Hoesa, and Yuhan Chaegim Hoesa.
Or skip the reading and start the W-8BEN-E wizard — guided questions, an automatically suggested treaty article and rate (Article 8 for an entity, not Article 7), and a signature-ready PDF for $30.
Blank form or already filled in?
You can download the official, blank form from the IRS and complete it yourself — or get the same file already filled in correctly by our wizard in a few minutes.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for Chusik Hoesa, Yuhan Hoesa, and Yuhan Chaegim Hoesa companies.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for 개인사업자 sole proprietors.
- 1976 Convention (currently in force): Income Tax Treaty PDF on IRS.gov — Business Profits is Article 8, not Article 7.
- IRS treaty documents page: Korea tax treaty documents.
- Already filled in (5–10 minutes): W-8BEN-E for Korean companies ($30) or W-8BEN for sole proprietors ($5) — treaty article and rate suggested automatically, ready to sign as a PDF.
Which Korean company type are you actually dealing with?
The answer depends on your company's legal form, not your revenue and not whether you have a BRN:
- 개인사업자 (individual business registration): Not a separate legal entity — you're treated as an individual for US tax purposes. You use the shorter W-8BEN, not W-8BEN-E. A Business Registration Number does not change that: sole proprietors receive the same-format BRN as companies.
- Chusik Hoesa (주식회사): The most common Korean company type, often written "Co., Ltd." in English. It is on the US per se corporation list — always Corporation for US tax purposes, with no ability to elect a different classification via Form 8832.
- Yuhan Hoesa (유한회사): A limited company. Not on the per se list, but defaults to Corporation because its members have limited liability. Electing partnership or disregarded-entity treatment requires filing Form 8832.
- Yuhan Chaegim Hoesa (유한책임회사): The more flexible LLC-equivalent introduced in 2012 — the form many multinational Korean subsidiaries (including well-known US-group affiliates) use precisely because Form 8832 can change the default. Still a Corporation by default; disregarded or partnership treatment is an election, not the starting point.
The clearest way to tell an incorporated company from a 개인사업자: the company has both a Business Registration Number (BRN, 10 digits) and a Corporate Registration Number (CRN, 13 digits, issued by the court registry). An individual business registration has only the BRN.
Because Korea has a real treaty, this distinction matters: getting the entity type right determines not just which form you file, but which article and rate you can claim in Part III (Lines 14–15). An entity cites Article 8; an individual cites Article 18.
Who actually needs to fill in W-8BEN-E?
In short, any Korean Chusik Hoesa, Yuhan Hoesa, or Yuhan Chaegim Hoesa that receives payments from a US business and wants to document its non-US tax status. Common situations:
- Invoicing US clients directly: Your company bills a US-based business for consulting, development, design, or other services — including MCN, creator-studio, and game-publisher invoices.
- US payment platforms: Payouts from Stripe, Amazon, YouTube/AdSense, or similar US-headquartered platforms.
- US shares and dividends via a broker (서학개미): Your company holds US securities through Toss Securities, Mirae Asset, Kiwoom, Interactive Brokers Korea, or a similar broker and receives dividends.
- Royalty or interest income: Your company receives royalty or interest payments from a US source — ordinary interest is generally 12% and royalties are 15% or 10%, never 0% (see rates below).
What happens without a valid form?
Without a submitted W-8BEN-E, the US payer generally withholds 30% of the gross payment under the nonresident-alien presumption rules — not because it treats you as a US person, and even if a lower rate (or 0%) would otherwise apply under the treaty. Services can be 0% with no US permanent establishment under Article 8; dividends stay 15% (or 10% in a narrow corporate-holder case); interest is generally 12%; royalties are 15% or 10%. Some US platforms and brokers pause payment entirely until a valid form is on file.
The form is never sent to the National Tax Service or the IRS — it stays with the US payer as their own compliance record. Your company still reports the US income as normal on its Korean corporate tax return; W-8BEN-E only affects US withholding at source.
W-8BEN-E line by line: what a Korean Chusik Hoesa actually enters
Below is the official IRS "Line X" numbering exactly as printed on the current form, for the standard case: an operating Chusik Hoesa, Active NFFE, claiming treaty benefits under the 1976 US–Korea treaty. Holding structures and financial institutions follow different rules on some lines — our wizard determines the right answer automatically from your answers.
| Line | What you enter |
|---|---|
| Line 1 | Your company's full legal name exactly as registered (for example, Seoul Tech Co., Ltd.). |
| Line 2 | Country of incorporation: Korea (Republic of). |
| Line 3 | Leave blank — only applies if a disregarded entity is receiving the payment on behalf of its owner. |
| Line 4 | Check "Corporation" for a Chusik Hoesa (always — it is per se), or a Yuhan Hoesa / Yuhan Chaegim Hoesa (by default, unless Form 8832 elected otherwise). A registered partnership checks "Partnership" instead. The "hybrid entity" follow-up question is usually "No" for an ordinary operating company. |
| Line 5 | Chapter 4 (FATCA) status — for a normal operating company with no financial activity, usually "Active NFFE". |
| Line 6 | Your company's actual registered office address (not a virtual mailbox used only for correspondence). |
| Line 7 | Only complete if your mailing address differs from Line 6. |
| Line 8 | Usually blank — a US TIN (EIN) is only required in specific cases your payer will tell you about. |
| Line 9a | Leave blank — a GIIN only applies to financial institutions. |
| Line 9b | Your company's Business Registration Number (BRN, 사업자등록번호, 10 digits, format XXX-XX-XXXXX). This is the tax-purpose foreign TIN — not the 13-digit Corporate Registration Number and not an individual's Resident Registration Number. |
| Line 9c | In practice this is never checked for a registered Chusik Hoesa — a BRN is assigned when the business is registered. |
| Line 10 | Usually blank — only completed at the payer's explicit request. |
| Part II (Lines 11–13) | Not completed for a normal Chusik Hoesa or Yuhan Hoesa — only applies to a disregarded entity or a branch. |
| Line 14a | Country of residence for treaty purposes: Korea (Republic of). |
| Line 14b | Limitation on Benefits (LOB) category — this 1976 treaty has no LOB article at all, so check "No LOB Article In Treaty." Do not invent an active-trade-or-business test. |
| Line 14c | Not normally checked — a narrow special case. |
| Line 15 | Treaty article, paragraph, rate, and income type (e.g. "Article 8(1)", 0%, "Services" for service income with no US permanent establishment). Suggested automatically by the wizard. Never cite Article 7 for Korean business profits. |
| Line 39 (Part XXV) | Check the "Active NFFE" certification, matching Line 5. |
| Part XXX | Signature, printed name, date. Normally signed by a representative director or other authorised signatory. |
Line numbers match the form currently in force (Rev. October 2021). If the IRS issues a new revision, always defer to the numbering on the actual PDF you download.
Every field in the table above is filled in automatically by our guided W-8BEN-E wizard based on your answers — including the treaty article and rate on Line 15.
The BRN vs CRN vs RRN trap on Line 9b: which number actually goes on the form?
This is the single most common identifier mistake for Korean companies — and it is unlike most other countries in this product, because the 13-digit CRN and the 13-digit RRN look the same length.
| Point | What it means |
|---|---|
| BRN (Business Registration Number) | 사업자등록번호, 10 digits, format XXX-XX-XXXXX, issued by the National Tax Service to both companies and sole proprietors. This is the tax-purpose foreign TIN for Line 9b. |
| CRN (Corporate Registration Number) | 법인등록번호, 13 digits, format XXXXXX-XXXXXXX, issued by the court registry only to incorporated companies. It proves legal existence. It is not the tax TIN and should not go on Line 9b. |
| RRN (Resident Registration Number) | 주민등록번호, 13 digits — an individual's identifier, the closest Korean equivalent to a US SSN. It belongs on Form W-8BEN for an individual, not on W-8BEN-E. Same digit count as a CRN, so length alone does not tell them apart. |
| The sole-proprietor trap | A 개인사업자 has a BRN too, but it does not make them a separate entity — they still file the individual Form W-8BEN, never this form. |
| PIPA caution on RRN | South Korea's Personal Information Protection Act (PIPA) restricts private parties from processing RRNs except in narrow, legally-authorized cases. If a private US payer asks a freelancer for an RRN, consider whether disclosure is appropriate, or whether a BRN (if you have one) is a suitable alternative to discuss with the requester. |
Form 8832 can change the Yuhan Hoesa / Yuhan Chaegim Hoesa default (electing partnership or disregarded treatment) — but only if that election has actually been filed. A Chusik Hoesa cannot elect out: it is per se Corporation.
What a completed W-8BEN-E looks like for a Korean Chusik Hoesa
An anonymised example: a Chusik Hoesa providing software consulting to US clients, Active NFFE, no US permanent establishment, claiming treaty benefits under Article 8(1) — 0% withholding on US service income, with "No LOB article in treaty" on Line 14b. This is the same signature-ready PDF our wizard produces automatically from the same inputs.
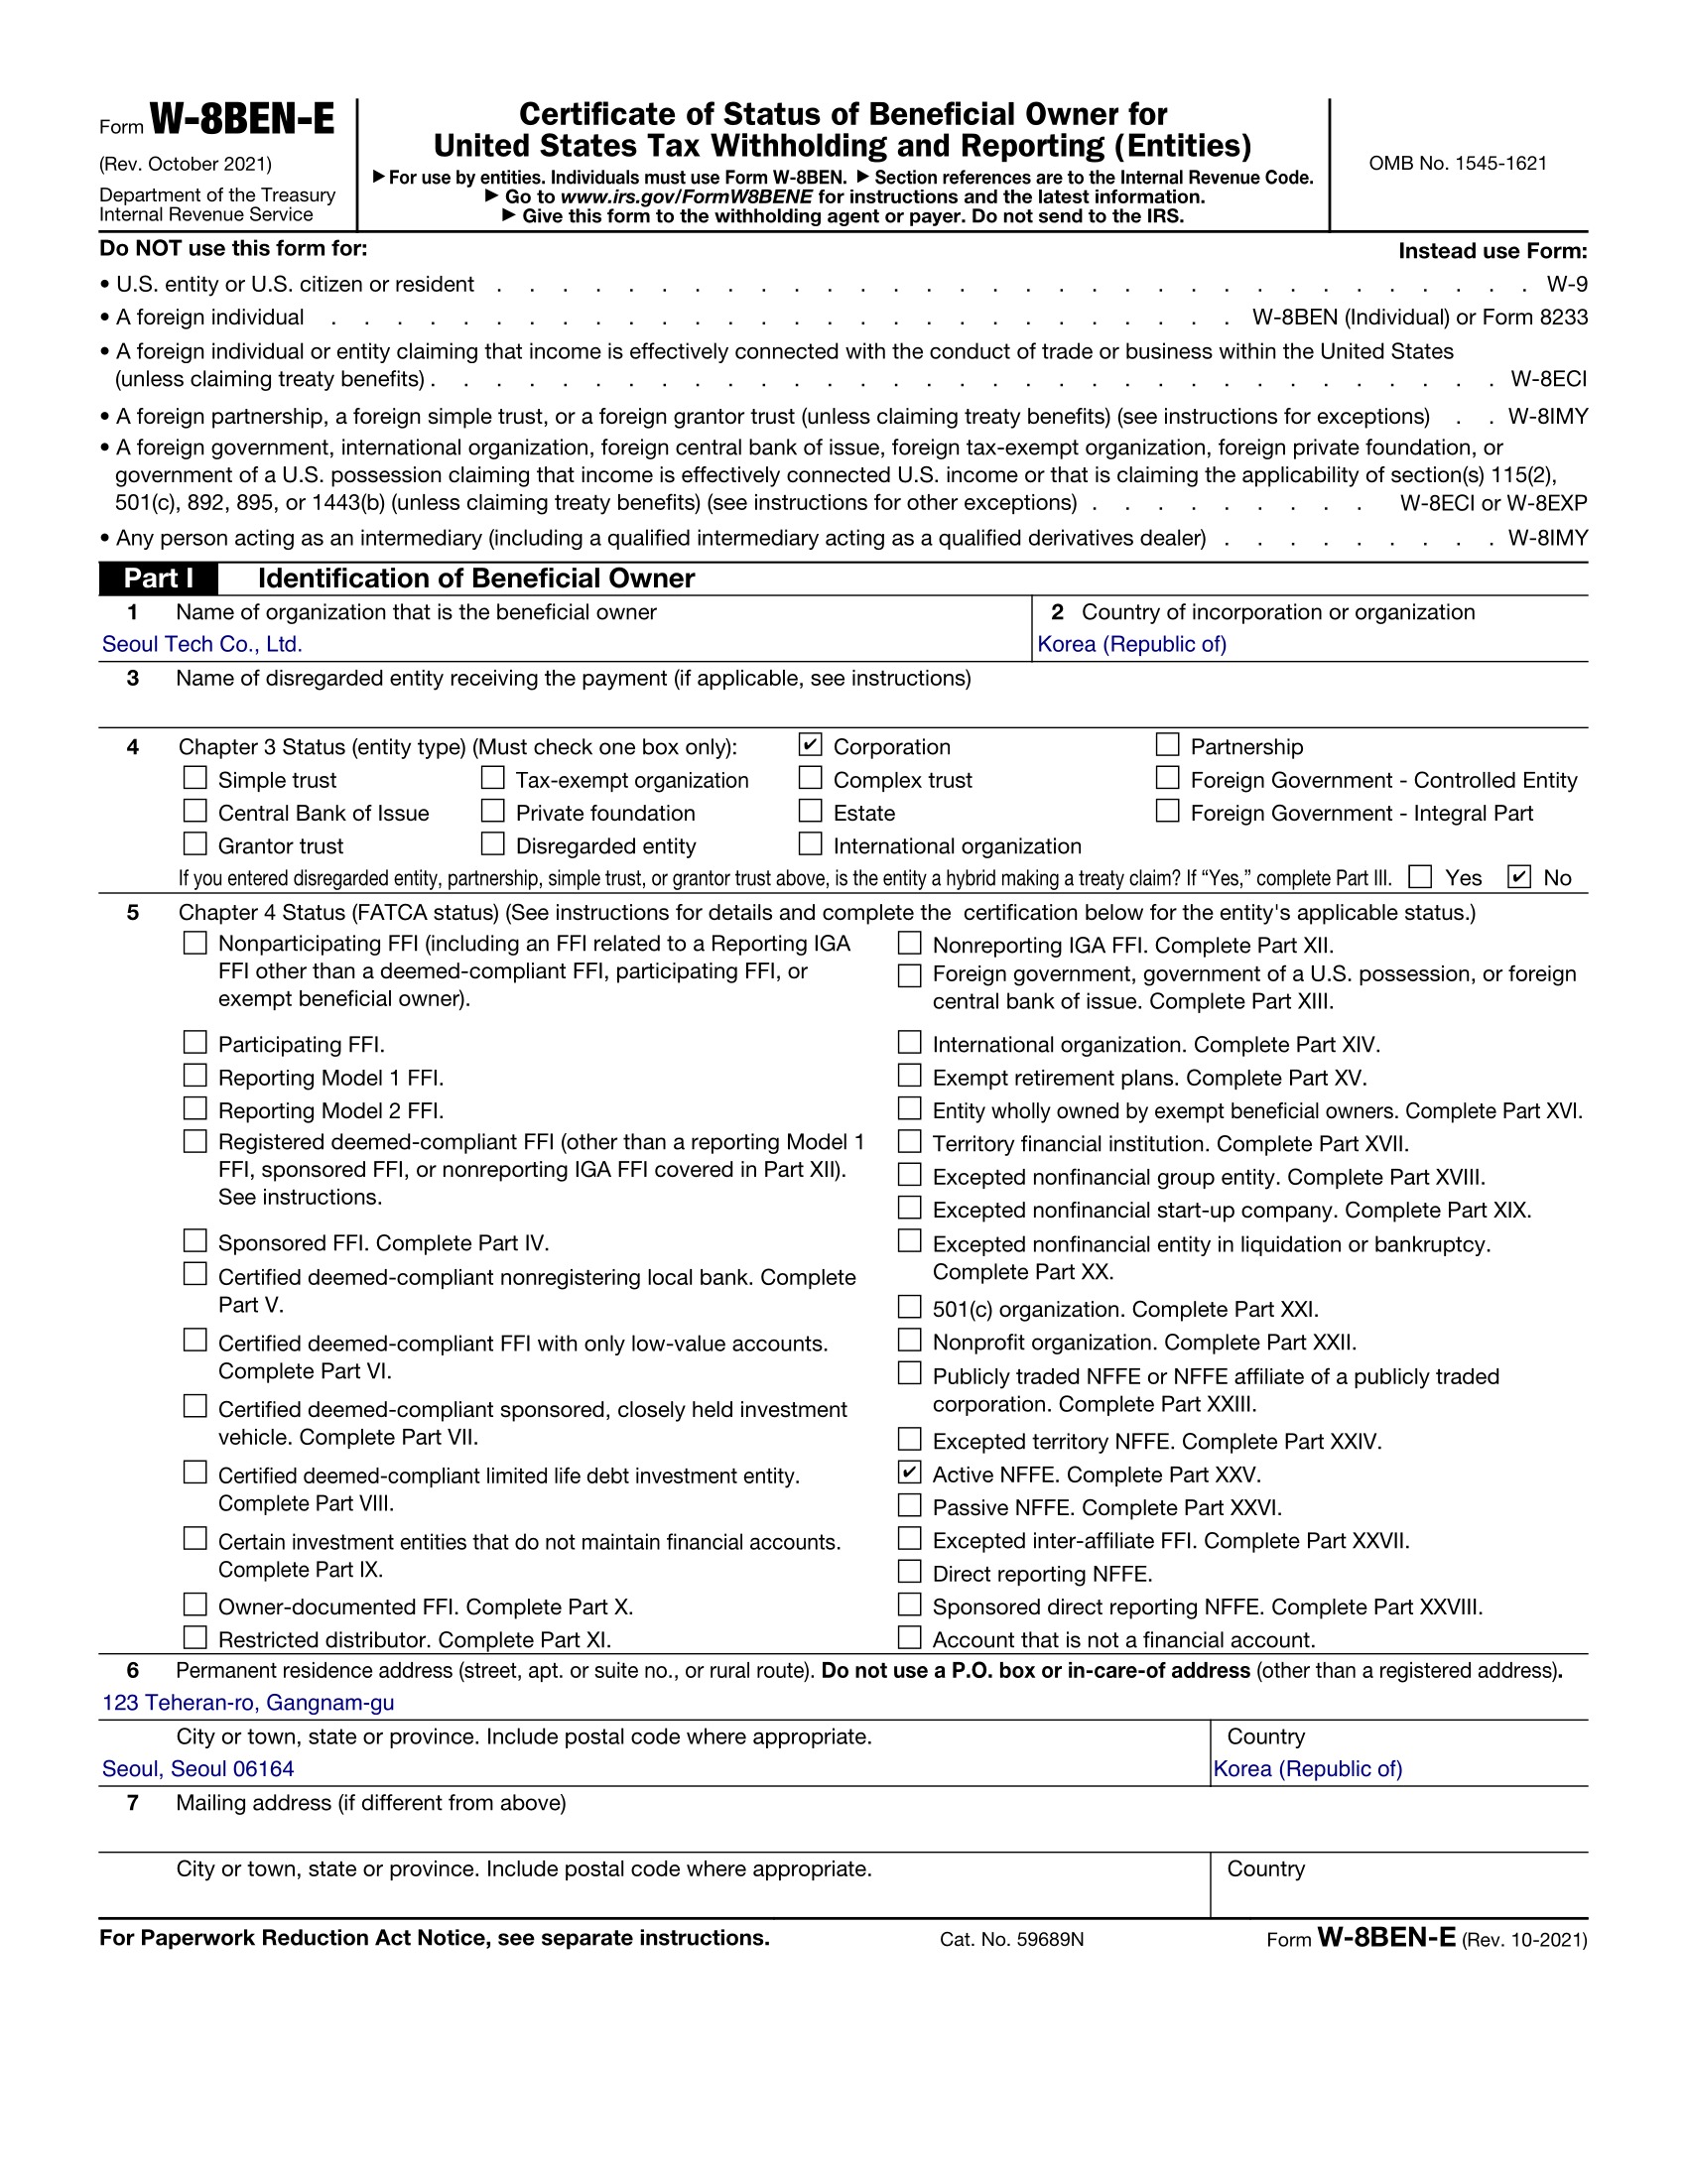
For illustration only — company name, address, director, and BRN are fictional. Example: Seoul Tech Co., Ltd., Seoul, BRN 123-45-67890, Chapter 3 Corporation, FATCA Active NFFE, US–Korea treaty Article 8(1) (Business Profits) 0%, No LOB article in treaty.
Treaty rates by income type — the 1976 Convention, still current
Notice the article numbers. This convention predates the modern "Article 7 = Business Profits" pattern used by most other US treaties. If you see Article 7 cited for Korean business income, that is a red flag:
| Income type | Article | Rate |
|---|---|---|
| Services / consulting / software (Business Profits) | Article 8 | 0% (with no US permanent establishment) |
| Dividends (general, including most 서학개미 accounts) | Article 12(2)(a) | 15% of the gross amount |
| Dividends (10%+ corporate holder, anti-conduit test met) | Article 12(2)(b) | 10% — a niche holding-company case, not the default for an ordinary small business |
| Interest (ordinary) | Article 13(2) | 12% of the gross amount |
| Royalties — patents, trademarks, know-how (IP only) | Article 14(1) | 15% — there is no 0% royalty rate in this treaty |
| Royalties — copyright, literary/artistic/musical, film/broadcast | Article 14(2) | 10% |
| Rental of tangible equipment / personal property | Article 8 | 0% (Business Profits — Art. 8(5); not a royalty under Art. 14(4)) |
| Independent personal services (individuals only) | Article 18 | 0% if services are not performed in the US, or if none of the paragraph-2 tests (183-day presence, $3,000 of US-performed income, or a 183-day fixed base) is met |
You may have seen Korean-language guides claiming a flat 0% treaty rate on royalty income (for example YouTube AdSense or licensing revenue). This is incorrect. There is no 0% royalty rate in the US–Korea treaty. The correct rate is 15% for most IP royalties (Article 14(1)) or 10% specifically for copyright and broadcast-use royalties (Article 14(2)). Equipment rental is not a royalty here: Article 14(4) lists only IP (plus a narrow ships/aircraft case), and Article 8(5) treats rental of tangible personal property as Business Profits — 0% with no US PE. Business Profits is Article 8, not Article 7. Independent personal services for an individual are Article 18, not Article 14.
A blog post explaining the form, or the finished PDF right away?
The Korean-language guides we found are either broker notes aimed at 서학개미 dividend withholding, or creator-tax posts that sometimes quote a flat 0% royalty rate. Our wizard asks the right questions once and hands you the signature-ready PDF immediately.
| Criterion | Published guides | Our wizard |
|---|---|---|
| What you get | A general explanation, often aimed at investors or creators | The completed, signature-ready PDF itself |
| Chusik Hoesa vs Yuhan vs 개인사업자 | Often not distinguished | Explained with the exact default rule, built into the Chapter 3 step |
| BRN vs CRN vs RRN on Line 9b | Not distinguished — risk of using the 13-digit CRN or RRN | Asks for the company identifier and recommends the 10-digit BRN for entities |
| Treaty article & rate (Line 15) | Worked out manually — easy to cite Article 7 or a 0% royalty myth | Suggested automatically from the 1976 facts (Article 8 for an entity) |
Start the wizard now and get your finished PDF in minutes.
Frequently asked questions about W-8BEN-E for Korean companies
Direct answers to the questions Korean company owners run into most often when filling this in.
Is there really no 0% royalty rate?
Correct: there is no 0% royalty rate in the 1976 US–Korea treaty. Article 14(1) caps most IP royalties (patents, trademarks, know-how) at 15%. Article 14(2) caps copyright and film/broadcast royalties at 10%. Equipment rental is not in Article 14(4)'s royalty definition — it is Business Profits under Article 8(5) (0% with no US PE). A Korean-language claim of a flat 0% on YouTube AdSense or licensing income is incorrect.
What's the difference between BRN and CRN?
The BRN (사업자등록번호, 10 digits) is the tax ID issued by the National Tax Service and is what goes on Line 9b. The CRN (법인등록번호, 13 digits) is the court-registry number that proves the company exists — it is not the tax TIN. A 개인사업자 has a BRN but no CRN.
Do I need to give my RRN to a US company?
South Korea's Personal Information Protection Act (PIPA) restricts private parties from processing Resident Registration Numbers except in narrow, legally-authorized cases. If you are an individual freelancer asked for your RRN by a private US payer, consider whether disclosure is appropriate, or whether your BRN (if you have a business registration) is a suitable alternative to discuss with the requester.
My broker (Toss / Mirae Asset / Kiwoom) is asking for a W-8 — which form?
A Chusik Hoesa, Yuhan Hoesa, or Yuhan Chaegim Hoesa files W-8BEN-E. A 개인사업자 or an individual 서학개미 account files the shorter W-8BEN. The broker uses the form to apply Article 12 dividend withholding (generally 15%), not a 0% rate.
Why does the AI advisor cite Article 8 and not Article 7?
Because the 1976 US–Korea Convention numbers Business Profits as Article 8. Most modern US treaties use Article 7. Citing Article 7 for a Korean entity is a red flag that the source is applying the wrong numbering convention.
What's the difference between Chusik Hoesa, Yuhan Hoesa, and Yuhan Chaegim Hoesa for this form?
A Chusik Hoesa always checks "Corporation" on Line 4 (it is on the US per se corporation list). A Yuhan Hoesa or Yuhan Chaegim Hoesa also defaults to Corporation because members have limited liability, but either can elect a different classification via Form 8832. A 개인사업자 is not on this form at all.
What's Chapter 4 / Active NFFE?
It's a separate FATCA classification from your entity type. A normal trading company with under 50% passive income and assets is usually "Active NFFE".
What treaty rates typically apply?
Under the 1976 US–Korea treaty: 0% on standard service income with no US permanent establishment (Article 8), 0% on rental of tangible equipment with no US PE (also Article 8, not 14), 15% on ordinary dividends (Article 12(2)(a); 10% only if a corporate holder meets the 10% ownership and anti-conduit tests), 12% on ordinary interest (Article 13(2); 0% only for the other state's government, local authority, central bank, or a wholly-owned untaxed instrumentality — not an ordinary bank), and 15%/10% on IP royalties (Article 14 — never 0%). Our wizard suggests the right one automatically.
Does the form go to the National Tax Service or the IRS?
No — W-8BEN-E goes only to the US payer (client, platform, or broker), never to the NTS or the IRS directly.
How long is W-8BEN-E valid for?
Generally until the end of the third calendar year after signing — a form signed in 2026 is valid through 31 December 2029, provided none of the underlying details change.
What if my company details change?
A change of name, address, entity type, or ownership structure invalidates the existing form, and a new W-8BEN-E is required regardless of the usual three-year cycle.
I'm a 개인사업자, not a company — which form do I use?
The shorter W-8BEN, using your personal identifier rather than a company CRN. Treaty benefits for independent services are Article 18 — 0% if the services are not performed in the United States, or if you are not present there 183 days or more, do not have a 183-day US fixed base, and (for services performed in the US) do not exceed the $3,000 paragraph-2 threshold. This page's line-by-line guidance is for incorporated companies.
Which Line 14b box should my company check?
"No LOB Article In Treaty." The 1976 convention has no Limitation on Benefits article at all — the same situation as Poland's 1974 treaty. Do not check Active trade or business. Article 17 (Investment or Holding Companies) can still deny Articles 12–14 and 16 for a preferential-tax holding company with 25%+ non-resident owners; it is not an LOB checkbox and does not change Line 14b.
Do I need an accountant to complete this?
Not necessarily for standard cases — an ordinary trading Chusik Hoesa, Active NFFE, common income types can usually be completed with a guided wizard. A holding structure or a complex ownership situation is worth a brief check with a Korean tax professional (세무사) first.
What does it cost to get W-8BEN-E right?
With our guided wizard, $30 per finished, signature-ready PDF for companies (or $5 for sole proprietors) — no subscription.
Related guides
For more detail on specific parts of the form:
- Entity type on Line 4 in detail: Full guide to Line 4
- Chapter 3 status in detail: Chapter 3 status guide
- W-8BEN vs W-8BEN-E compared directly: The difference between W-8BEN and W-8BEN-E
- You're a 개인사업자, not a company: W-8BEN wizard for sole proprietors ($5)
Common mistakes to avoid
- Citing Article 7 for business profits: The correct article is Article 8. Article 7 is not Business Profits in this treaty.
- Claiming a 0% royalty rate: There is no 0% royalty rate on IP. Use 15% (Article 14(1)) or 10% (Article 14(2)) depending on the royalty type. Do not put equipment rental in Article 14 — that is Article 8.
- Entering the 13-digit CRN or RRN on Line 9b: Line 9b wants the 10-digit BRN. CRN and RRN are both 13 digits — length alone does not tell them apart.
- Treating a 개인사업자 as eligible for W-8BEN-E: A sole-proprietor registration is not a separate entity. File W-8BEN, not W-8BEN-E.
- Assuming a Limitation on Benefits test applies: This treaty predates LOB articles. Line 14b should say "No LOB Article In Treaty," not Active trade or business. Article 17 can still deny Arts. 12–14 and 16 for a preferential-tax holding company with 25%+ non-resident owners — it is not an LOB checkbox.
A quick note on Korean corporate tax
This page focuses entirely on US withholding tax — the reason your company needs to fill in W-8BEN-E at all. It doesn't cover Korea's own tax treatment of that income. Korean corporate tax currently uses progressive brackets of 9% / 19% / 21% / 24% depending on taxable income.
How that income is actually taxed once it reaches your Korean company is a question for a licensed 세무사, not something this page — or our wizard — determines for you. W-8BEN-E only affects what a US payer withholds at source; it has no bearing on how Korea taxes your company's profits.
- Corporate tax brackets: 9% / 19% / 21% / 24% depending on taxable income.
- VAT: Generally not relevant to the US W-8BEN-E itself.
Ready to finish your own W-8BEN-E instead of reading more guides?
The guided wizard asks the same questions covered on this page — directly inside your own form, with the treaty article and rate suggested automatically from the 1976 Convention (Article 8 for an entity, Article 18 for an individual).