W-8BEN-E for an Australian Company: Pty Ltd, Public Ltd, or Sole Trader — Correct Treaty Rates, Line-by-Line, and a Sample PDF
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Treaty articles and rates on this page are checked against the 1982 US–Australia Convention and the 2001 Protocol that amends it — last verified October 2026. The Protocol applies to withholding tax on dividends, royalties and interest derived on or after the later of 1 July 2003 and the first day of the second month after it entered into force (Protocol Article 13(2)). The commonly linked IRS PDF (irs.gov/pub/irs-trty/aus.pdf) is the 1982 text only and does not include those Protocol rates.
 AI-generated image
Your Australian Pty Ltd just invoiced a US client for consulting, software, or agency work — and the client's finance team is now asking for a completed W-8BEN-E before they'll release payment. That's the single most common reason Australian company owners end up on this page.
This guide walks through the actual IRS line numbers for that scenario, using the current 2021 revision of the form. If the work is done in Australia, the fee is not US-source income: there is no US withholding, and Part III of the form (Lines 14a, 14b and 15) stays blank. The real filled example below shows the other case, consultants who perform services on site in the United States with no US permanent establishment, claiming Article 7(1) at 0% on Line 15. The guide also covers the two points generic guides get wrong: which Australian company type you actually have, and which treaty rates apply after the 2001 Protocol — not the stale 1982 figures still sitting in the IRS treaty PDF.
If you're not incorporated — a sole trader operating under your own TFN, even if you also have an ABN — the shorter W-8BEN applies instead: start the W-8BEN wizard. This page covers incorporated businesses: Pty Ltd, Public Ltd, and the niche No Liability Company (NL).
Or skip the reading and start the W-8BEN-E wizard — guided questions, an automatically suggested treaty article and rate (post-2001 Protocol), and a signature-ready PDF for $30.
Blank form or already filled in?
You can download the official, blank form from the IRS and complete it yourself — or get the same file already filled in correctly by our wizard in a few minutes.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for Pty Ltd, Public Ltd, and NL companies.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for sole traders.
- 1982 Convention (base text only): Income Tax Treaty PDF on IRS.gov — do not use its dividend and royalty rates on their own.
- 2001 Protocol (the rates that apply today): Protocol signed 27 September 2001 on Treasury.gov.
- Already filled in (5–10 minutes): W-8BEN-E for Australian companies ($30) or W-8BEN for sole traders ($5) — treaty article and rate suggested automatically, ready to sign as a PDF.
Which Australian company type are you actually dealing with?
The answer depends on your company's legal form, not your revenue and not whether you have an ABN:
- Sole trader: Not a separate legal entity — you're treated as an individual for US tax purposes. You use the shorter W-8BEN, with your personal TFN, not W-8BEN-E. An ABN does not change that.
- Pty Ltd (Proprietary Limited): By far the most common Australian company type. Not on the US "per se corporation" list, but defaults to Corporation for US tax purposes anyway, because its shareholders have limited liability. Electing a different classification requires filing Form 8832.
- Public Limited Company (Ltd): The one common Australian company type explicitly on the US "per se corporation" list — always Corporation, with no ability to elect a different classification via Form 8832. Typical of larger or ASX-listed companies.
- No Liability Company (NL): A niche mining or mineral-exploration form. Also on the US per se corporation list — always Corporation. Rare outside that sector; mentioned so you recognise the NL suffix if you see it.
A quick myth to clear up: having an ABN does not, by itself, tell you which form to file. The Australian Business Register issues an ABN to sole traders and partnerships exactly as it does to Pty Ltd and Public Ltd companies — the ABN identifies a business for invoicing and GST, not a separate legal entity. Check your actual registration type (sole trader vs a company registered with ASIC, which also has an ACN) to know which W-8 form applies.
Because Australia has a real treaty, this distinction matters: getting the entity type right determines not just which form you file, but which article and rate you can claim in Part III (Lines 14–15).
Who actually needs to fill in W-8BEN-E?
In short, any Australian Pty Ltd, Public Ltd, or NL that receives payments from a US business and wants to document its non-US tax status. Common situations:
- Invoicing US clients directly: Your company bills a US-based business for consulting, development, design, or other services.
- US payment platforms: Payouts from Stripe, Amazon, YouTube/AdSense, or similar US-headquartered platforms.
- US shares and dividends via a broker: Your company holds US securities through a broker (Interactive Brokers Australia, CommSec, Stake, SelfWealth, or similar) and receives dividends.
- Royalty or interest income: Your company receives royalty or interest payments from a US source — ordinary interest is generally 10% and royalties 5% after the 2001 Protocol (see rates below).
What happens without a valid form?
Without a submitted W-8BEN-E, a US payer generally withholds 30% of the gross amount of US-source income such as dividends, interest, royalties, and pay for services performed in the United States — even if a lower rate (or 0%) would otherwise apply under the treaty. Services your company performs in Australia are not US-source income, so no US tax is withheld on them, but the payer may still hold the payment until a valid form is on file. Services performed in the United States can be 0% under Article 7(1) when the company has no US permanent establishment; dividends stay 5%/15% (RIC and REIT dividends are narrower still); interest is generally 10%; royalties are 5% after the 2001 Protocol (not the 10% in the 1982 IRS PDF). Some US platforms and brokers pause payment entirely until a valid form is on file.
The form is never sent to the ATO or the IRS — it stays with the US payer as their own compliance record. Your company still reports the US income as normal on its Australian company tax return; W-8BEN-E only affects US withholding at source.
W-8BEN-E line by line: what an Australian Pty Ltd actually enters
Below is the official IRS "Line X" numbering exactly as printed on the current form, for an operating Pty Ltd or Public Ltd, Active NFFE. In the most common case — services performed in Australia for a US client — the income is not US-source, so Part III (Lines 14a, 14b, and 15) stays blank. Lines 14a, 14b, and 15 are filled only when the company claims the treaty as amended by the 2001 Protocol: for dividends, interest, or royalties from the United States, or for services its staff perform in the United States with no US permanent establishment (the case the sample PDF below shows). Holding structures and financial institutions follow different rules on some lines — our wizard determines the right answer automatically from your answers.
| Line | What you enter |
|---|---|
| Line 1 | Your company's full legal name exactly as registered with ASIC (for example, Southern Cross Pty Ltd). |
| Line 2 | Country of incorporation: Australia. |
| Line 3 | Leave blank — only applies if a disregarded entity is receiving the payment on behalf of its owner. |
| Line 4 | Check "Corporation" for a Public Ltd or NL (always), or a Pty Ltd (by default, unless Form 8832 elected otherwise). A registered partnership checks "Partnership" instead. The "hybrid entity" follow-up question is usually "No" for an ordinary Pty Ltd or Public Ltd. |
| Line 5 | Chapter 4 (FATCA) status — for a normal operating company with no financial activity, usually "Active NFFE". |
| Line 6 | Your company's actual registered office address (not a virtual mailbox used only for correspondence). |
| Line 7 | Only complete if your mailing address differs from Line 6. |
| Line 8 | Usually blank — a US TIN (EIN) is only required in specific cases your payer will tell you about. |
| Line 9a | Leave blank — a GIIN only applies to financial institutions. |
| Line 9b | Your company's Tax File Number (TFN, 9 digits) is the technically correct "Foreign TIN" — but because TFNs are treated as confidential in Australia, many companies instead provide their public Australian Business Number (ABN, 11 digits). Either is used in practice; see the dedicated note below. This is NOT an individual's TFN, even though both are 9 digits. |
| Line 9c | In practice this is never checked for a registered Pty Ltd or Public Ltd — an ABN/TFN is assigned when the company is registered. |
| Line 10 | Usually blank — only completed at the payer's explicit request. |
| Part II (Lines 11–13) | Not completed for a normal Pty Ltd or Public Ltd — only applies to a disregarded entity or a branch. |
| Line 14a | Only when the company claims the treaty: country of residence for treaty purposes, Australia. Services performed in Australia leave it blank. |
| Line 14b | Only when the company claims the treaty: the Limitation on Benefits (LOB) test it meets under Article 16 (as replaced by the 2001 Protocol), so "No LOB Article In Treaty" is not valid here. An operating Pty Ltd usually checks "Active trade or business" under Article 16(3): it actively conducts a trade or business in Australia (not making or managing investments for its own account, unless banking, insurance or securities activities carried on by a bank, insurance company or registered, licensed or authorized securities dealer), the US income is derived in connection with, or is incidental to, that business, and, where it or an associated enterprise carries on a business activity in the United States that gives rise to the income, the Australian activity is substantial in relation to it. |
| Line 14c | Not normally checked — a narrow special case. |
| Line 15 | Only when the company claims the treaty: article, paragraph, rate, and income type — for example "Article 7(1)", 0%, "Services" for services performed in the United States with no US permanent establishment. Services performed in Australia leave it blank. Suggested automatically by the wizard. Never cite the pre-2001 dividend or royalty rates from the 1982 IRS PDF alone. |
| Line 39 (Part XXV) | Check the "Active NFFE" certification, matching Line 5. |
| Part XXX | Signature, printed name, date. Normally signed by a director or other authorised signatory. |
Line numbers match the form currently in force (Rev. October 2021). If the IRS issues a new revision, always defer to the numbering on the actual PDF you download.
Every field in the table above is filled in automatically by our guided W-8BEN-E wizard based on your answers — including the treaty article and rate on Line 15.
The ABN vs TFN trap on Line 9b: which number actually goes on the form?
This is the single most common identifier mistake for Australian companies — and it is unlike most other countries in this product, because the TFN is the same length for individuals and companies.
| Point | What it means |
|---|---|
| What each number is | TFN (Tax File Number, 9 digits) is issued by the ATO to both individuals and entities and is Australia's official tax identifier. ABN (Australian Business Number, 11 digits, formatted XX XXX XXX XXX) is issued by the Australian Business Register for invoicing and GST — a company's ABN is built from its 9-digit ACN plus a 2-digit check prefix. |
| Why this is confusing | Unlike most countries here, Australia's TFN is the SAME LENGTH (9 digits) for individuals and companies — so an incorrect entry doesn't "look wrong" the way a 10-digit vs 11-digit mix-up would elsewhere. The real question is which number to disclose, not which format to use. |
| What Australian businesses actually do | Many Australian companies are reluctant to share their confidential TFN with a private US payer, and provide their public ABN instead. Both are accepted in practice as a "Foreign TIN" on this form. Our sample PDF uses the 11-digit ABN. |
| The sole trader trap | A sole trader has an ABN too, but it does not make them a separate entity — they still use their personal TFN and file the individual Form W-8BEN, never this form. |
| Form 8832 election angle | A Pty Ltd can elect partnership or disregarded-entity treatment by filing Form 8832; a Public Limited Company cannot (it is per se). A sole trader cannot file Form 8832 — they are not a separate entity. |
Form 8832 can change the Pty Ltd default (electing partnership or disregarded treatment) — but only if that election has actually been filed. Absent a Form 8832 election, use Corporation for a Pty Ltd.
What a completed W-8BEN-E looks like for an Australian Pty Ltd
An anonymised example: a Proprietary Limited company whose software consultants perform services on site in the United States for short engagements, Active NFFE, no US permanent establishment, claiming treaty benefits under Article 7(1) — 0% withholding on that US-source service income, with "Active trade or business" on Line 14b. If the same work were done in Australia, Part III would stay blank. This is the same signature-ready PDF our wizard produces automatically from the same inputs.
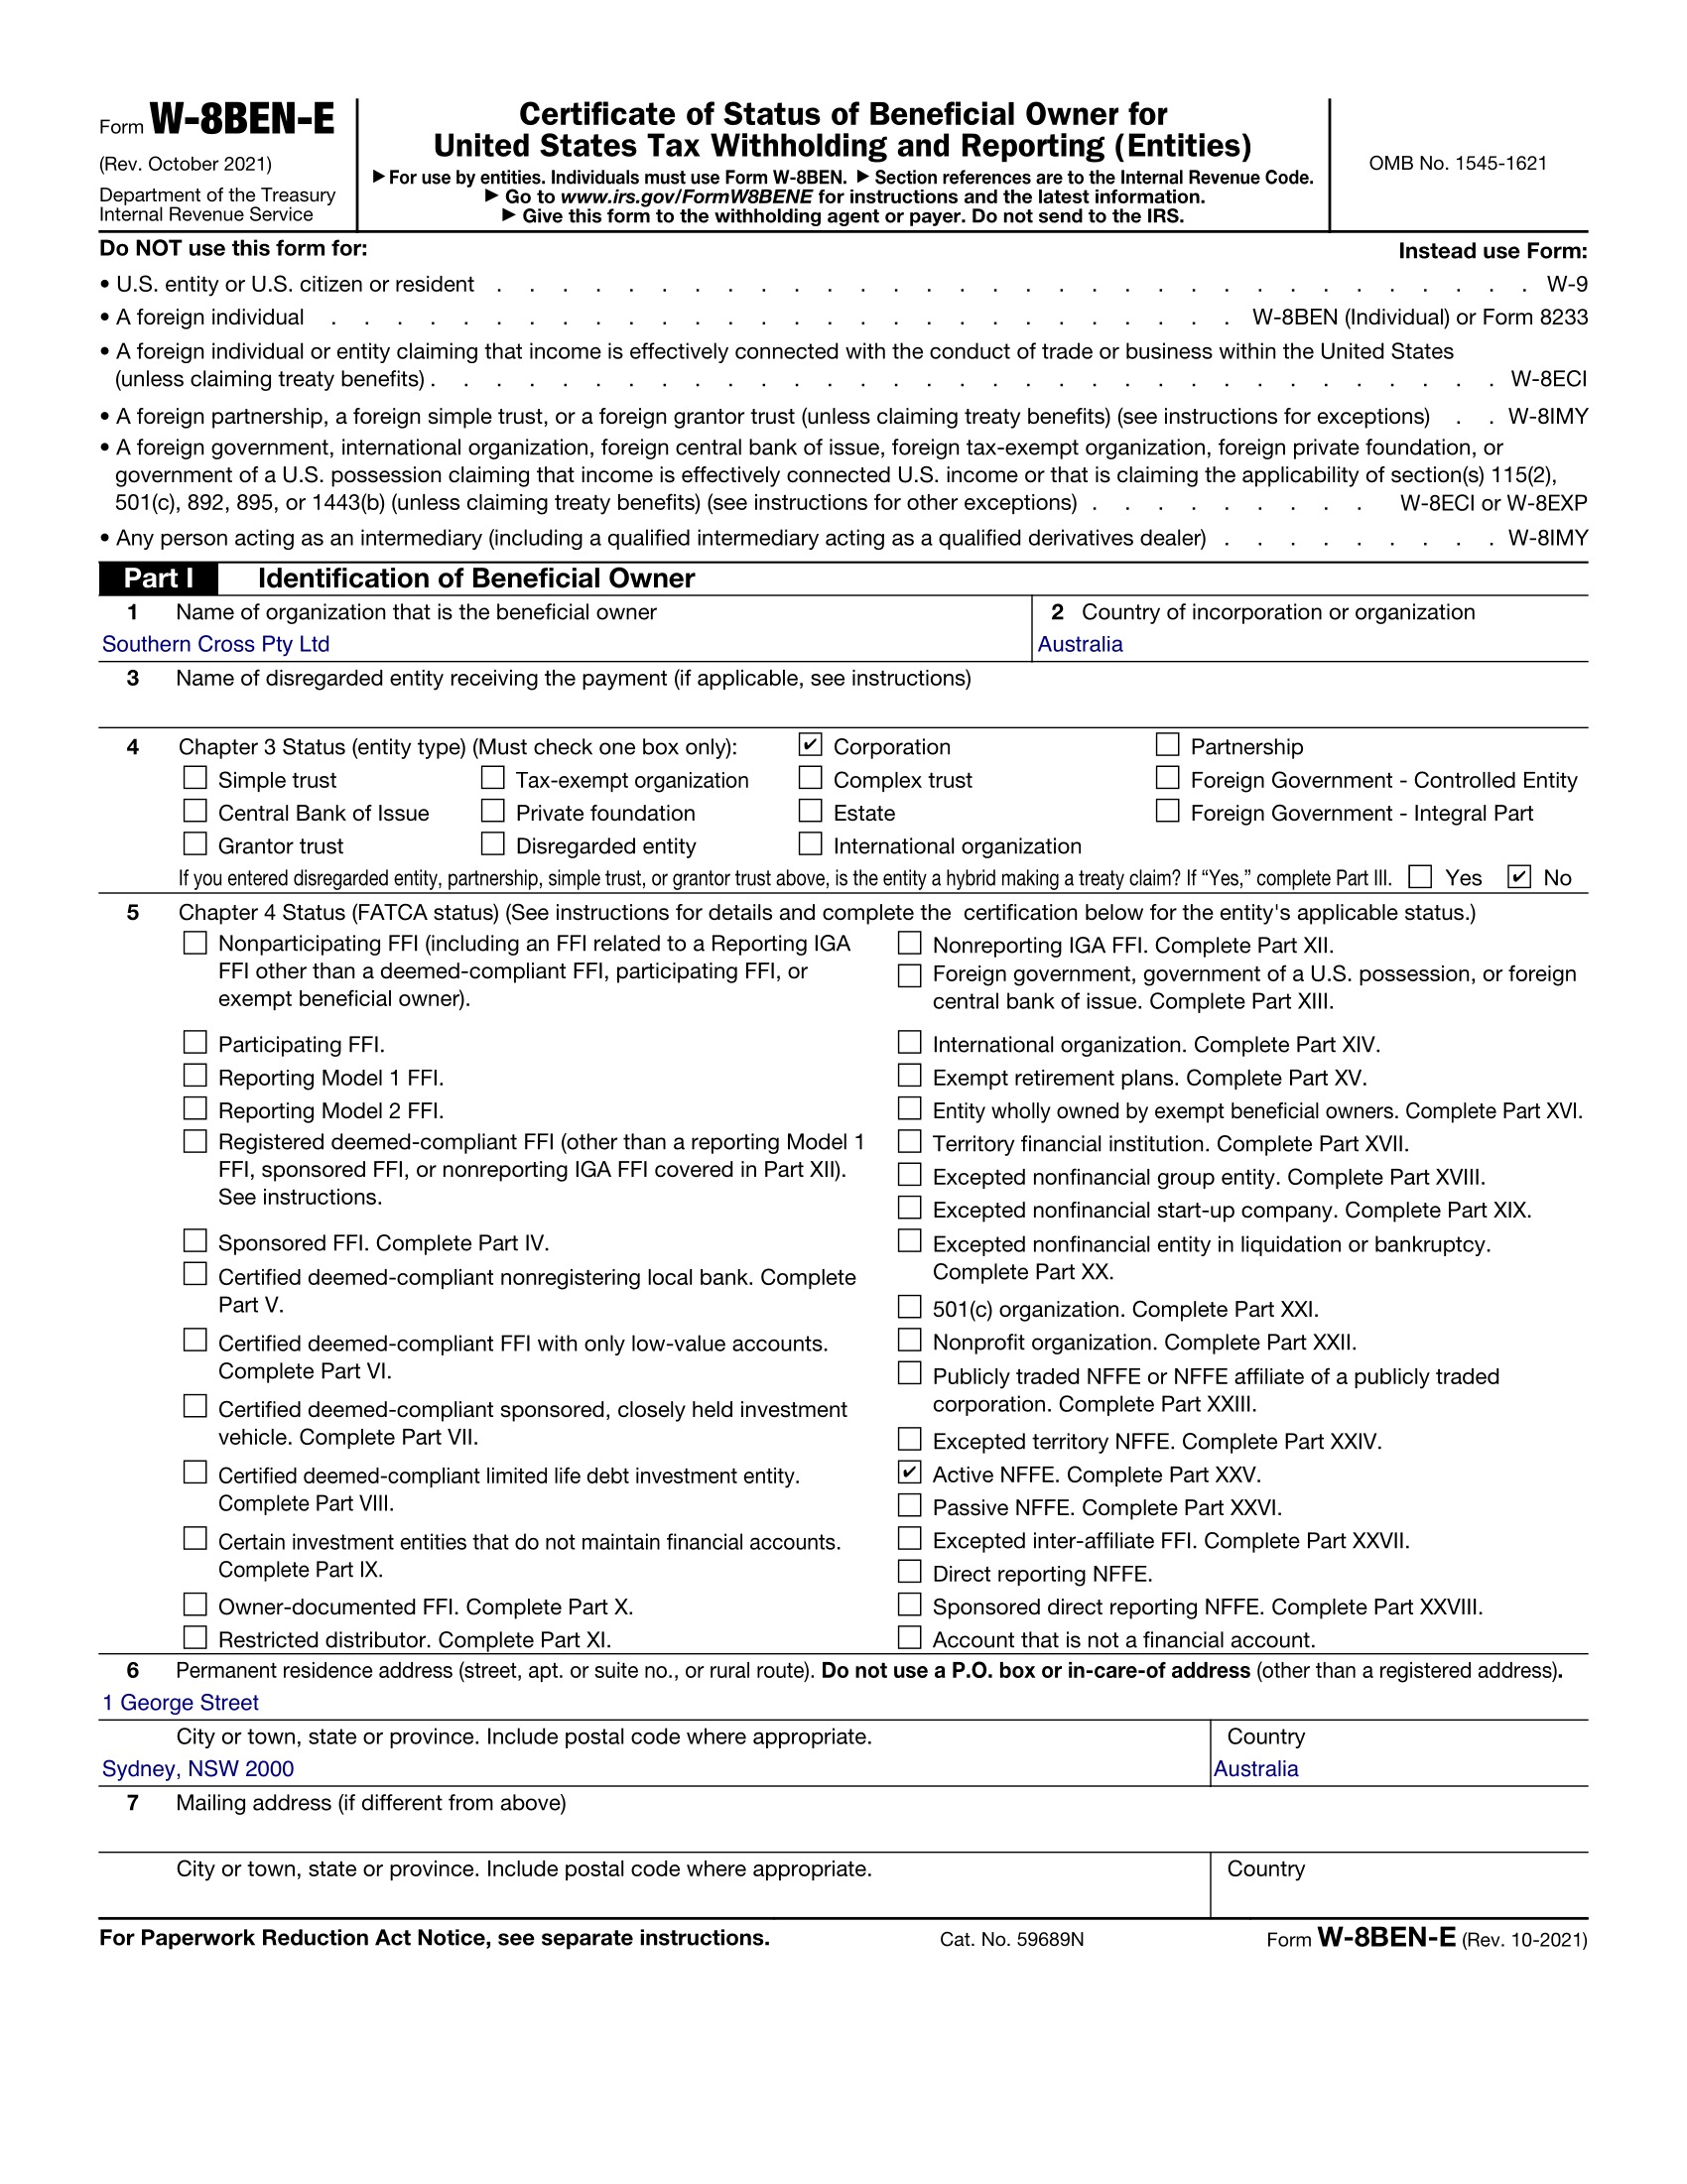
For illustration only — company name, address, director, and ABN are fictional. Example: Southern Cross Pty Ltd, Sydney, ABN 51824753556, Chapter 3 Corporation, FATCA Active NFFE, US-Australia treaty Article 7(1) (Business Profits) 0% for services performed in the United States with no US permanent establishment, Active trade or business.
Treaty rates by income type — after the 2001 Protocol
The commonly linked IRS treaty PDF still shows the original 1982 rates. The figures below are the treaty as amended by the 2001 Protocol:
| Income type | Article | Rate |
|---|---|---|
| Services / consulting / software (Business Profits) | Article 7(1) | 0% only for services performed in the United States when the company has no US permanent establishment; profit attributable to a US permanent establishment gets no 0%. A fee for work performed in Australia is not US-source FDAP, so Part III (lines 14a, 14b and 15) stays blank. |
| Dividends (company holding ≥10% of the payer's voting power) | Article 10(2)(a) | 5% — a lower ownership threshold than the 25%+ seen in many other treaties |
| Dividends (all other ordinary cases, including individuals) | Article 10(2)(b) | 15% — the 1982 text had a flat 15% with no 5% tier; do not cite that version alone |
| Dividends from a US RIC or REIT | Article 10(4) | Never 5% or 0%. A RIC dividend is 15%. A REIT dividend is 15% only for an individual holding not more than 10% of the REIT, a holder of not more than 5% of any class of a publicly traded class, a holder of not more than 10% of a REIT in which no single real property holding exceeds 10% of the gross value of its total real property, or a listed Australian property trust (Article 10(4)(d)); otherwise there is no treaty rate and 30% applies |
| Interest (ordinary) | Article 11(2) | 10% of the gross amount |
| Interest (government body, central bank, or unrelated financial institution) | Article 11(3) | 0% — only for interest derived by a Contracting State, a political or administrative subdivision or local authority, another body exercising governmental functions or a central bank (11(3)(a)), or by a financial institution unrelated to and dealing wholly independently with the payer (11(3)(b)); back-to-back loans stay at 10% (11(4)(a)). Not the typical case for a consulting Pty Ltd |
| Interest determined with reference to the profits of the issuer or of an associated enterprise | Article 11(9)(a) | 15% |
| Royalties (copyright, patents, designs, trademarks, know-how, films and broadcasting tapes) | Article 12(2) | 5% — reduced from the original 1982 rate of 10%. Since the 2001 Protocol, rent for industrial, commercial or scientific equipment is no longer a royalty |
If any source — including the plain IRS treaty PDF or an AI tool that only reads that PDF — cites a flat 15% dividend rate with no 5% tier, or a 10% royalty rate, it is citing the pre-2001 treaty and is out of date. A narrow 0% dividend exception exists under Article 10(3): the company must have owned shares representing 80% or more of the voting power of the US payer for the 12 months ending on the date the dividend is declared and either be a qualified person under Article 16(2)(c) or have a competent-authority determination under Article 16(5) for the dividends. Article 16(2)(c) covers a company whose principal class of shares is listed on the Australian Stock Exchange, another recognized Australian exchange, NASDAQ or a US national securities exchange and regularly traded on recognized exchanges, or one at least 50% of whose aggregate vote and value is owned, directly or indirectly, by five or fewer such companies, each intermediate owner resident in Australia or the United States. The active-trade-or-business test does not open it, and it is not the default for an ordinary small business. Article 16 is the Limitation on Benefits article (lower number than the 22/23/26 seen in some other treaties, but the income articles stay 7/10/11/12/14).
A blog post explaining the form, or the finished PDF right away?
The Australian-specific guides we found are either broker or law-firm notes focused on investors and dividends (Macquarie, Westpac, Perpetual, Mallesons), or generic global guides that still quote the 1982 IRS PDF. Our wizard asks the right questions once and hands you the signature-ready PDF immediately.
| Criterion | Published guides | Our wizard |
|---|---|---|
| What you get | A general explanation, often aimed at investors | The completed, signature-ready PDF itself |
| Pty Ltd vs Public Ltd vs sole trader | Often not distinguished | Explained with the exact default rule, built into the Chapter 3 step |
| ABN vs TFN on Line 9b | Not distinguished — risk of using the wrong identifier | Asks for the company identifier and recommends the public ABN for entities |
| Treaty article & rate (Line 15) | Worked out manually — easy to cite the 1982 PDF | Suggested automatically from the 2001 Protocol facts |
Start the wizard now and get your finished PDF in minutes.
Frequently asked questions about W-8BEN-E for Australian companies
Direct answers to the questions Australian company owners run into most often when filling this in.
Is the US–Australia tax treaty still the 1982 version?
The 1982 Convention is still the base document, but a 2001 Protocol fully replaced the dividends, interest, Limitation on Benefits and other income articles, reduced the royalty rate from 10% to 5%, and took equipment rent out of the royalty definition. Always apply the Protocol's rates, not the original 1982 figures in irs.gov/pub/irs-trty/aus.pdf.
What's the difference between Pty Ltd, Public Ltd, and NL for this form?
Public Ltd and NL always check "Corporation" on Line 4 (they are on the US per se corporation list). A Pty Ltd also defaults to Corporation because its shareholders have limited liability, but it can elect a different classification via Form 8832. A sole trader is not on this form at all.
Should I put my TFN or my ABN on Line 9b?
Your TFN is technically the correct "Foreign TIN," but many Australian businesses provide their ABN instead since it is public rather than confidential. Both are used in practice. Our sample uses the 11-digit ABN. A sole trader still files W-8BEN with their personal TFN.
My sole trader business has an ABN — do I still file the individual form?
Yes. An ABN does not make a sole trader a separate legal entity. File Form W-8BEN using your personal TFN, not Form W-8BEN-E.
Do I need a US EIN, or is the ABN enough?
For most Pty Ltd companies, the ABN (or TFN) is sufficient as the "Foreign TIN" on Line 9b. A US EIN is only needed in specific cases your payer will tell you about.
Which Line 14b box should my company check?
Only when the company claims the treaty — services performed in Australia leave Part III (Lines 14a, 14b and 15) blank. For a typical operating Pty Ltd with a claim, "Active trade or business" (Article 16(3)) is usually the applicable one: an active trade or business in Australia, US income connected with or incidental to it, and substantial in relation to any US business activity of the company or an associated enterprise that gives rise to the income. A company listed on a recognized exchange, or at least 50% owned by five or fewer such listed companies, checks "Publicly traded corporation" or "Subsidiary of a publicly traded corporation" (Article 16(2)(c)). "No LOB Article In Treaty" is not valid — Article 16 exists after the 2001 Protocol.
What's Chapter 4 / Active NFFE?
It's a separate FATCA classification from your entity type. A normal trading company with under 50% passive income and assets is usually "Active NFFE".
What treaty rates typically apply?
Under the US–Australia treaty as amended by the 2001 Protocol: services performed in Australia need no claim, and Part III (Lines 14a, 14b and 15) stays blank; 0% under Article 7(1) only for services performed in the United States when the company has no US permanent establishment there; 5% on dividends where your company directly holds at least 10% of the voting power, 15% otherwise (Article 10(2); RIC and REIT dividends follow Article 10(4)); 10% on ordinary interest (Article 11(2); 0% under Article 11(3) only for interest derived by a government body or central bank, or by a financial institution unrelated to and dealing wholly independently with the payer, and not on back-to-back loans); and 5% on royalties (Article 12(2) — not the pre-2001 10%). Our wizard suggests the right one automatically.
Does the form go to the ATO or the IRS?
No — W-8BEN-E goes only to the US payer (client, platform, or broker), never to the ATO or the IRS directly.
How long is W-8BEN-E valid for?
Generally until the end of the third calendar year after signing — a form signed in 2026 is valid through 31 December 2029, provided none of the underlying details change.
What if my company details change?
A change of name, address, entity type, or ownership structure invalidates the existing form, and a new W-8BEN-E is required regardless of the usual three-year cycle.
I'm a sole trader, not a company — which form do I use?
The shorter W-8BEN, using your personal TFN rather than a company ABN. Work you do in Australia is not US-source, so Part II (Lines 9 and 10) stays blank; pay for personal services you perform in the United States is claimed on Form 8233 under Article 14 (taxable in the United States only if you are present there more than 183 days in the taxable year, or on the part attributable to a fixed base regularly available to you there), not on W-8BEN. This page's line-by-line guidance is for incorporated companies (Pty Ltd, Public Ltd, NL).
Do I need an accountant to complete this?
Not necessarily for standard cases — an ordinary trading Pty Ltd, Active NFFE, common income types can usually be completed with a guided wizard. A holding structure or a complex ownership situation is worth a brief check with an Australian-registered tax agent first.
What does it cost to get W-8BEN-E right?
With our guided wizard, $30 per finished, signature-ready PDF for companies (or $5 for sole traders) — no subscription.
Related guides
For more detail on specific parts of the form:
- Entity type on Line 4 in detail: Full guide to Line 4
- Chapter 3 status in detail: Chapter 3 status guide
- W-8BEN vs W-8BEN-E compared directly: The difference between W-8BEN and W-8BEN-E
- You're a sole trader, not a company: W-8BEN wizard for sole traders ($5)
- South African (Pty) Ltd: W-8BEN-E for a South African (Pty) Ltd
Common mistakes to avoid
- Citing the 1982 IRS treaty PDF alone: irs.gov/pub/irs-trty/aus.pdf does not include the 2001 Protocol. Using it alone produces a flat 15% dividend rate and a 10% royalty rate — both outdated.
- Citing a 10% royalty rate: Article 12 was changed by the Protocol from 10% to 5%. If a source still says 10%, it is reading the pre-2001 text.
- Treating a sole trader's ABN as proof it is a company: An ABN does not make a sole trader a separate entity. They file W-8BEN, not W-8BEN-E.
- Assuming the TFN length tells you entity vs individual: The TFN is 9 digits for both. The practical distinction is the ABN (11 digits, public, typical for a Pty Ltd) on Line 9b versus the individual's 9-digit TFN, which goes on Line 6a of Form W-8BEN.
- Citing Article 14 for a Pty Ltd: Article 14 is Independent Personal Services for individuals, claimed on Form 8233 for work performed in the United States. An entity cites Article 7(1) (Business Profits) only for services performed in the United States when it has no US permanent establishment there; services performed in Australia leave Part III (Lines 14a, 14b and 15) blank.
- Checking "No LOB Article In Treaty" on Line 14b: Article 16 exists after the 2001 Protocol. When the company claims the treaty, an ordinary trading Pty Ltd typically uses the active-trade-or-business test of Article 16(3).
- Claiming 5% on equipment rent: The 2001 Protocol took industrial, commercial and scientific equipment out of the Article 12 royalty definition. Rent from a lease that is part of the company's trade is business profits under Article 7(1): 0% only when the company has no US permanent establishment and no business activity in the United States — and substantial equipment kept in the United States for more than 12 months (other than equipment let under a hire-purchase agreement) is itself a permanent establishment (Article 5(4)(b)). A passive lease is other income, which Article 21(3) lets the United States also tax, so it has no treaty rate.
A quick note on Australian company tax
This page focuses entirely on US withholding tax — the reason your company needs to fill in W-8BEN-E at all. It doesn't cover Australia's own tax treatment of that income. The standard company tax rate is 30%, or 25% for eligible base-rate entities (generally smaller companies with turnover under a threshold and mostly active income).
How that income is actually taxed once it reaches your Australian company is a question for a licensed Australian tax agent, not something this page — or our wizard — determines for you. W-8BEN-E only affects what a US payer withholds at source; it has no bearing on how Australia taxes your company's profits.
- Company tax rate: 30% standard, 25% for eligible base-rate entities.
- GST: 10%, generally not relevant to the US W-8BEN-E itself.
Ready to finish your own W-8BEN-E instead of reading more guides?
The guided wizard asks the same questions covered on this page — directly inside your own form, with the treaty article and rate suggested automatically from the 2001 Protocol.