W-8BEN-E for a Norwegian AS (and W-8BEN for an ENK): US–Norway Treaty Guide (2026)
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Last checked: 30.10.2026 against the 1971 US–Norway convention (irs.gov/pub/irs-trty/norway.pdf) and the 1980 protocol (irs.gov/pub/irs-trty/norway-1980-protocol.pdf). Signed at Oslo on December 3, 1971, in force November 29, 1972. The protocol was signed September 19, 1980. Article 9(1) in the consolidated PDF says either State. The protocol says the other State. This page follows the protocol.
 AI-generated image
Most W-8BEN-E guides assume modern article numbers: 7 for business profits, 10 for dividends, 12 for royalties. The US–Norway treaty is from 1971: industrial or commercial profits of a company are Article 5, dividends are Article 8, and royalties are Article 10.
This guide is for a private aksjeselskap (AS) that invoices US clients, licenses software, or holds US stocks, and for an enkeltpersonforetak (ENK). It covers which form you file, why an AS is not an ASA, and which number goes on the tax line. Work an AS does in Norway is not US-source income: there is no US withholding to reduce, and Part III of Form W-8BEN-E (Lines 14a, 14b and 15) stays blank. The filled sample PDF further down shows the other case: developers of the AS performing services on site in the United States, with no US permanent establishment, which claims Article 5(1) at 0%.
An ENK is a person who carries on business under personal liability. That person files Form W-8BEN, not Form W-8BEN-E: start the W-8BEN wizard. Work done in Norway is not US-source income, so Part II of Form W-8BEN (Lines 9 and 10) stays blank. Pay for personal services the person performs in the United States goes on Form 8233, not Form W-8BEN, under Article 13. An NUF (norskregistrert utenlandsk foretak) is the Norwegian branch of a foreign company. The foreign company files Form W-8BEN-E under its own country's treaty, not the US–Norway treaty.
If you prefer to skip the reading, start the W-8BEN-E wizard. For services an AS performs in Norway it leaves Part III blank. For services its staff perform in the United States with no US permanent establishment it cites Article 5(1) at 0%, and Line 14b is Other: Holding company test, Article 20. A signature-ready PDF is $30. Form W-8BEN for a person is $5.
Blank form or already filled in?
You can download the official blank form from the IRS, or get the same file already filled in.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for an AS or an ASA.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for an ENK.
- Already filled in (5–10 minutes): W-8BEN-E for a Norwegian AS ($30) or W-8BEN for an ENK ($5).
- The convention: US–Norway Income Tax Treaty PDF on IRS.gov — signed December 3, 1971. Industrial or commercial profits of a company are Article 5, not Article 7.
- The 1980 protocol: norway-1980-protocol.pdf — Article 9(1) says the other State. Dividends are 15% at any ownership.
AS, ASA, ANS, or an ENK?
26 CFR 301.7701-2(b)(8)(i) lists Norway, Allment Aksjeselskap. US classification does not follow the local abbreviation one-for-one:
- Allmennaksjeselskap (ASA): A public limited company. It is a per se corporation from November 29, 1999, and it cannot file Form 8832. There is no ownership-change grandfather.
- Aksjeselskap (AS): The usual private company. An AS is not on the per se list — only ASA is. It defaults to Corporation because the members have limited liability. A different US classification is Form 8832. A single-member AS is not disregarded by default.
- Ansvarlig selskap (ANS), delt ansvar (DA), or kommandittselskap (KS): These default to Partnership. They are fiscally transparent in Norway. Treaty residence follows the partners to the extent the income is taxed in Norway as income of a resident.
- Enkeltpersonforetak (ENK): A person, not a company. That person files Form W-8BEN. Work done in Norway leaves Part II (Lines 9 and 10) blank; pay for personal services performed in the United States goes on Form 8233, under Article 13.
- Norskregistrert utenlandsk foretak (NUF): Not a Norwegian entity for treaty purposes. The foreign parent files its own Form W-8BEN-E under that parent's treaty.
Chapter 3 still decides which form you file. Part III is where the article and the rate go, and only when the company claims the treaty. On Line 14b check Other and write "Holding company test, Article 20". IRS Tax Treaty Table 4 lists Article 20 under Other. It denies dividend, interest, royalty, and gains rates only when both special low-tax measures and the 25% test are met: 25% or more of the capital is held of record by one or more persons who are not individual residents of Norway (companies included), or by citizens of the United States. Indirect ownership counts only after the competent authorities so determine. Business profits are not affected.
Article 20 and a holdingselskap
A Norwegian corporation is not entitled to Article 8, Article 9, Article 10, or Article 12 for US dividends, interest, royalties, or gains when both conditions are met. (a) Because of special measures, the Norwegian tax on that income is substantially less than the tax generally imposed on corporate profits. (b) 25% or more of its capital is held of record by one or more persons who are not individual residents of Norway. Citizens of the United States also count toward that 25% when the corporation is Norwegian. Capital owned directly or indirectly counts toward the 25% only after consultation between the competent authorities of the United States and Norway.
An AS whose capital is held of record, 100%, by a personal holding AS meets condition (b). That holding AS is the owner of record and is not an individual resident of Norway. Whether the participation exemption (fritaksmetoden) is a special measure under condition (a) is not settled on this page. Confirm that with a tax advisor. This page does not assert either way.
Line 9b and Part III
Norway uses two different numbers. Do not add the MVA suffix on either form. Part III (Lines 14a, 14b and 15) stays blank for services an AS performs in Norway; it is filled only when the company claims the treaty, for example for services performed in the United States, dividends, interest or royalties.
| Line | What you enter |
|---|---|
| Line 9b of Form W-8BEN-E | The 9-digit organisasjonsnummer, for example 923456783. Weights 3, 2, 7, 6, 5, 4, 3, 2, 1, and the weighted sum mod 11 is 0. 923456783 passes. 988077917 passes. Do not add the MVA suffix. |
| Foreign TIN on Form W-8BEN | The 11-digit fødselsnummer or D-nummer of the person, for example 01018512366. 01018512366 passes. 12345678901 fails. 15108695088 passes. The ENK organisasjonsnummer does not replace the fødselsnummer on Form W-8BEN. |
| Line 14a | Only when the company claims the treaty: Norway. Blank for services performed in Norway. |
| Line 14b | Only when the company claims the treaty: check Other and write "Holding company test, Article 20". |
| Line 15 | Only when the company claims the treaty; blank for services performed in Norway. For services the AS's staff perform in the United States: Article 5(1), 0%, when the AS has no permanent establishment in the United States. Do not cite Article 7. |
Read the organisasjonsnummer from the Brønnøysund register before Line 9b. Do not invent a 9-digit string that fails the check digit.
Sample: completed W-8BEN-E for a Norwegian AS
A filled example of the claim case: a fictional AS in Oslo whose developers perform services on site in the United States, with no US office, dependent agent or other permanent establishment there. Chapter 3 Corporation, Line 14b Other: Holding company test, Article 20, Line 15 Article 5(1) at 0%. Services performed only in Norway would leave Part III blank.
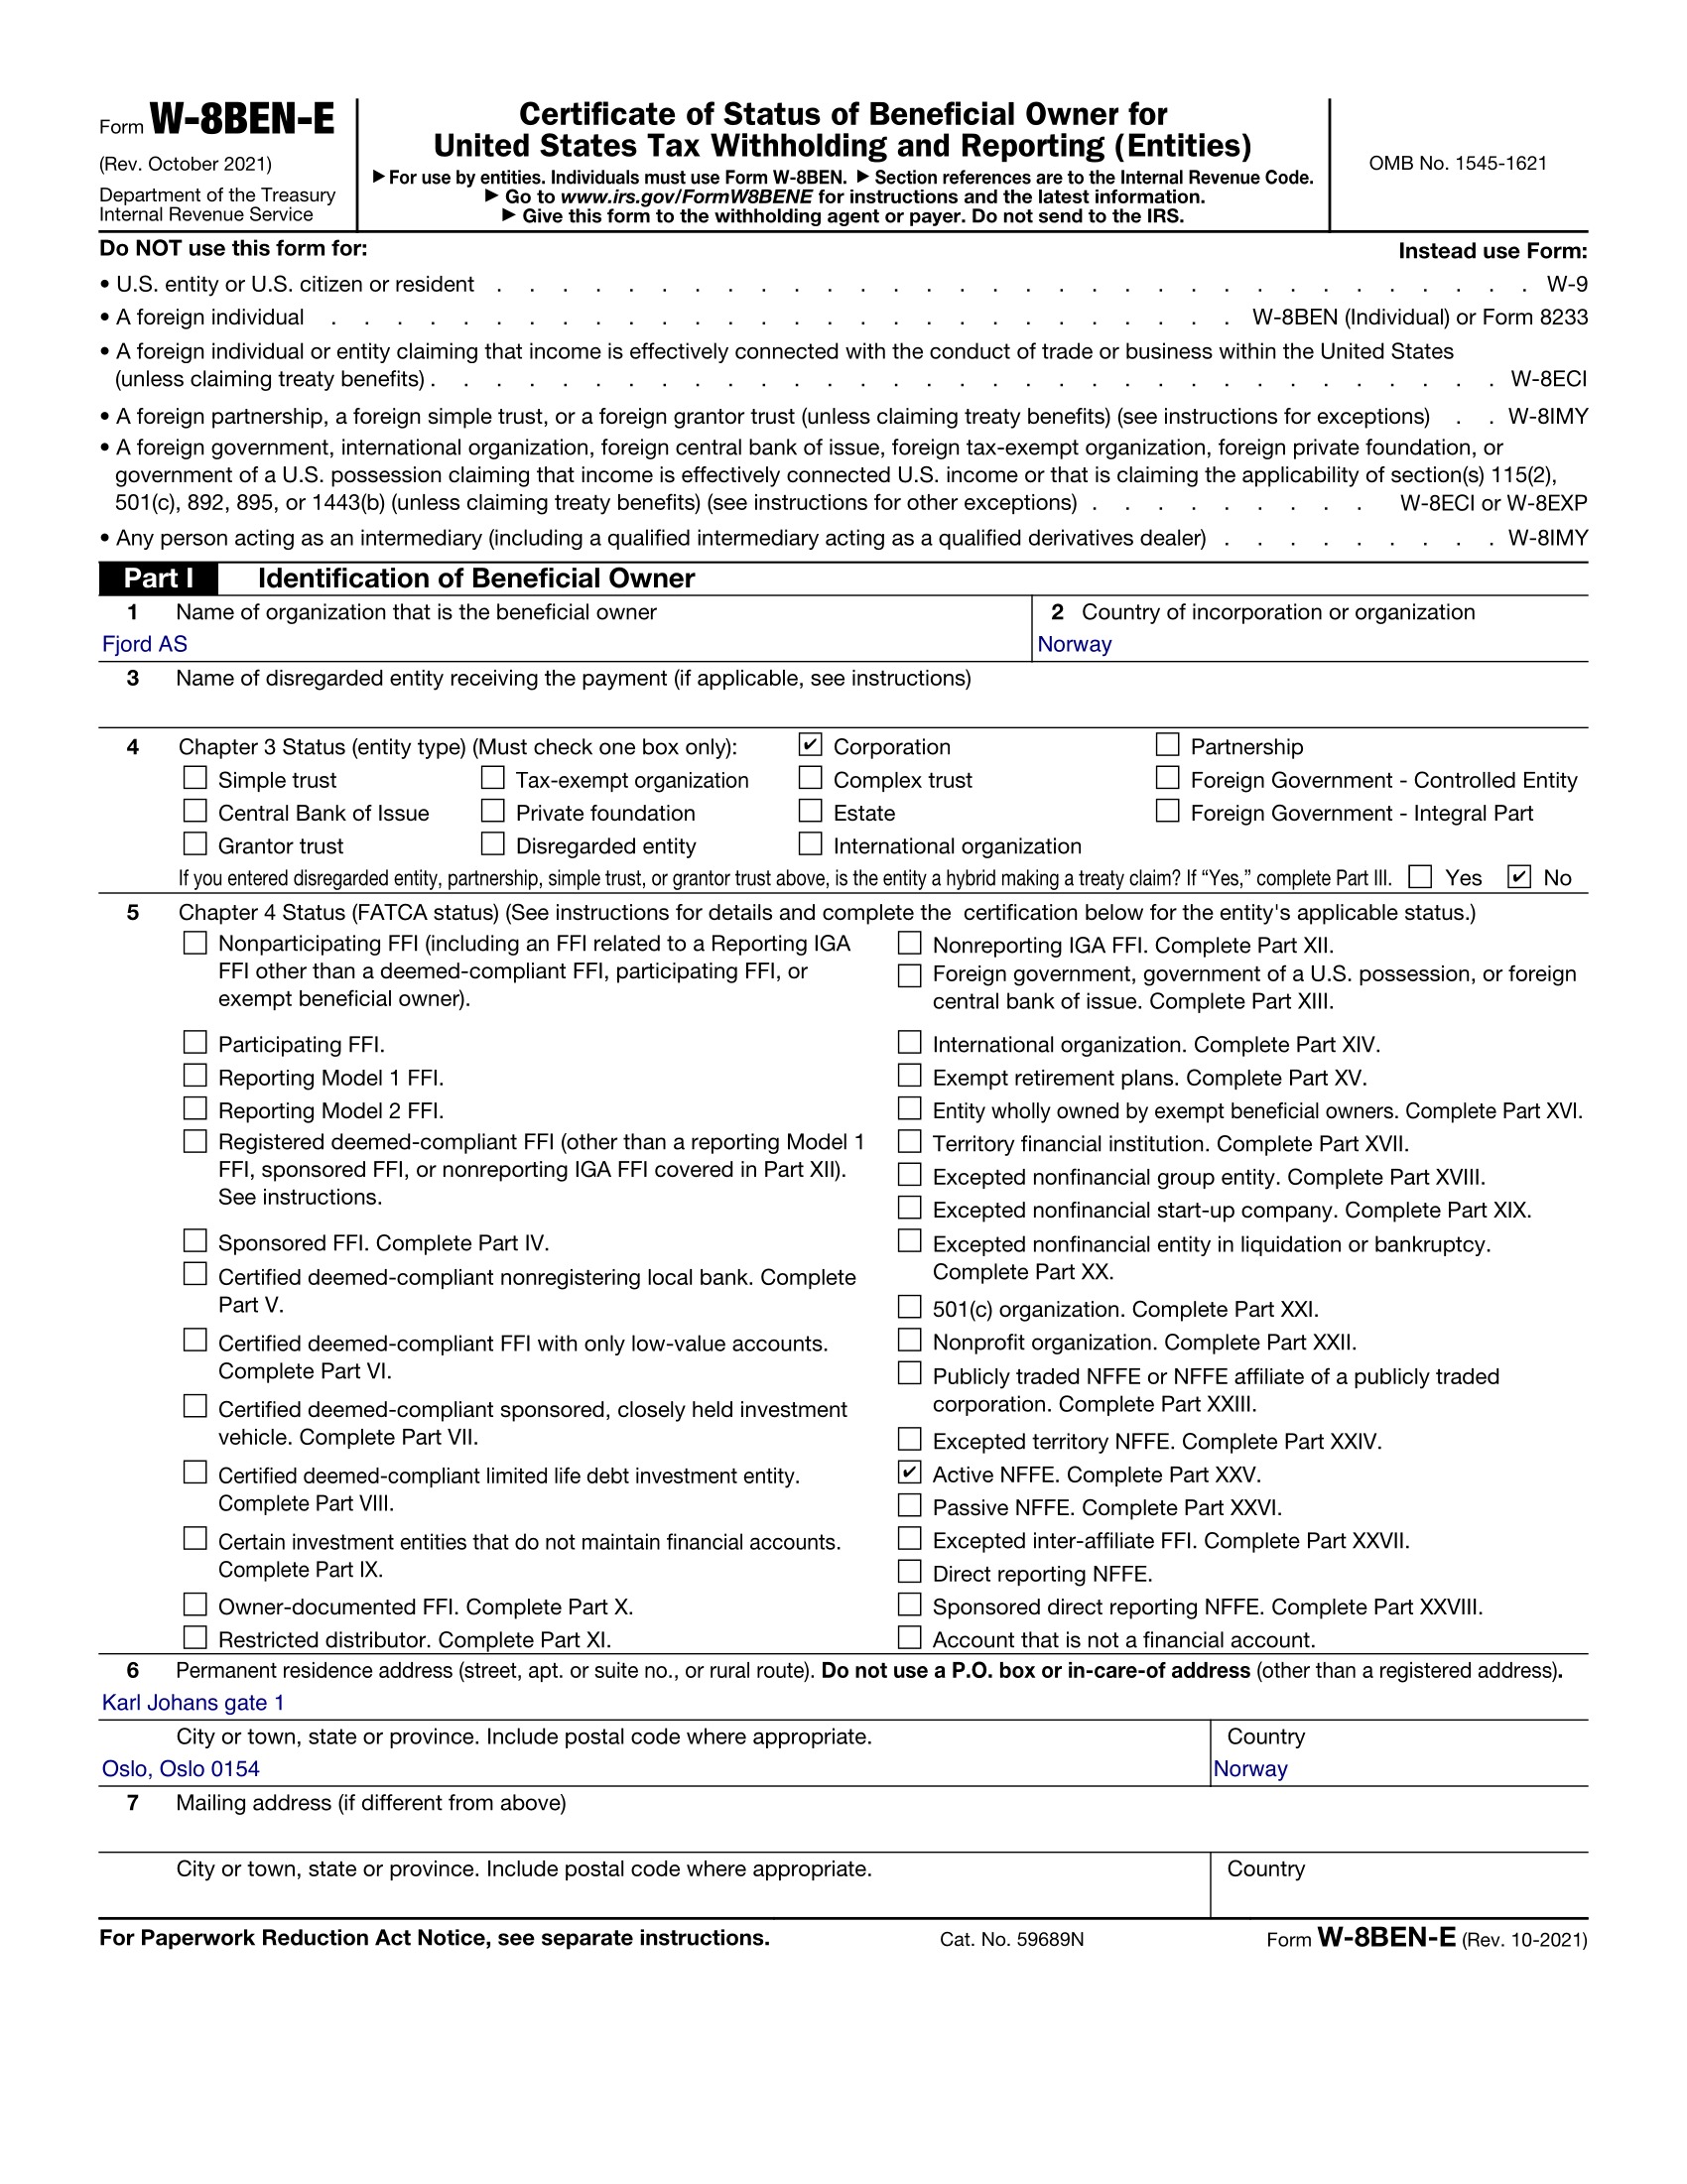
Sample only. Fjord AS, Karl Johans gate 1, Oslo 0154, Norway, organisasjonsnummer 923456783, Chapter 3 Corporation, FATCA Active NFFE, Article 5(1) at 0% for services performed in the United States with no US permanent establishment, Line 14b Other: Holding company test, Article 20.
What happens to the income
Each row stands on its own. Do not move a rate onto the neighbouring row. Do not cite Article 7 for services, Article 10 for dividends, or Article 12 for royalties.
| Income | Article | Rate and condition |
|---|---|---|
| Services an AS performs in Norway | None | No US withholding: the income is not US-source. Part III (Lines 14a, 14b and 15) stays blank. |
| Services of an AS performed in the United States | Article 5(1) | 0% under Article 5(1) — only if the AS has no permanent establishment in the US. A construction or installation project is a permanent establishment only after 12 months. Offshore activities in connection with the exploration or exploitation of the seabed and subsoil are a permanent establishment once they run more than 30 days in any 12-month period (Article 4A). Otherwise the United States may tax the profits attributable to that permanent establishment. |
| Services of an ENK or freelancer | Article 13(1) | Work done in Norway: Part II (Lines 9 and 10) stays blank. Pay for personal services performed in the United States goes on Form 8233, under Article 13: exempt if you are in the US fewer than 183 days in the tax year and have no US fixed base for 183 days or more; a public entertainer or athlete also needs not more than 90 days and not more than USD 10,000 of such income in the tax year. Otherwise the US may tax the income from services you perform in the US; for a fixed base, only the income attributable to it. |
| Software licence, patents, trademarks, know-how | Article 10(1) | 0% — copyrights of literary, artistic or scientific works, including a software licence, plus patents, designs, trademarks, and know-how. Any amount above arm's length between related parties is not covered. |
| Film or TV rights | Article 5(1) | 0% under Article 5(1) — only when the licence income is not attributable to a US permanent establishment; the wizard asks you to confirm that. The rental or licensing of motion picture films or films or tapes for radio or television broadcasting is industrial or commercial activity under Article 5(5), not royalties under Article 10. |
| Equipment rental | Article 5(1) | 0% under Article 5(1) — only with no US permanent establishment and no US activity for the lease, for an AS or an ENK. A lessor with activity in the United States, with or without a permanent establishment there, makes no claim for that rent: Part III (Lines 14a, 14b and 15) of Form W-8BEN-E, or Part II (Lines 9 and 10) of Form W-8BEN, stays blank. A dependent agent that maintains substantial equipment or machinery in the United States for more than twelve months is itself a permanent establishment (Article 4(4)(b)). The rental of tangible personal property is industrial or commercial activity under Article 5(5), not royalties under Article 10. |
| Interest | Article 9(1) | 0% under Article 9(1) in any calendar year in which Norway exempts similar interest from Norwegian sources under its own law; IRS Tax Treaty Table 1 lists 0% on that basis. In a year in which it does not, Article 9(2) caps the US tax at 10%, and Article 9(3) still exempts in all events interest owned or paid by a Contracting State, a political subdivision or local authority, or an instrumentality not taxed by that State; interest owned by a resident of a Contracting State on debt guaranteed or insured by that same State (or its political subdivision, local authority or untaxed instrumentality); interest a purchaser pays a seller on a commercial credit for deferred payments for goods, merchandise or services; interest on a loan of any nature made by a bank; and interest on an obligation outstanding on September 19, 1980. Article 9(1) follows the 1980 protocol: the other State, not the consolidated either State. |
| Dividends from US companies | Article 8(2) | 15% — at any ownership percentage. There is no 5% rate and no 10% direct-investment rate in this treaty. The protocol deleted the earlier corporate dividend rate. |
| Dividends, interest, or royalties of certain holding companies | Article 20 | No treaty rate when special measures cut the Norwegian tax on that income substantially AND 25% or more of the capital is held of record by persons who are not individual residents of Norway. Citizens of the United States also count toward that 25% for a Norwegian corporation. Direct or indirect ownership counts only after consultation between the competent authorities. Check with an advisor. On Line 14b it is the Other box, "Holding company test, Article 20", when the company claims the treaty. |
Form W-8BEN-E does not invent a modern article number. An AS whose staff perform services in the United States with no US permanent establishment writes Article 5(1). Article 7 of this treaty is Related Persons. For work done in Norway, Part III stays blank.
Questions people ask before they sign
Short answers for an AS or an ENK. A fund or a bank needs an accountant, not this page.
Why not Article 7?
Article 7 of the 1971 convention is Related Persons. Industrial or commercial profits of a company are Article 5. Independent personal services of an individual are Article 13, claimed on Form 8233 for work performed in the United States. Do not copy Article 7 from a modern treaty.
Is my AS a per se corporation?
No. Only an ASA is on the per se list, from November 29, 1999, with no ownership-change grandfather. An AS defaults to Corporation and can file Form 8832.
What rate on US dividends in my AS?
Article 8(2) is 15% at any ownership percentage. There is no 5% or 10% direct-investment rate. Article 20 may deny even the 15% when both conditions are met. Condition (b) counts capital held of record, and citizens of the United States count toward the 25% for a Norwegian corporation. Indirect ownership counts only after consultation between the competent authorities. Ask a tax advisor before you rely on 15% for a holdingselskap.
YouTube or AdSense for an ENK?
Both qualifications in this treaty can be 0%. As a copyright royalty, Article 10(1) is 0%. As a right in a film or a tape for broadcasting, Article 5(1) is 0% when the income is not attributable to a US permanent establishment. Which article Google writes depends on Google's qualification. This page does not pick one for Google. Website AdSense earned from work done in Norway is not a royalty and not US-source: Part II (Lines 9 and 10) of Form W-8BEN stays blank.
I work from Norway for a US client — any US tax?
No. Services performed in Norway are not US-source, so there is no US withholding to reduce. An AS leaves Part III (Lines 14a, 14b and 15) of Form W-8BEN-E blank, and an ENK leaves Part II (Lines 9 and 10) of Form W-8BEN blank. Article 5(1) at 0% is for services an AS's staff perform in the United States with no US permanent establishment; an ENK's pay for work in the United States goes on Form 8233.
What to do next
- Fill out W-8BEN-E in the guided wizard: Start the W-8BEN-E wizard ($30). For services an AS's staff perform in the United States with no US permanent establishment it uses Article 5(1) at 0% and Line 14b Other: Holding company test, Article 20; for work done in Norway it leaves Part III blank.
- Are you an ENK?: Use the W-8BEN wizard ($5). Work done in Norway leaves Part II blank; pay for personal services performed in the United States goes on Form 8233.
Mistakes that get the form sent back
- Article 7, 10, or 12 from a modern treaty: On this treaty those numbers are Related Persons, Royalties, and Capital Gains. Industrial or commercial profits of an AS are Article 5. Dividends are Article 8.
- Article 5(1) for services performed in Norway: That income is not US-source. Part III (Lines 14a, 14b and 15) stays blank. Article 5(1) at 0% is for services performed in the United States with no US permanent establishment.
- Article 13 on Form W-8BEN: Work done in Norway leaves Part II (Lines 9 and 10) blank; pay for personal services performed in the United States goes on Form 8233, under Article 13.
- 5% on dividends: Article 8(2) is 15% at any ownership percentage. There is no 5% rate and no 10% direct-investment rate.
- Treating an AS as per se: Only an ASA is on the per se list, from November 29, 1999. An AS can file Form 8832.
- Form W-8BEN-E from an ENK: An enkeltpersonforetak files Form W-8BEN.
- Fødselsnummer on Line 9b of Form W-8BEN-E: The company enters the 9-digit organisasjonsnummer, for example 923456783. The person enters 01018512366 on Form W-8BEN.
- Form W-8BEN-E from an NUF under the US–Norway treaty: The foreign parent files under its own country's treaty.