W-8BEN-E for an Albanian SH.P.K. and W-8BEN for a Self-Employed Professional: No US–Albania Tax Treaty (2026)
This article was created with AI assistance and has not been reviewed by a human editor. It is provided for general informational purposes only and does not constitute tax, legal, or financial advice.
Last checked: 29.09.2026. Albania does not appear on the IRS United States Income Tax Treaties - A to Z list. The United States is not among Albania's treaty partners. PwC lists 42 Albanian treaties in force, and the United States is not one of them. The 1995 US–Albania bilateral investment treaty is not an income tax treaty and does not reduce withholding.
 AI-generated image
There is no US–Albania income tax treaty. The 1995 US–Albania investment treaty protects investors; it does not reduce US withholding. For services you perform from Albania, that usually changes nothing: the income is not US-source.
This guide is for a shoqëri me përgjegjësi të kufizuar (SH.P.K.) that invoices US clients, licenses software, or holds US stocks, and for a person fizik, including a profesionist i lirë. It covers which form you file, what stays blank, and which 10-character number goes on the tax line. A sample PDF is included further down.
A person fizik is a person, not a company. A NIPT does not make that person a company. That person files Form W-8BEN, not Form W-8BEN-E: start the W-8BEN wizard. A branch of a foreign company is not an Albanian resident. The foreign company files its own form.
If you prefer to skip the reading, start the W-8BEN-E wizard. It already knows Albania has no US income tax treaty and, by default, leaves Part III (Lines 14–15) blank. A signature-ready PDF is $30. Form W-8BEN for a person is $5.
Blank form or already filled in?
You can download the official blank form from the IRS, or get the same file already filled in.
- Blank official W-8BEN-E (IRS, free): Download W-8BEN-E as a PDF directly from the IRS — for an SH.P.K. or an SH.A.
- Blank official W-8BEN (IRS, free): Download W-8BEN as a PDF directly from the IRS — for a person fizik.
- Already filled in (5–10 minutes): W-8BEN-E for an Albanian SH.P.K. ($30) or W-8BEN for a self-employed professional ($5) — Part III and Part II stay blank.
- IRS treaty list: United States Income Tax Treaties - A to Z — Albania does not appear.
- PwC withholding summary: Albania – Corporate – Withholding taxes — the United States is not among the treaty partners.
SH.P.K., SH.A., or a person fizik?
Albania is not on the per se list in 26 CFR 301.7701-2(b)(8)(i). US classification does not follow the local abbreviation one-for-one:
- Shoqëri me përgjegjësi të kufizuar (SH.P.K.): The usual private company. Albania is not on the US per se corporation list. An SH.P.K. defaults to Corporation. A different classification is Form 8832. A single-member SH.P.K. is not disregarded by default.
- Shoqëri aksionare (SH.A.): The joint-stock company. Albania is not on the US per se corporation list. An SH.A. defaults to Corporation and can file Form 8832.
- Shoqëri kolektive or shoqëri komandite: These default to Partnership.
- Person fizik: A person, including a profesionist i lirë. A person fizik files Form W-8BEN, even with a NIPT.
- Degë e shoqërisë së huaj: A branch of a foreign company. It is not an Albanian resident. The foreign company files its own form.
Chapter 3 still decides which form you file. Part III is where a treaty claim would go. Today that part stays blank, because there is no treaty to cite.
Relocated to Albania?
Treaty benefits follow tax residence, not citizenship. If you are a tax resident of Albania, the treaty of your country of citizenship does not apply. An Italian citizen who is a tax resident of Albania cannot use the US–Italy treaty. If you are still a tax resident of another country, use that country's treaty.
- Tax resident of Albania: Part II of Form W-8BEN and Part III of Form W-8BEN-E stay blank. There is no US–Albania treaty to cite.
- Citizenship alone: A passport does not choose the treaty once tax residence is in Albania.
What to write, and what to leave blank
On Form W-8BEN-E, Part III (Lines 14–15, Claim of Tax Treaty Benefits) stays blank. Do not enter an article number or a rate. Line 14b is not filled in. Part II (Lines 11–13) is a different section — a disregarded entity or a branch receiving the payment — and also stays blank for an ordinary SH.P.K. On Form W-8BEN, Part II (Claim of Tax Treaty Benefits) stays blank for the same reason. The 1995 investment treaty does not fill those lines.
Income from services performed from Albania, the common case for an SH.P.K. or a person fizik invoicing a US client remotely or through Upwork or Toptal, is foreign-source and is not subject to US withholding at all. Services performed while you are physically in the United States are US-source. No treaty exemption is available for that income. Genuine US-source income is different again: a software licence fee for IP used in the United States, ad revenue attributed to US viewers, dividends on US stock, and interest on US instruments stay at the full 30% statutory rate. The portfolio interest exemption is a separate domestic rule. Ask an accountant. Do not treat it as automatic.
Line 9b, NIPT and NID
A company and a person use the same 10-character shape, and different labels.
| Line | What you enter |
|---|---|
| Line 9b of Form W-8BEN-E | The 10-character NIPT (NUIS) from the QKB registration, for example L81315001A. That example shows the format: a letter, 8 digits, and a letter. Do not add the AL prefix. This page does not verify the check letter. |
| Foreign TIN on Form W-8BEN | The 10-character NID (numri personal) from the Albanian ID card, for example I50101001A. That example shows the format. This page does not verify the check letter. A self-employed person may use a NIPT of the same shape instead. |
| Line 14b and Line 15 | LEAVE BLANK. There is no US income tax treaty with Albania, so there is no treaty country and no article or rate. Line 14b is not filled in. The 1995 investment treaty does not go here. |
| Part II of Form W-8BEN | LEAVE BLANK. A person fizik who is a tax resident of Albania does not claim a treaty benefit. |
| State or Province | Tirana, when that is the place. The city does not create a US treaty. |
Read the NIPT from the QKB extract before Line 9b. L81315001A is 10 characters and is a format illustration. The check letter is not verifiable.
Sample: completed W-8BEN-E for an Albanian SH.P.K.
A filled example for a fictional SH.P.K. in Tirana, Chapter 3 Corporation, with Part III left blank because Albania has no US income tax treaty.
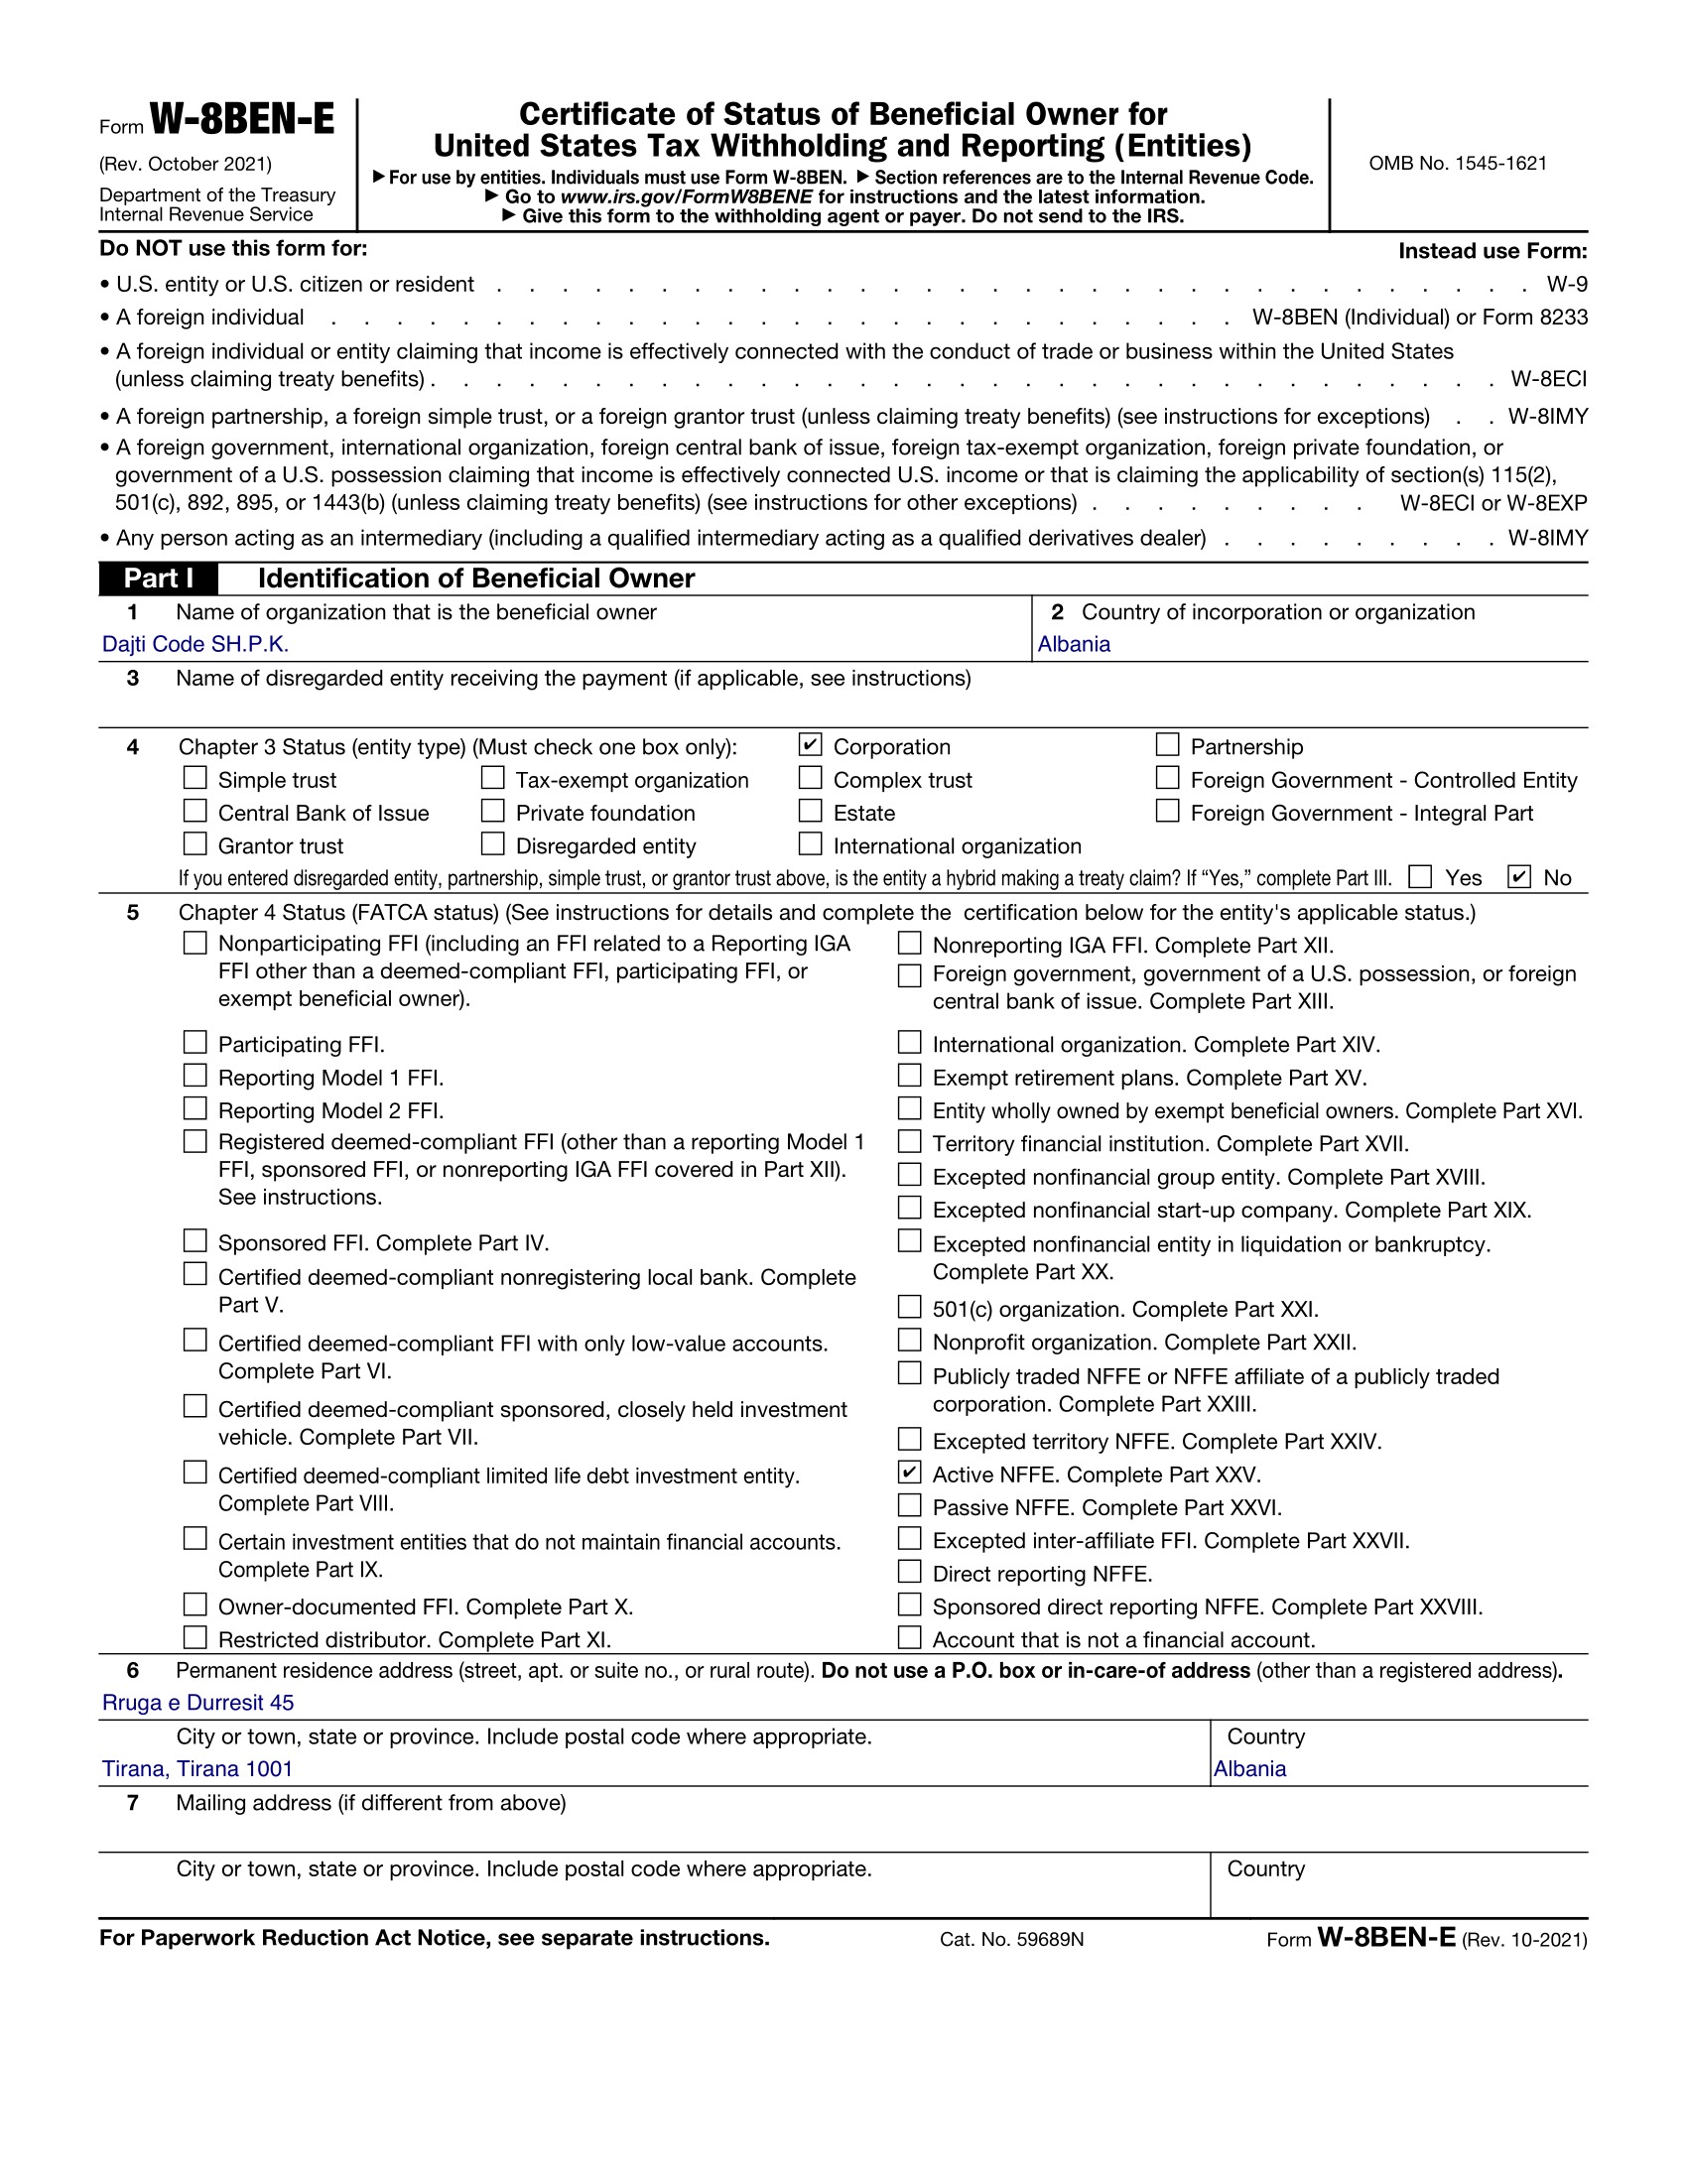
Sample only. Dajti Code SH.P.K., Rruga e Durresit 45, Tirana 1001, NIPT L81315001A, Chapter 3 Corporation, Active NFFE, Part III blank. The street on the form is stored without the letter ë.
What happens to the income
Each row stands on its own. Do not move a rate onto the neighbouring row. There is no treaty rate to copy from a treaty Albania has with another country, and the 1995 investment treaty is not a rate.
| Income | US withholding | Why |
|---|---|---|
| Services performed from Albania (Upwork, Toptal, direct clients) | 0%. Services performed from Albania are foreign-source income, so they are not US-source income. | The work is performed from Albania. US withholding does not apply to that foreign-source income. |
| Services performed while physically in the United States | May be taxed in the United States. Services performed while physically in the United States are US-source, and no treaty exemption is available. | Physical performance in the United States makes the income US-source. Albania has no treaty exemption for it. |
| Software licence fees and royalties for IP used in the United States | 30%. A software licence fee or other royalty for IP used in the United States is US-source, and there is no treaty rate. | The IP is used in the United States. The statutory rate is 30%. |
| AdSense or YouTube revenue attributed to US viewers | 30% on the US portion. Ad revenue attributed to US viewers is US-source royalty-type income, and there is no treaty rate. | Only the portion attributed to US viewers is US-source. That portion is 30%. |
| Dividends from US stocks | 30%. Dividends from US stocks have no treaty rate, at any ownership percentage. | There is no US–Albania dividends treaty provision. The statutory rate is 30%. |
| Interest from US sources | 30% unless a US domestic exemption applies. Ask an accountant. It is not automatic. | Interest from US sources is US-source. A domestic exemption is separate from a treaty and is a question for an accountant. |
Form W-8BEN-E does not create a treaty rate. It shows the payer that the company is foreign, so foreign-source service fees performed from Albania are not withheld by mistake.
Questions people ask before they sign
Short answers for an SH.P.K. or a person fizik. A fund or a bank needs an accountant, not this page.
Does the US–Albania investment treaty reduce withholding?
No. The 1995 bilateral investment treaty protects investors. It is not an income tax treaty and it does not reduce a rate.
I'm a profesionist i lirë with a NIPT — W-8BEN or W-8BEN-E?
Form W-8BEN. A person fizik is a person, not an SH.P.K. A NIPT does not change the form.
Which number: NIPT or NID?
An SH.P.K. uses the NIPT (NUIS) from the QKB registration, for example L81315001A. A person uses the NID (numri personal) from the ID card, for example I50101001A. A self-employed person may use a NIPT of the same 10-character shape. Both examples show the format only. Do not add the AL prefix. The check letter is not verifiable.
Why does Upwork or AdSense withhold 30%?
Usually the form was not filed, or the income type was chosen as US-source royalties or dividends. Services performed from Albania are foreign-source. Ad revenue attributed to US viewers stays at 30%. The form documents the foreign-source status so the platform does not withhold service fees by mistake.
What to do next
- Fill out W-8BEN-E in the guided wizard: Start the W-8BEN-E wizard ($30). It leaves Part III blank.
- Are you a person fizik?: Use the W-8BEN wizard ($5).
- A company in Serbia: W-8BEN-E for a Serbian d.o.o..
- A company in Bosnia and Herzegovina: W-8BEN-E for a Bosnian d.o.o..
- A company in North Macedonia: W-8BEN-E for a Macedonian DOOEL.
- A company in Montenegro: W-8BEN-E for a Montenegrin DOO.
Mistakes that get the form sent back
- Treating the 1995 investment treaty as a tax treaty: It does not give a reduced rate. Do not type it on Line 14b or Line 15.
- A citizenship treaty instead of residence: An Italian citizen who is a tax resident of Albania does not claim the US–Italy treaty. Benefits follow tax residence.
- Rates from treaties with third countries: A treaty Albania has with another country does not apply to a US payer. Dividends from US stocks stay at 30%.
- Form W-8BEN-E from a person fizik: A person fizik files Form W-8BEN, even with a NIPT.
- An AL prefix on the NIPT: Type the 10 characters only, for example L81315001A. Do not add AL.